Ute Finance for Tradies, Field Service Operators & Small Business
Equifund finances utes for Australian ABN holders and trade businesses, also known as dual-cab or light commercial vehicle finance. BAS and trade income assessed directly, with low-doc options available. Toyota HiLux, Ford Ranger, Isuzu D-Max, Mitsubishi Triton, Mazda BT-50 and Nissan Navara, with tray, canopy or service-body fit-outs bundled into one chattel mortgage, finance lease or operating lease.
- Pre-approval inside 24 hours
- $0 deposit for prime applications
- Wide specialist lender panel
- New, used, dealer or private-sale utes
30-second check. No impact on your credit score.
Choose Your Industry
Choose the category that best describes your finance requirement.
No obligation. Soft credit check only.
Built for Tradies & Operators, Backed by Specialists
Equifund matches Australian tradies, field service operators, rural and regional operators, and small business fleets to lenders that read trade and business income and ABN history correctly.
Who We Help
Specialist finance for every corner of Australian trade, field service and small business.
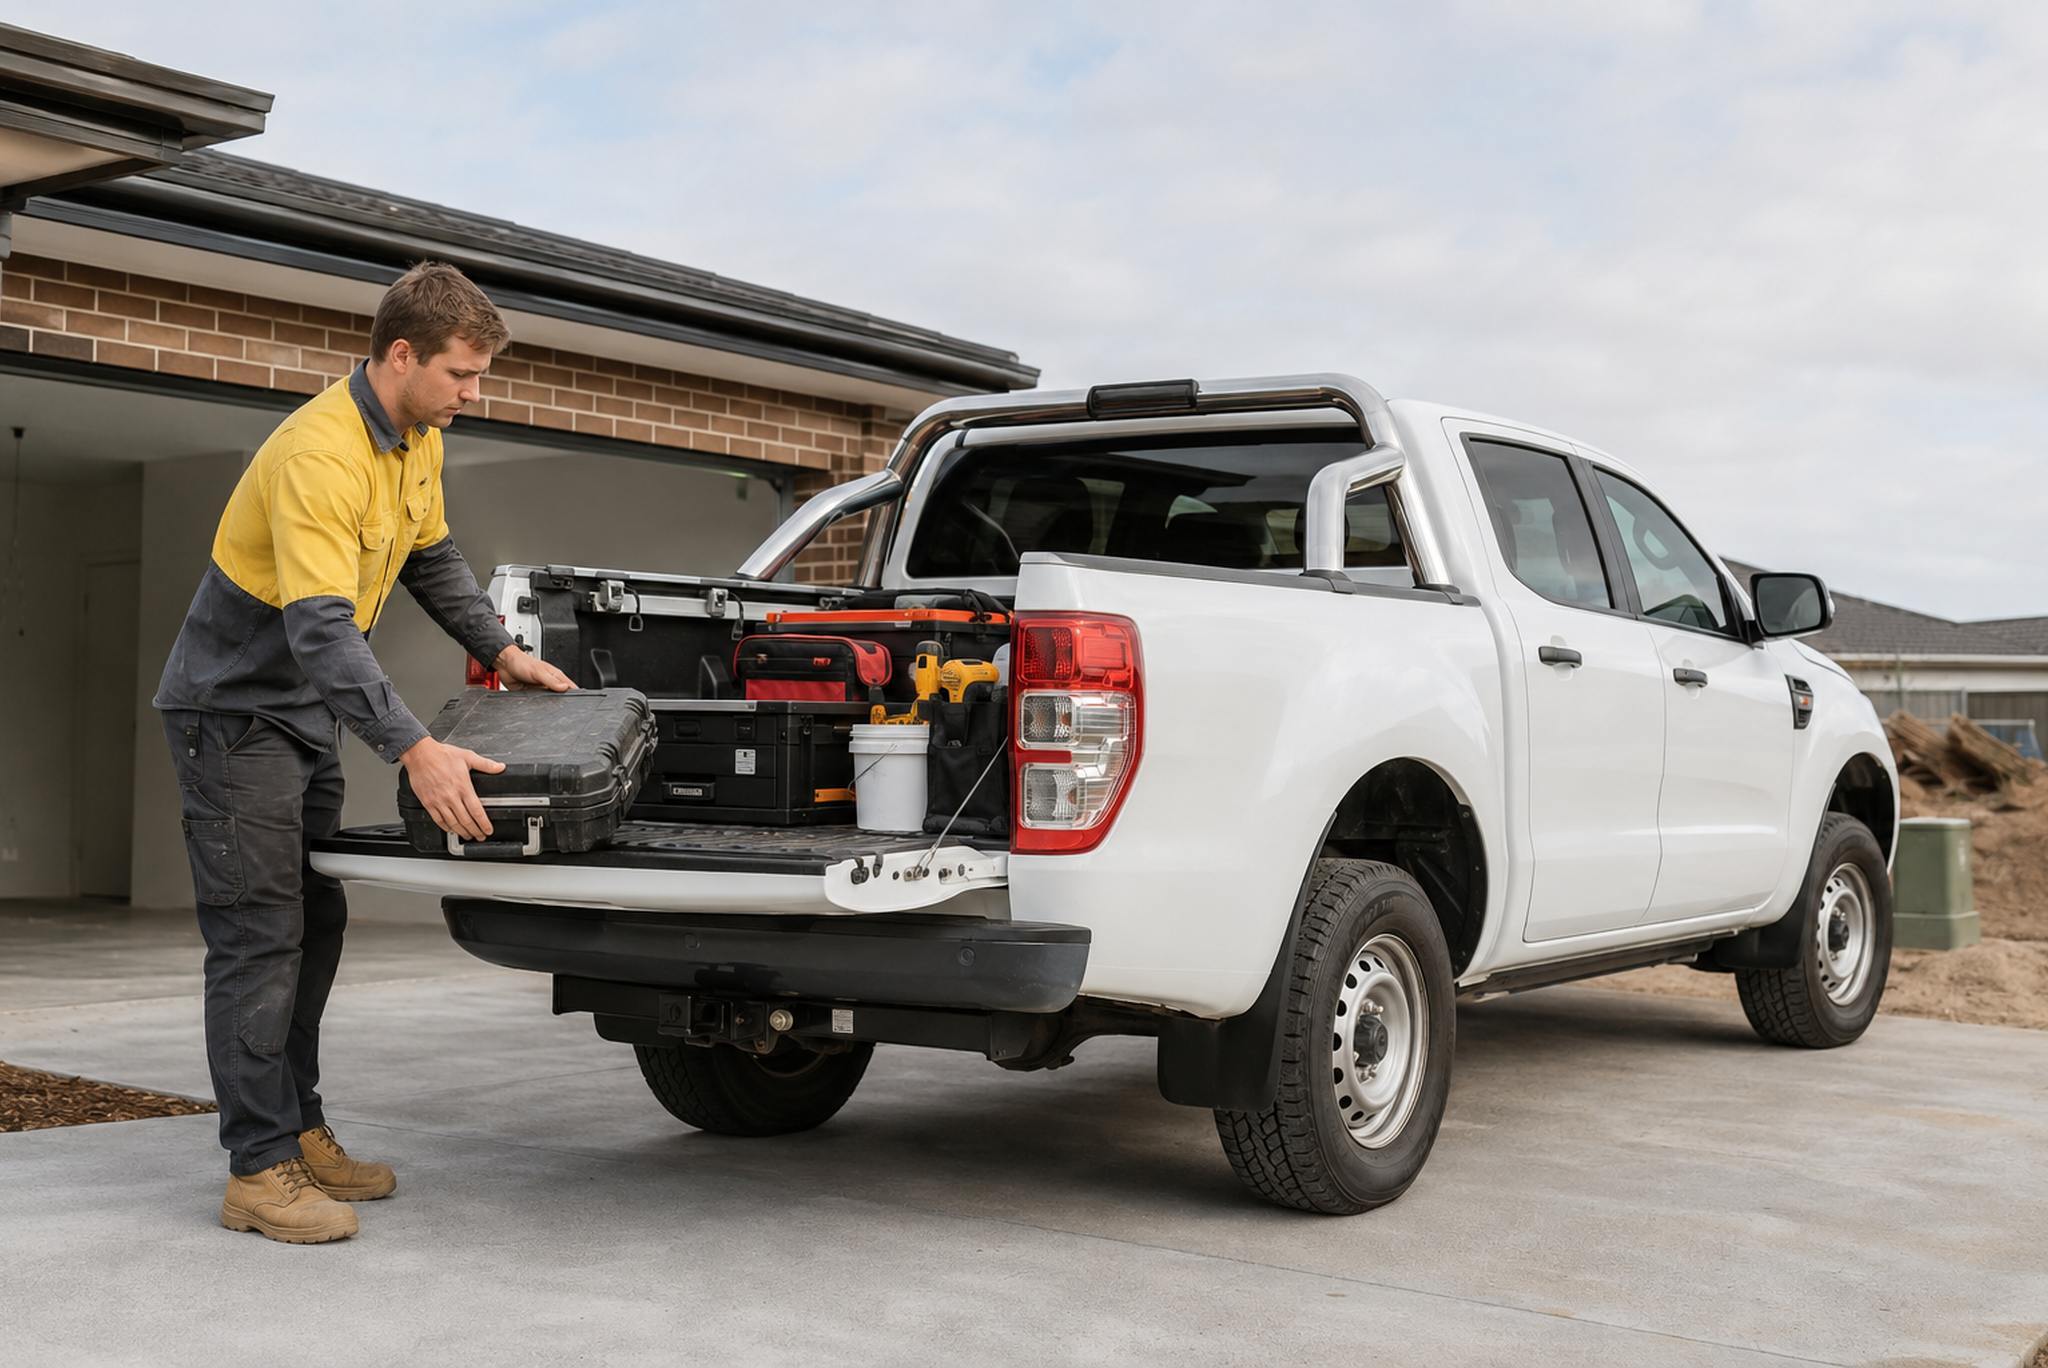 Solo Tradies Buying Their First or Next Ute
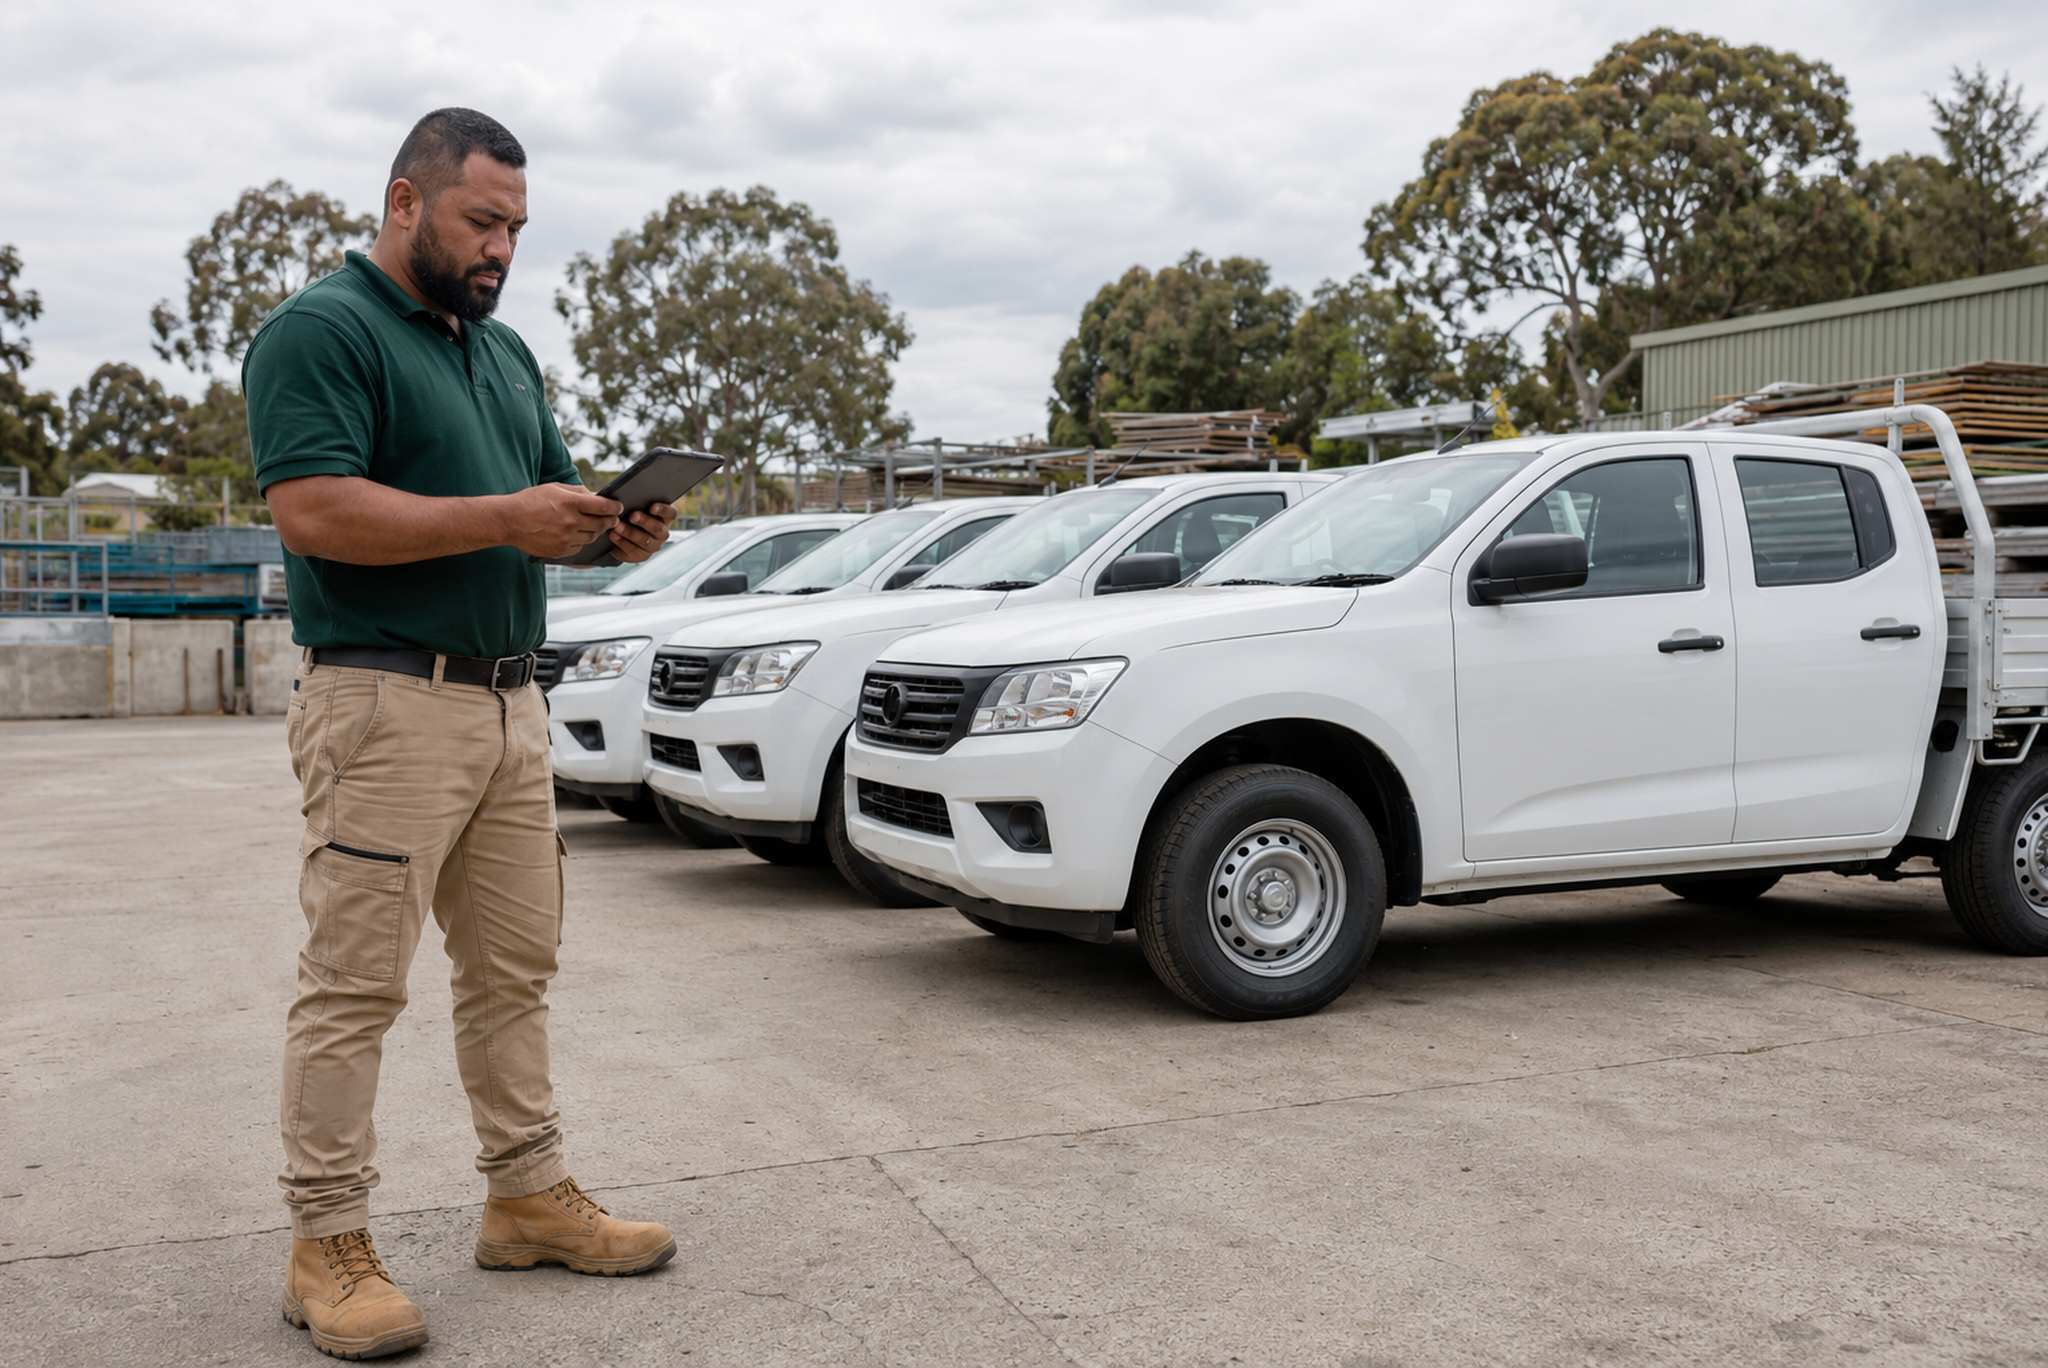 Trade Businesses Standardising a Small Fleet
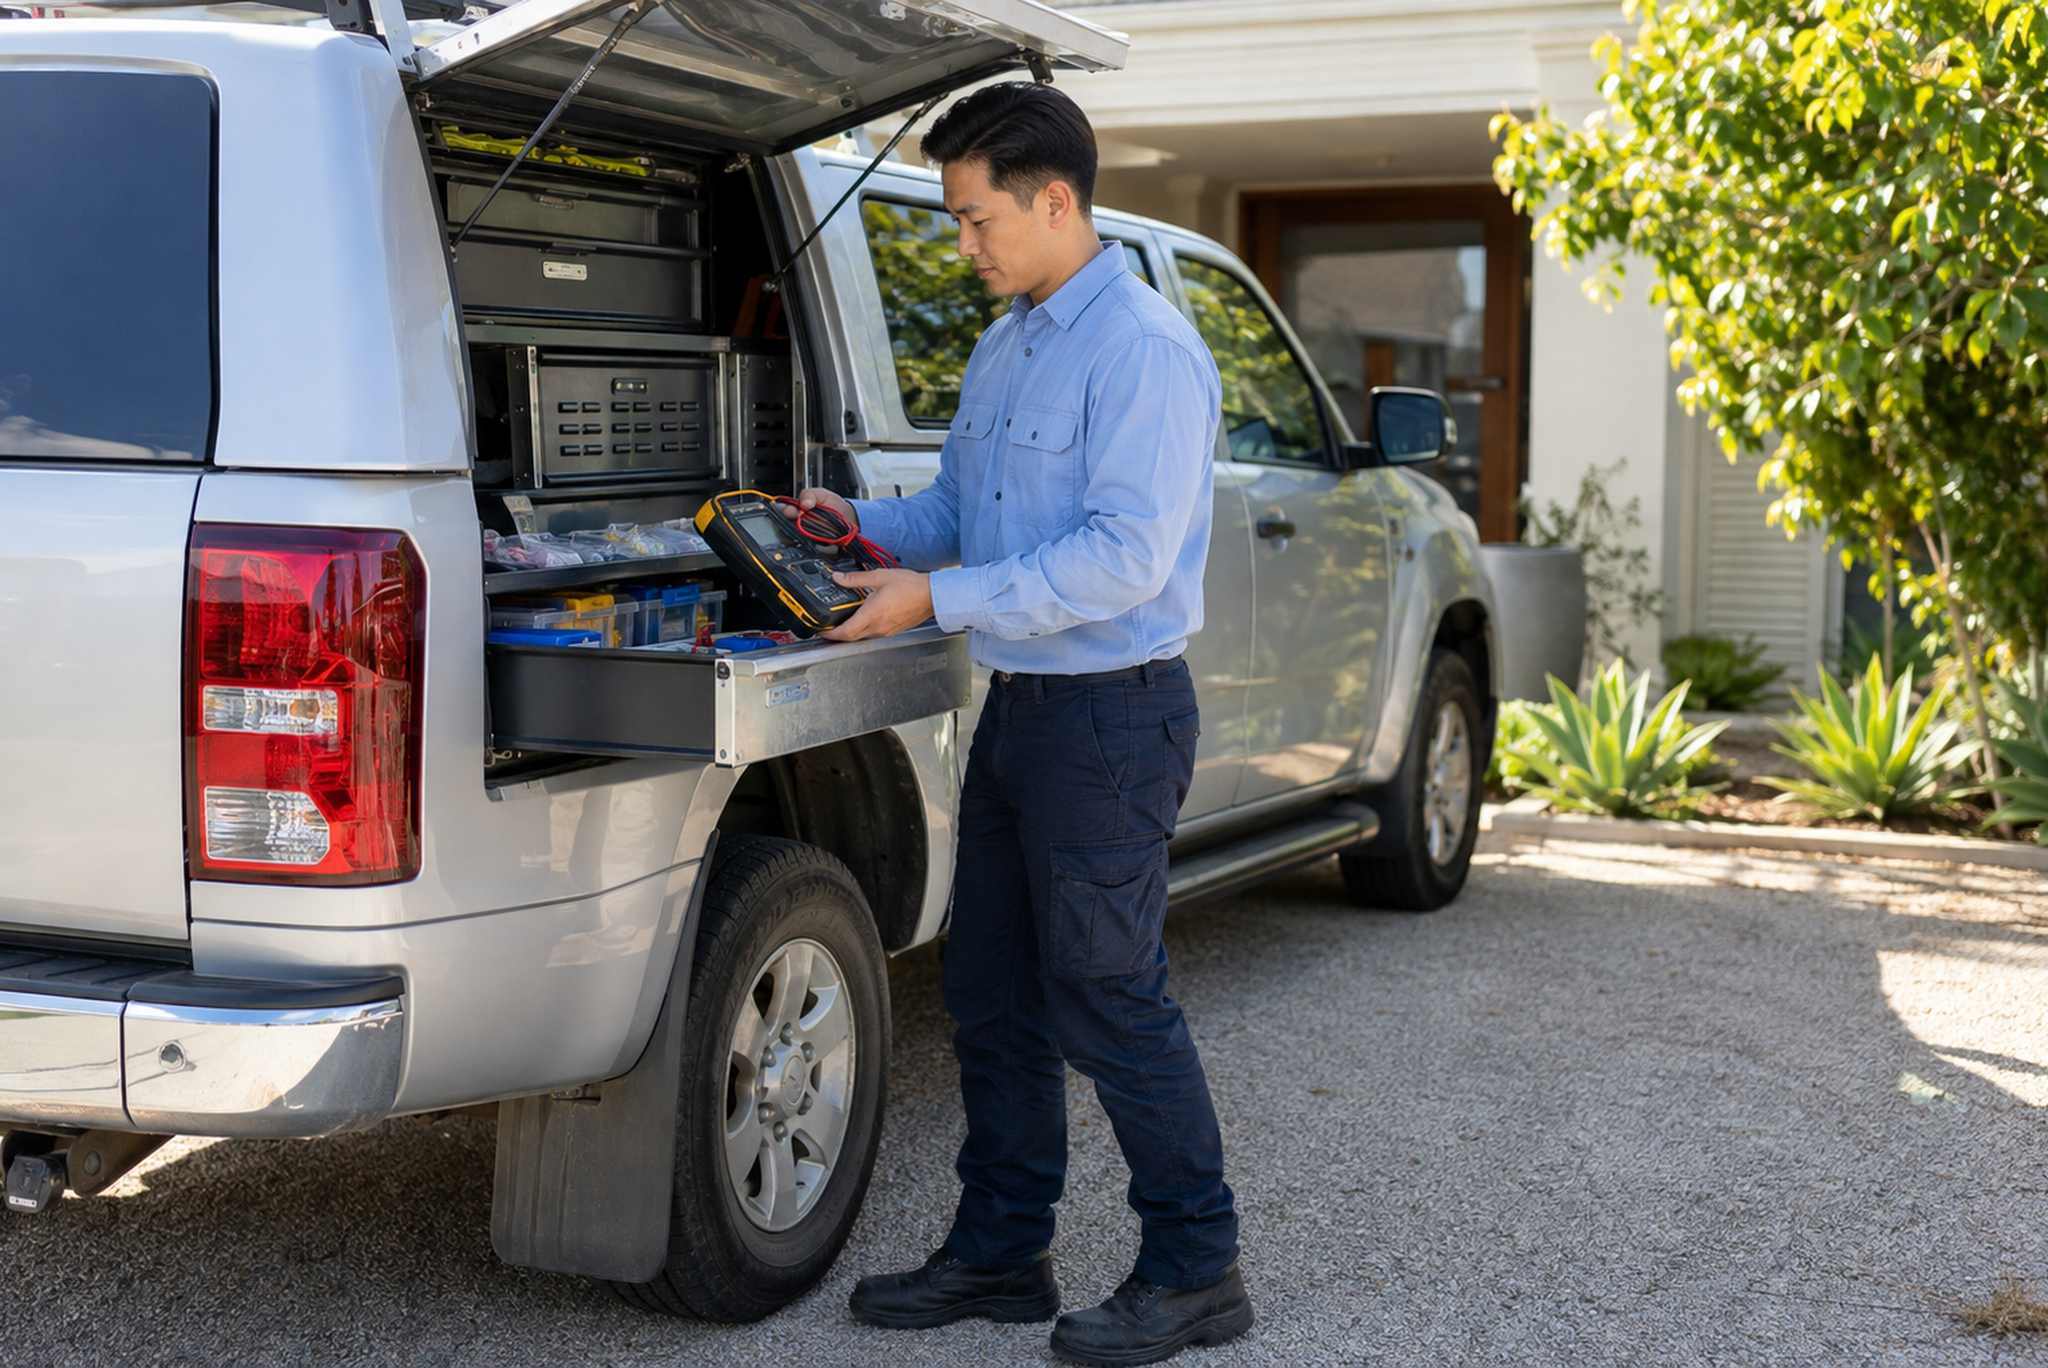 Field Service & Delivery Operators
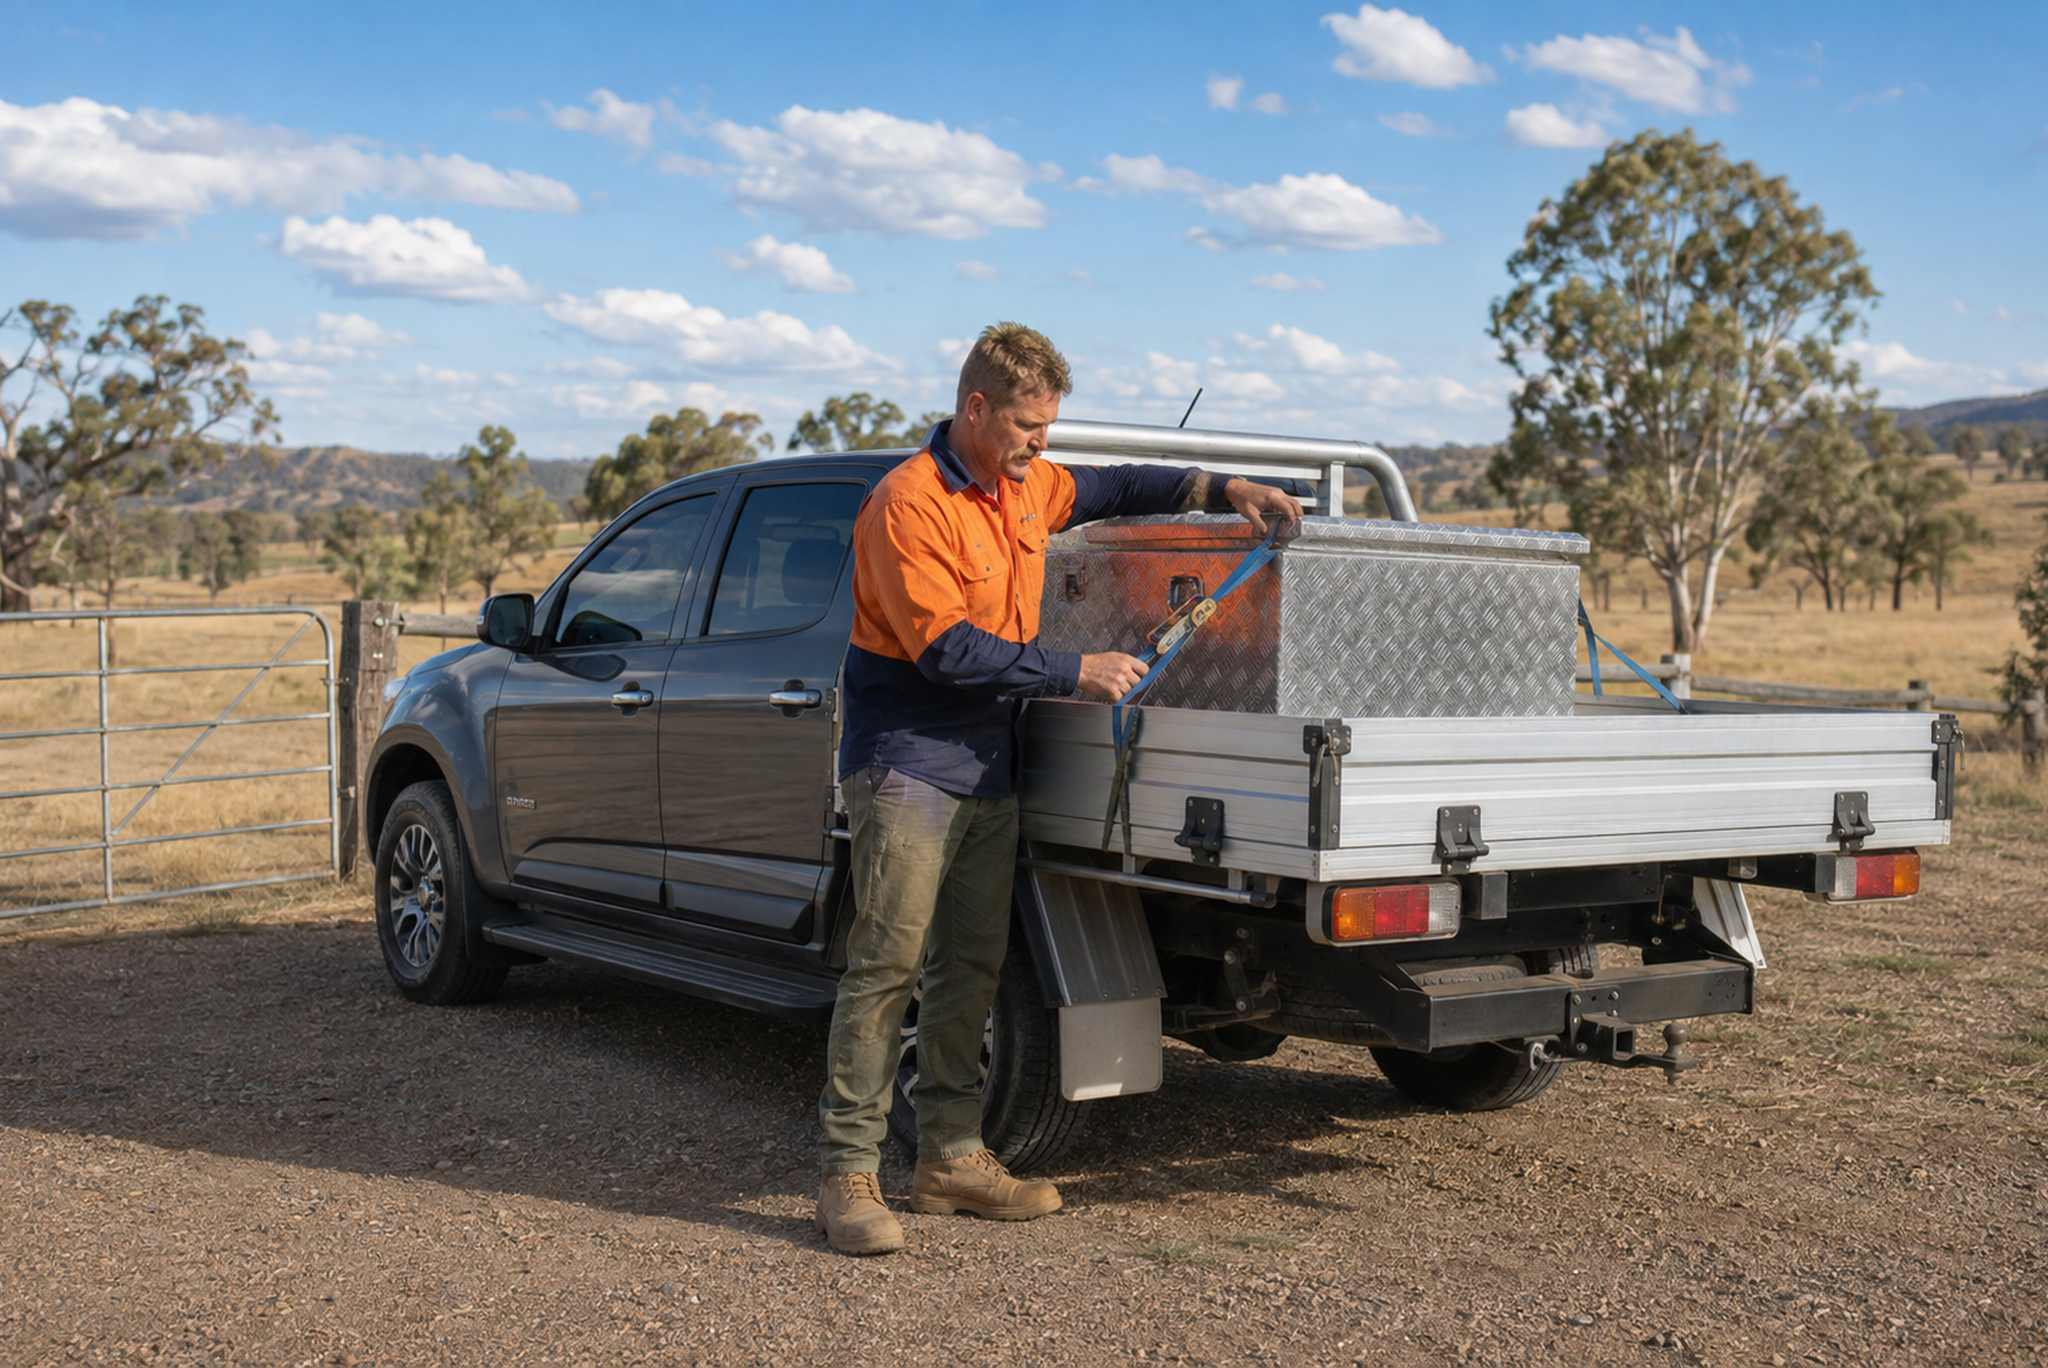 Rural, Regional & Agricultural Operators
Faster Pre-Approvals, Built Around Your Business
Equifund gives you faster pre-approvals and terms built around your trade or small business, not a generic bank policy.
Wide Panel of Australian Lenders, Not One Credit Template
We match your application across a wide panel of specialist lenders instead of one bank's fixed policy.
We Move Quickly So You Are Not Left Waiting
Pre-approval often comes back the same day, so you are not stuck waiting on a job start.
Trade Income and BAS Assessed Directly
Low-doc applications are assessed on your BAS and trade income, not years of financial statements.
Support for Sole Traders and Complex Profiles
New ABNs, casual income and non-standard trading histories are considered case by case.
Which Ute Brands Can I Finance?
Equifund finances Australia's most popular dual-cab utes through specialist lenders that assess a wide range of ABN and trade profiles.
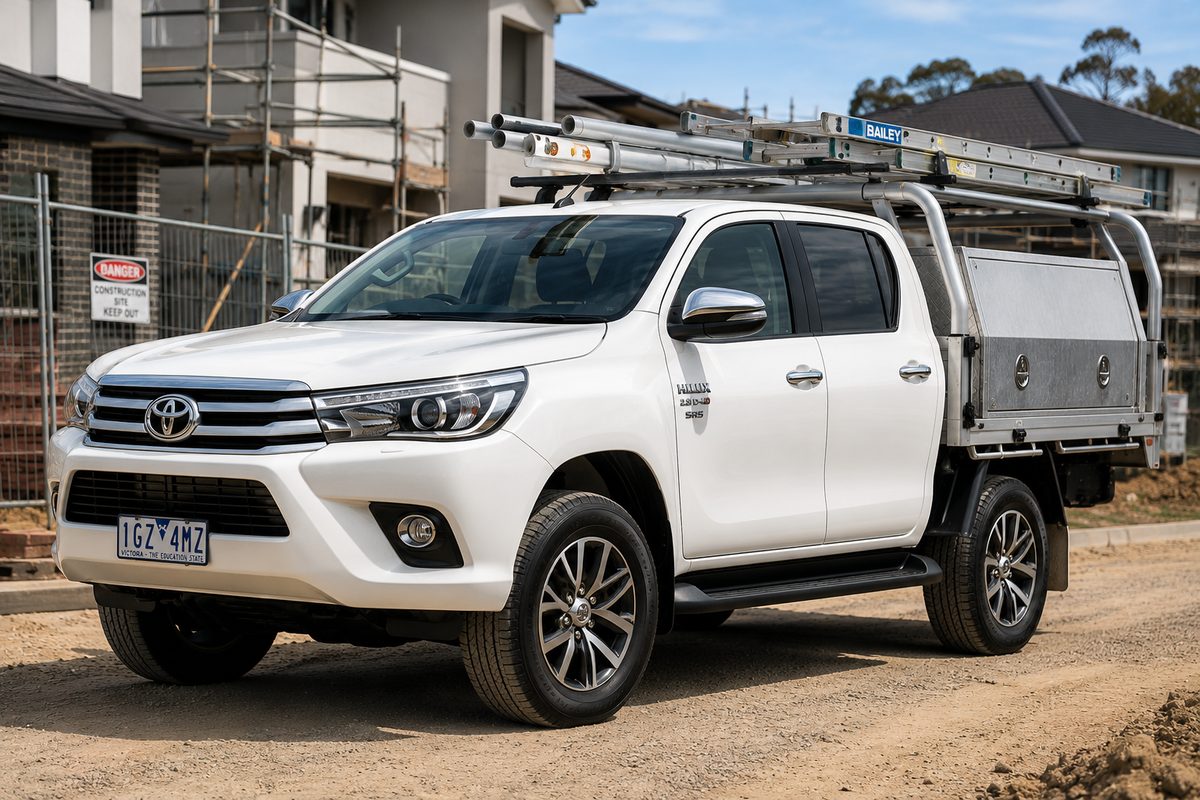
Toyota HiLux
SR, SR5 and Rogue dual-cab and single-cab variants, workhorse reliability with strong resale, financed new or used, plus tray and canopy fit-outs. Up to 1-tonne payload and 3,500kg braked towing across the range.
SR, SR5 and Rogue dual-cab and single-cab, new or used.
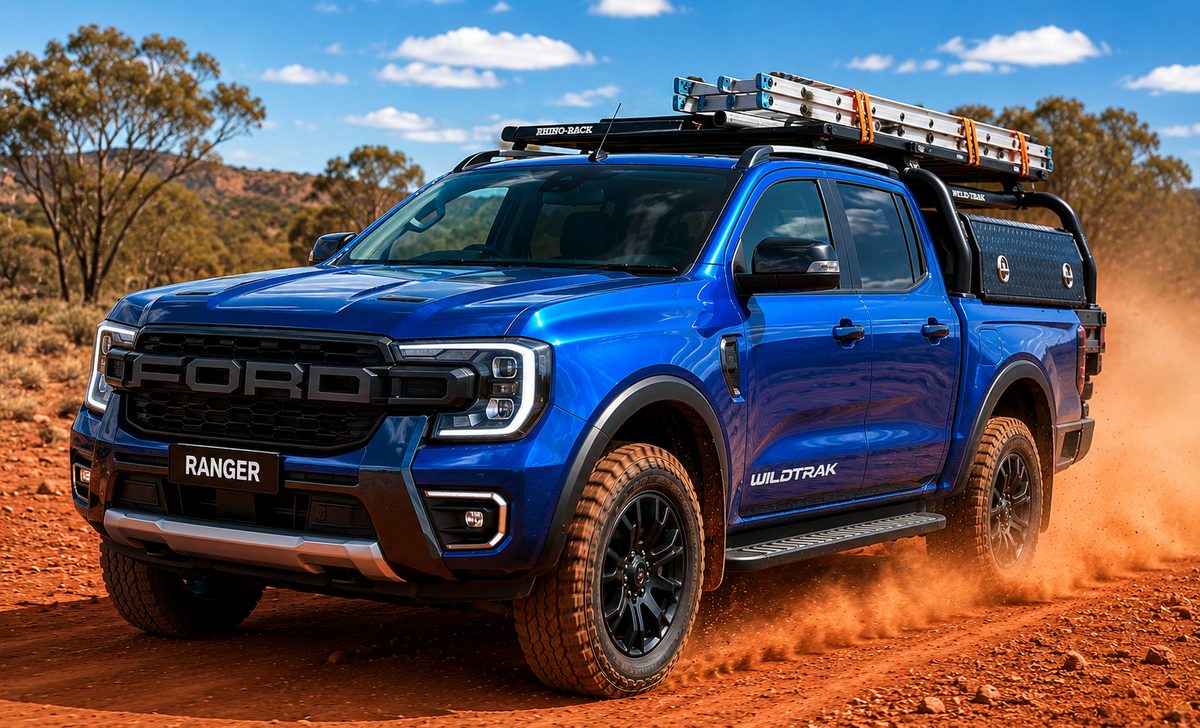
Ford Ranger
XL, XLT, Sport and Wildtrak grades, a strong payload and towing package for trade and field-service work, new or used. Up to 1-tonne payload and 3,500kg braked towing across the range.
XL, XLT, Sport and Wildtrak grades, new or used.
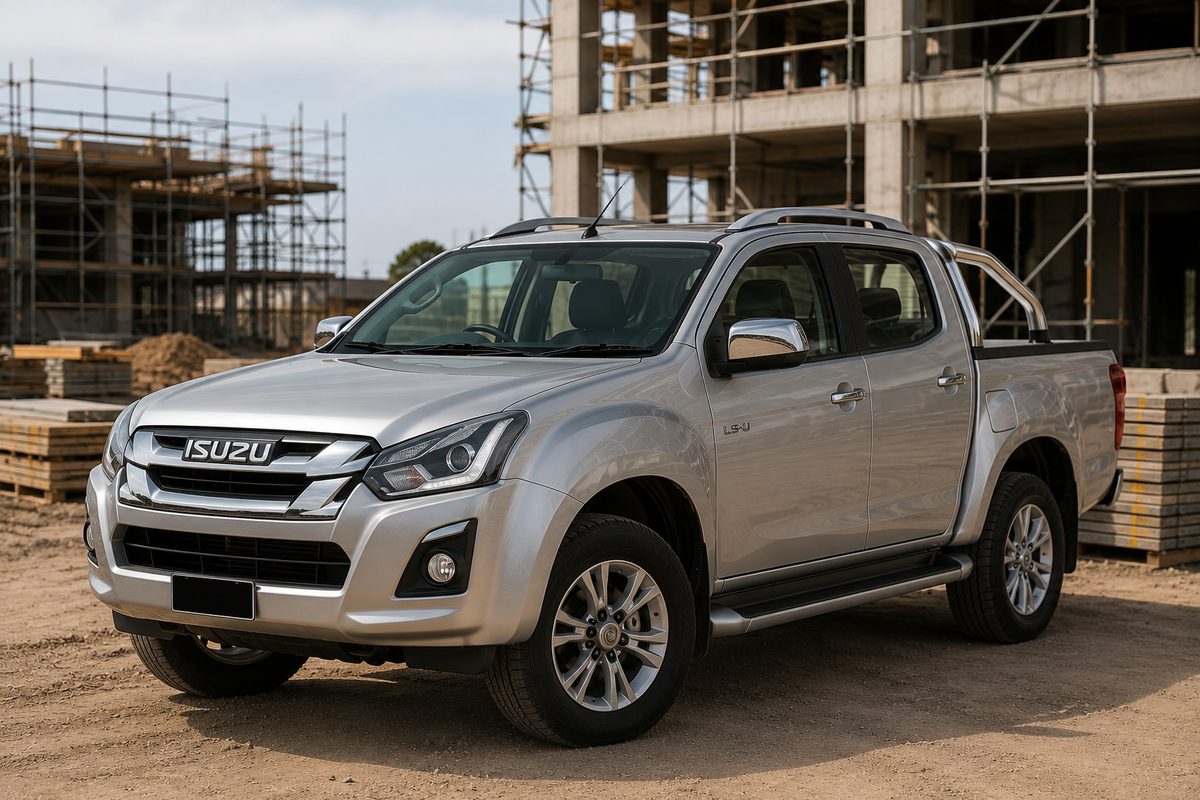
Isuzu D-Max
SX, LS-U and X-Terrain grades, a common choice for small fleets standardising on one model, new or used. Up to 1-tonne payload and 3,500kg braked towing across the range.
SX, LS-U and X-Terrain grades, new or used.
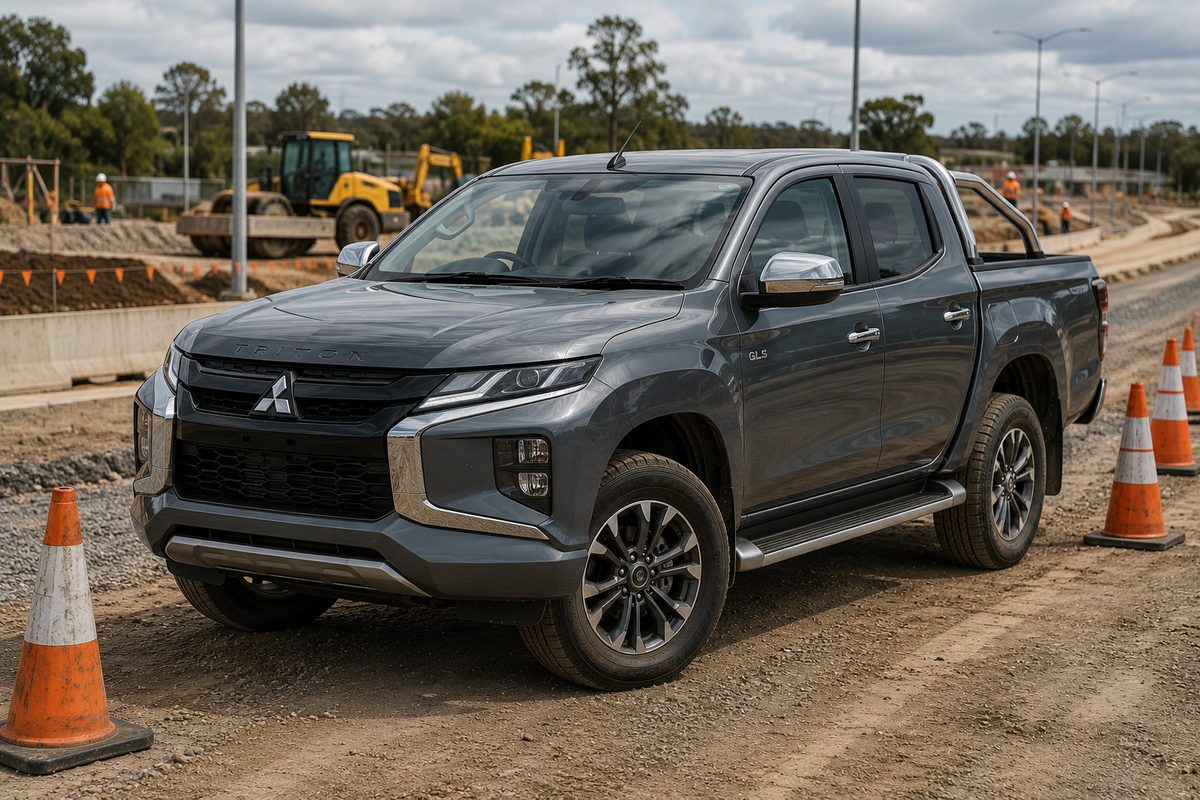
Mitsubishi Triton
GLX, GLS and GSR grades, a popular choice for service-body and canopy fit-outs on a competitive price point, new or used. Up to 1-tonne payload and 3,500kg braked towing across the range.
GLX, GLS and GSR grades, new or used.
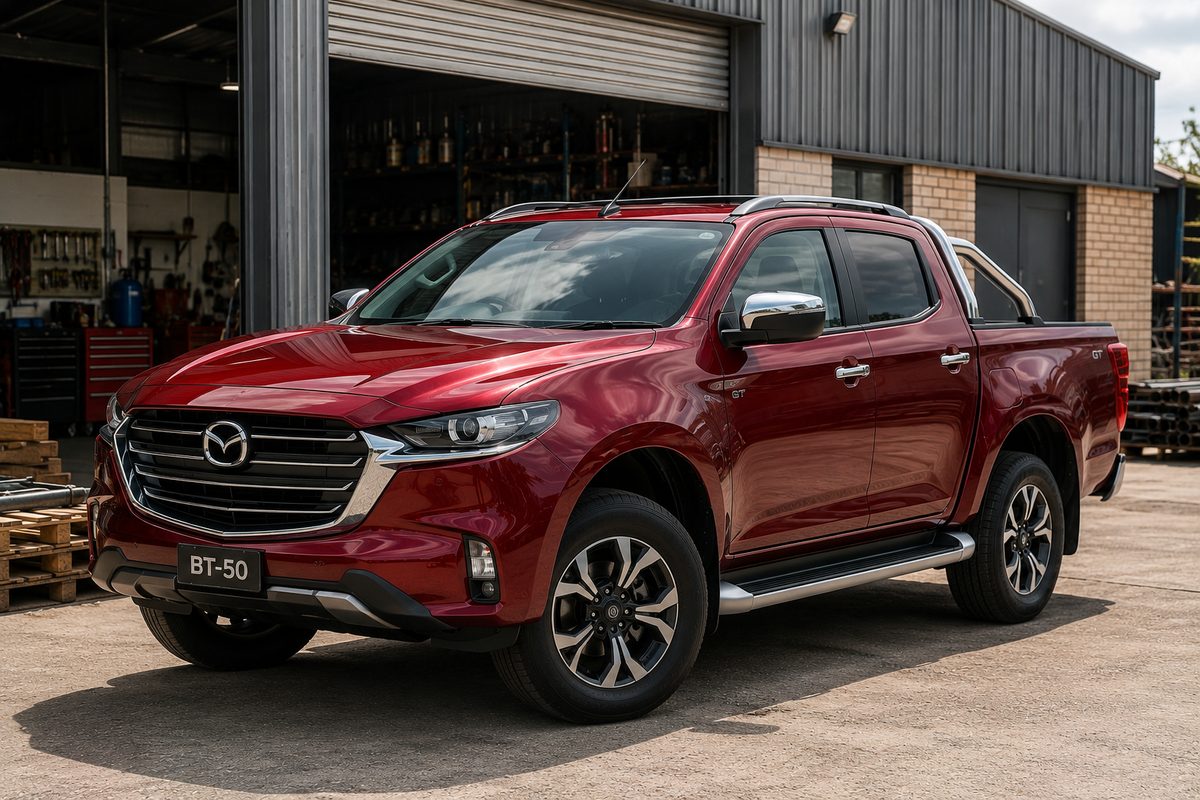
Mazda BT-50
XT, XTR and GT grades, suited to field service operators wanting a comfortable daily field vehicle, new or used. Up to 1-tonne payload and 3,500kg braked towing across the range.
XT, XTR and GT grades, new or used.
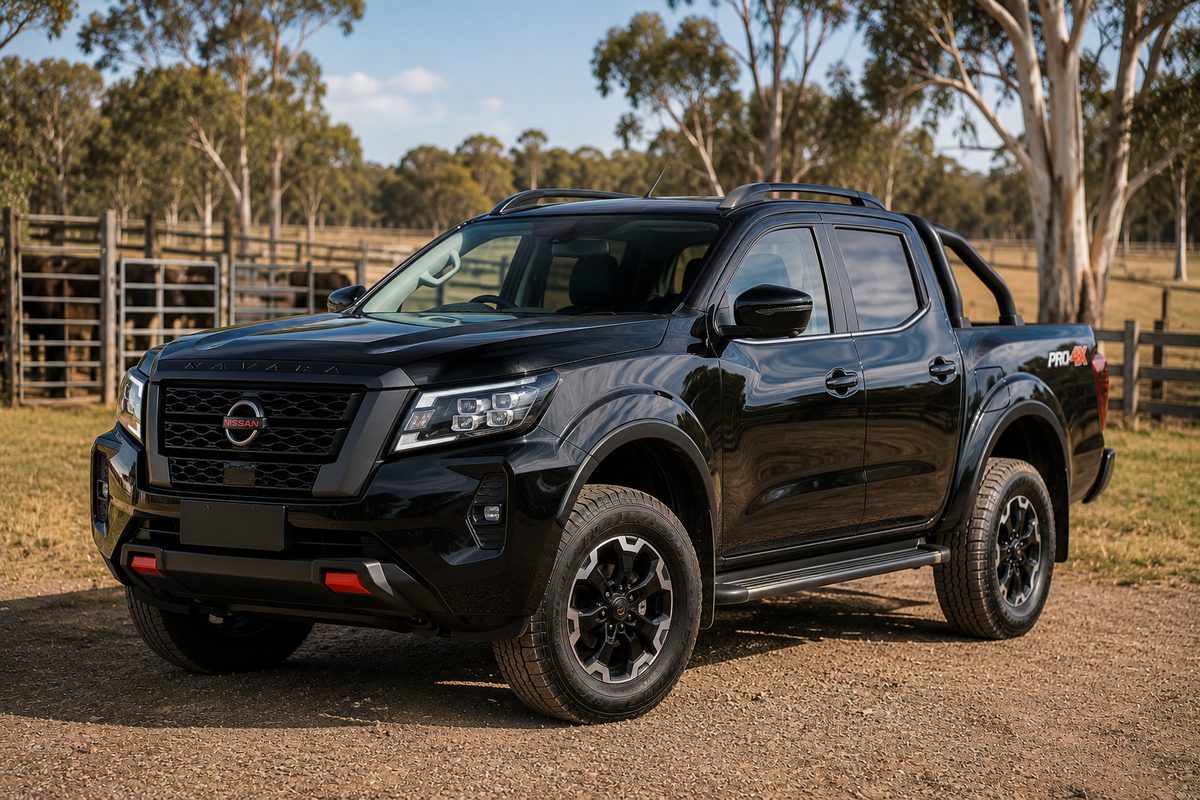
Nissan Navara
SL, ST and PRO-4X grades, a common pick for rural, regional and remote-site work, new or used. Up to 1-tonne payload and 3,500kg braked towing across the range.
SL, ST and PRO-4X grades, new or used.
Plus LDV T60, GWM Cannon, Volkswagen Amarok and RAM 1500. If your brand is not listed, we still finance it.
Why Australian Operators Choose Equifund for Ute Finance
A bank applies a generic credit template. Here is how a specialist ute finance broker reads your trade income and asset value the way a major bank or dealer will not.
Equifund (Ute Finance Specialist)
Built around your deal
- Pre-approval often inside 24 hours
- Reads trade and business income correctly
- $0 deposit on prime applications
- Funds deals outside standard bank policy
- New, used, ex-fleet, private-sale or dealer
Major Bank
Traditional lending
- Generic template for property-backed borrowers
- Full financials and property security required
- Sole-trader or new-ABN deals can fall outside policy
- One product, limited structure flexibility
Dealer / In-house Finance
Point of sale
- Convenient when buying from the yard
- Limited to that dealer's stock and brands
- Less flexibility to structure the deal
- Not built for private-sale or auction buys
Clear Terms. No Unnecessary Complexity. Fast Outcomes.
A straightforward path designed to move you from application to pre-approval quickly.
Complete the Form in 60 Seconds
Tell us about your trade business and the ute you are financing through our secure online form.
Speak With a Ute Finance Specialist
An Australia-based ute finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get Pre-Approved Over the Phone
You'll have a clear pre-approval often within 1 business day, with rate, term and repayment structure tailored to how your trade income actually flows.
Settle the Loan and Take Delivery
Your specialist sources the strongest matched offer and coordinates settlement with the dealer, private seller or auction house.
Real Results for Australian Operators
See how Australian tradies, field service operators and small business fleets are getting the utes they need, even with complex profiles.
What Other Equipment Can I Finance?
Equifund finances every major commercial asset class for prime ABN profiles, backed by a wide lender panel.
 Trucks
 Semi-Trailers & Trailers
 Refrigerated Trucks
 Excavators & Loaders
 Cranes & Site Machinery
 Trailer Trucks
 Tractors & Harvesters
 Yellow Goods
 Skid Steers & Access EquipmentTrucksSemi-Trailers & TrailersRefrigerated TrucksExcavators & LoadersCranes & Site MachineryTrailer TrucksTractors & HarvestersYellow GoodsSkid Steers & Access Equipment

Apply for Your Ute Finance
Three quick steps. An Australia-based ute finance specialist gets back to you the same business day.
 Business Details
 Contact Information
 Asset Information
What Our Clients Have to Say
Rated 5.0 on Google by Australian tradies, field service operators and small business fleets for fast pre-approvals, flexible terms and specialist service. 5.0 ★ · Real Google reviews
Have Questions?
Equifund answers the questions Australian tradies, field service operators and business owners ask most about ute finance.
What is ute finance?
Ute finance is a commercial finance product for ABN-holding businesses that need a dual-cab utility vehicle. It is structured as a chattel mortgage, finance lease, operating lease or hire purchase, with the ute securing the loan and the interest and depreciation generally deductible for business use. Equifund sources ute finance through a wide panel of specialist lenders.
Who qualifies for ute finance?
ABN holders with an active trading history of 12 months or more qualify for standard ute finance. Established businesses trading 2+ years qualify for low-doc ute finance, which uses BAS and bank statements rather than full tax returns. Sole traders, partnerships, companies and trusts all qualify, the ABN is your primary assessment basis, not property ownership.
What types of businesses does Equifund finance utes for?
Equifund finances Australian ABN holders across trade, field service and rural sectors: solo tradies buying their first ute, trade businesses standardising a small fleet, field service and delivery operators running daily routes, and rural, regional or agricultural operators working property and remote-site jobs. Lenders assess trade and business income and ABN history rather than requiring years of financials.
What ute brands can Equifund finance?
Equifund finances all major ute brands in Australia including Toyota HiLux, Ford Ranger, Isuzu D-Max, Mitsubishi Triton, Mazda BT-50, Nissan Navara, LDV T60, GWM Cannon, Volkswagen Amarok and RAM 1500. Both new and used variants across all grades are financeable through the wide lender panel.
Can I finance a used or second-hand ute?
Yes. Equifund finances new, ex-demo, fleet-returned and used dual-cab utes including private-sale and auction purchases. Lender criteria on used utes typically relate to age and odometer; most specialist lenders will finance utes up to 10 years old or 200,000 km at time of purchase. Major banks are often more restrictive on used and private buys.
Is ute finance available for a small fleet?
Yes. Small fleet finance of 2 to 10 vehicles is available as separate individual loans or under a master facility, depending on the lender and the business profile. Fleet structures often allow staggered settlements so vehicles can be delivered progressively. Larger fleets of 10+ vehicles are handled as a commercial fleet account.
What is a Chattel Mortgage for ute finance?
You own the ute from the day finance settles, while your lender holds a mortgage over it as security until the loan is repaid. It's the most requested structure for GST-registered tradies and small businesses, since you can typically claim the GST back on the purchase price straight away and depreciation runs through your own business. Best for GST-registered operators wanting full ownership from day one, with terms from 1 to 7 years.
What is Hire Purchase for ute finance?
With hire purchase, the lender owns the ute for the life of the agreement and you make fixed repayments to use it, with ownership transferring to you once the final payment clears. It suits tradies who want the certainty of a fixed repayment structure, and the GST is spread across your payments rather than claimed as one lump sum upfront. Terms are flexible.
What is a Finance Lease for ute finance?
Under a finance lease, your lender retains legal title to the ute for the term of the lease while you use it for work, making regular lease payments that are typically fully tax deductible. At the end of the term you can make an offer to buy the ute, refinance the residual, or hand it back. Best for operators preferring an off-balance-sheet structure, with flexible terms.
What is an Operating Lease for ute finance?
An operating lease means you pay to use the ute for an agreed term, and your lender carries the risk of its residual value, not you. It suits small fleets that like to keep their utes current, since bundled servicing is often included and you simply hand it back and roll into a newer ute when the term ends. Terms typically run 3 to 5 years.
What is an Unsecured Business Loan for ute finance?
With an unsecured business loan, funds are assessed against your business's trading position rather than security over the ute itself, so you can move quickly on a private sale or older ute a traditional lender might decline. Best for fast settlement or older utes, with a shorter, flexible term.
Can I claim the GST on ute finance?
Under a chattel mortgage, GST-registered businesses can generally claim the GST on the purchase price on their next BAS. Under a finance lease, GST is recovered through the lease rentals instead. Treatment depends on your business structure and use of the vehicle, so confirm with your accountant before you apply.
Can I get $0 deposit on a ute?
Yes, for prime ABN profiles. $0 deposit ute finance is available when the business has a clean credit file, 2+ years trading history, and the ute is a standard commercial variant. A small deposit may be required for lower-doc or short-ABN-history applicants.
Can I finance a ute tray, canopy or accessories?
Yes. Canopies, trays, toolboxes, service bodies and fit-outs can typically be rolled into the same finance facility as the ute, provided they are permanently fixed to the vehicle. This keeps the transaction simple and avoids a separate personal loan for accessories. Get the accessory pricing from your dealer and include it in your application.
Chattel mortgage or finance lease, which is better for a ute?
Chattel mortgage suits GST-registered tradies who want to own the ute from day one and claim the GST and depreciation upfront; the ute sits on your balance sheet as an asset from settlement. Finance lease suits operators who prefer to keep the ute off their own balance sheet, claiming the lease payments as a tax deduction instead and deciding at the end of term whether to buy, refinance or hand it back. Most sole traders and small fleets choose chattel mortgage for the upfront GST and depreciation benefit; finance lease is more common for operators managing balance-sheet position or planning to cycle the ute at term end.
How quickly can ute finance be pre-approved?
Standard ute finance applications from established ABN holders are typically pre-approved within 2 to 4 business hours. Same-day pre-approval is common for prime profiles with clean credit and 2+ years ABN history. A short online application and basic business documents are all that is needed to get started.
How much can I borrow for a ute?
Loan amounts commonly range from around $20,000 for a late-model used ute to $120,000 or more for a new dual-cab with a service body and accessories. Fleet finance of 3 or more vehicles can be structured under a master facility. Loan amount is assessed on the business income and the asset value, not a fixed cap.
What documents do I need to apply for ute finance?
For a standard application: ABN, driver's licence, last 2 BAS statements and last 3 months business bank statements. For low-doc: ABN, driver's licence, 6 months BAS and an accountant's letter or 12 months bank statements. Full financial statements and tax returns are not required for most prime ABN profiles.