Business Car Financefor Australian ABN Holders
Specialist business car finance for established Australian ABN holders, from tradie utes to small-business SUVs, mobile-professional sedans and EV company cars. BAS and trading history assessed directly. Chattel mortgage, novated lease and finance lease options, settled fast and matched to how your business actually earns.
- Pre-approval inside 24 hours
- $0 deposit for prime applications
- Wide specialist lender panel
- New, used, dealer or private-sale vehicles
30-second check. No impact on your credit score.
Choose Your Industry
Choose the category that best describes your finance requirement.
No obligation. Soft credit check only.
Built for Business, Backed by Specialists
Whether you run a tradie ute, a client-facing SUV, or a small fleet, Equifund matches you to lenders that read business income and vehicle value correctly.
Who We Help
Specialist finance for every corner of Australian business motoring.
 Tradies & Contractors
 Small-Business Owners
 Mobile Professionals
 Small Fleet Operators
 EV & FBT-Exempt Buyers
Why Choose Us
Faster pre-approvals and terms built around your business.
Higher Pre-Approval Rates for Business Vehicles
We Move Quickly So Your Vehicle Is Not the Bottleneck
Repayments Structured Around Your Cash Flow
Support for Sole Traders and Non-Standard Profiles
Which Business Car Brands Can I Finance?
Every major business car brand on the Australian market, financed through specialist lenders for prime ABN profiles.
Toyota
HiLux (Workmate, SR, SR5, Rogue), HiLux GR Sport, Camry, RAV4 (incl. Hybrid), Prado, LandCruiser 79 / 300 Series, HiAce van and Corolla. Australia's #1 selling vehicle brand for tradies, sole-trader mobile professionals and small-business fleets.
Vans
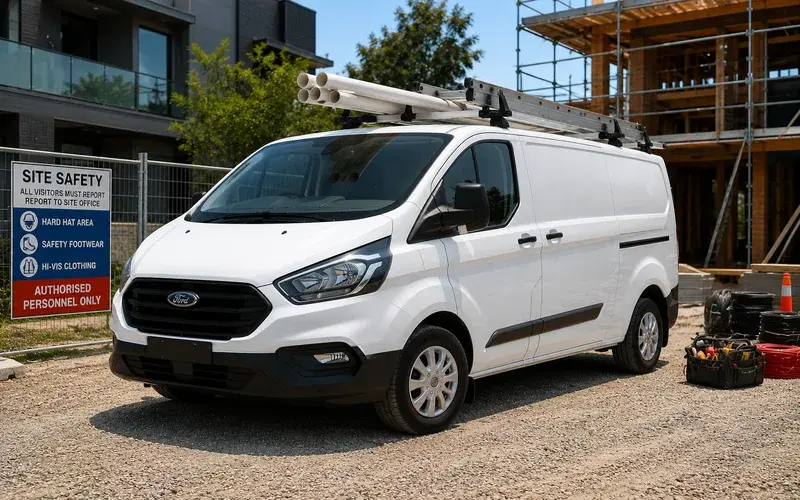
Toyota HiAce, Hyundai Staria Load, Ford Transit Custom and Transit, LDV Deliver 9 and Volkswagen Transporter. The HiAce was the top-selling medium van in Australia in January 2026, with the Staria Load and Transit Custom rounding out the top three. Built for trades, delivery and mobile-service businesses needing cargo space over ute tray capacity.
Ford
Ranger (XL, XLT, Sport, Wildtrak, Raptor), Everest, Transit Custom and Transit van, Puma and Escape SUV. The Ranger has dominated AU ute sales since 2023, with the strongest tradie and small-fleet buy-rate.
Mazda
BT-50 (XS, XT, GT, SP), CX-5, CX-60 PHEV, CX-90, Mazda 3 sedan and hatch, Mazda 6 sedan and wagon. The CX-5 is the most-financed mid-size SUV in the Australian commercial-buyer market.
Mitsubishi
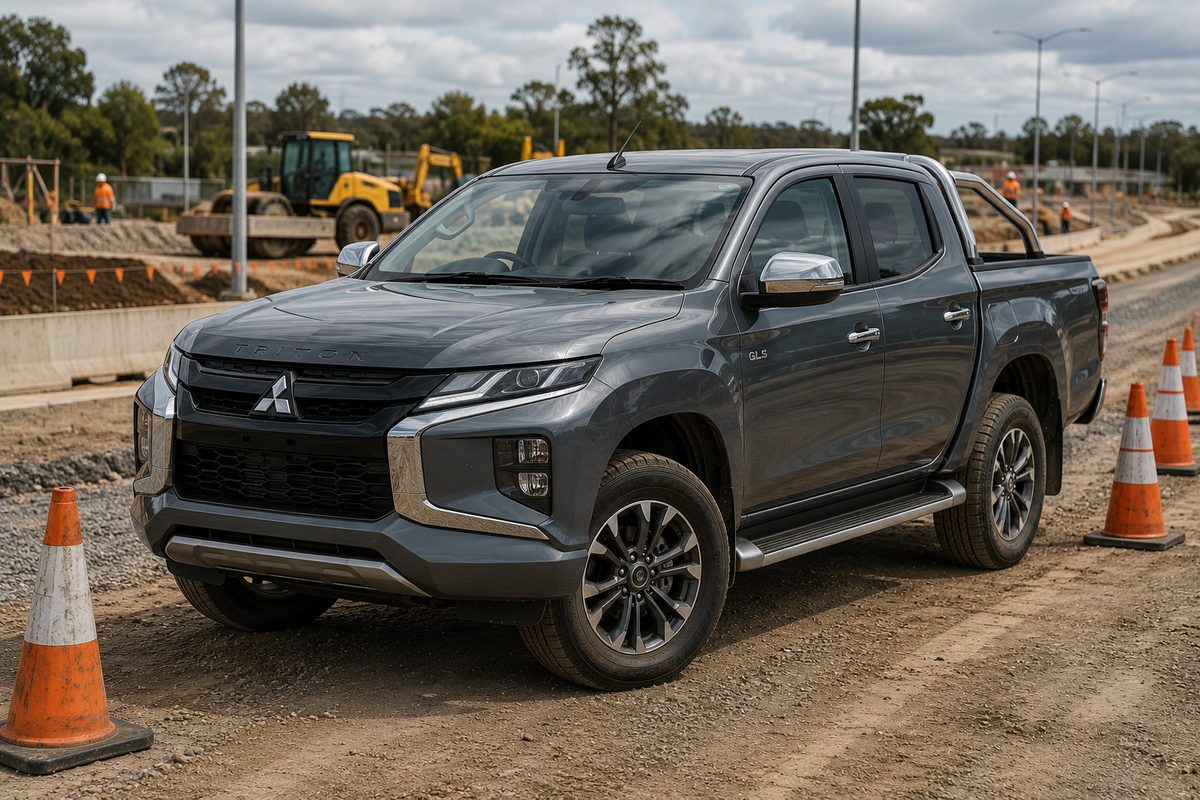
Triton (GLX, GLX-R, GLS, Exceed), Outlander (incl. PHEV plug-in hybrid), ASX, Pajero Sport 4WD and Eclipse Cross. The Outlander PHEV is the #1 plug-in hybrid SUV in AU, a popular FBT-exempt pick for sole-trader mobile professionals.
Isuzu Ute
D-Max (SX, LS-M, LS-U, X-Terrain, Blade) and MU-X 7-seat 4WD. D-Max is one of the top three selling utes in Australia alongside HiLux and Ranger, the workhorse choice for tradies. MU-X covers the tradie-family 4WD slot.
BYD
Atto 3, Dolphin, Seal sedan, Sealion 6 PHEV SUV, Sealion 7 and Shark 6 plug-in hybrid ute. The fastest-growing EV brand in Australia since 2022. The Shark 6 PHEV is the only plug-in hybrid ute on sale in AU, uniquely positioned for tradies wanting FBT-exempt ute capability.
Plus Hyundai, Kia, Tesla, Volkswagen, Nissan, Subaru, Polestar and GWM. If your brand is not listed, we still finance it.
Which Business Car Finance Structure Is Right for You?
Five ways to structure your finance, each suited to a different goal and cashflow position.
Chattel Mortgage
You own the vehicle from the day finance settles, while your lender holds a mortgage over it as security until the loan is repaid. It is the most requested structure for GST-registered ABN holders, since you can typically claim the GST back on the purchase price straight away and depreciation runs through your own business. A balloon payment can be added to lower your regular repayments if that suits your cash flow better.
Hire Purchase
The lender owns the vehicle for the life of the agreement and you make fixed repayments to use it, with ownership transferring to you once the final payment clears. It suits business owners who want the certainty of a fixed repayment structure, and the GST is spread across your payments rather than claimed as one lump sum upfront.
Finance Lease
Your lender retains legal title to the vehicle for the term of the lease while you use it in your business, making regular lease payments that are typically fully tax deductible. At the end of the term you can make an offer to buy the asset, refinance the residual, or hand it back, giving you flexibility as your fleet needs change.
Novated Lease
A three-way agreement between you as the employee, your employer and the lender, where the vehicle is salary-packaged directly from your pre-tax income. Running costs can be bundled into the same payment. Best suited to employees of an established business who want a personal or company car packaged through payroll, including EVs and plug-in hybrids eligible for the FBT exemption.
Unsecured Business Loan
Funds are assessed against your business's trading position rather than security over the vehicle itself, so you can move quickly on a private sale or an older vehicle a traditional lender might decline. It typically comes with a shorter term and can settle the same day, once your trading history has been assessed.
Depreciation and car cost thresholds set by the ATO. Credit licensing regulated by ASIC.
Clear Terms. No Unnecessary Complexity. Fast Outcomes.
A straightforward path designed to move you from application to pre-approval quickly.
Complete the Form in 60 Seconds
Tell us about your business and the vehicle you are financing through our secure online form.
Speak With a Business Car Finance Specialist
An Australia-based business car finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get Pre-Approved Over the Phone
You'll have a clear pre-approval often within 1 business day, with rate, term and repayment structure tailored to how your business actually earns.
Settle the Loan and Take Delivery
Your specialist sources the strongest matched offer and coordinates settlement with the dealer, private seller or auction house.
Real Results for Real Businesses
See how Australian tradies, business owners and fleet operators are getting the business cars they need, even with complex profiles.
What Other Vehicles & Equipment Can I Finance?
Equifund finances every major commercial asset class for prime ABN profiles, backed by a wide lender panel.

Apply for Your Business Car Finance
Three quick steps. An Australia-based business car finance specialist gets back to you the same business day.
 Business Details
 Contact Information
 Asset Information
What Our Clients Have to Say
Rated 5.0 on Google by Australian business owners and ABN holders for fast pre-approvals, flexible terms and specialist service. 5.0 ★ · Real Google reviews
Have Questions?
Straight answers to the questions Australian business owners and ABN holders ask most.
What types of business cars can I finance in Australia?
We finance every category of business car: dual-cab and single-cab utes (Toyota HiLux, Ford Ranger, Mazda BT-50, Mitsubishi Triton, Isuzu D-Max, VW Amarok), 4WDs (Toyota Prado, LandCruiser 79 / 200 / 300, Ford Everest, Pajero Sport, Patrol), mid-size SUVs (Toyota RAV4, Mazda CX-5, Hyundai Tucson, Kia Sportage, Mitsubishi Outlander), large SUVs (Toyota Kluger, Hyundai Santa Fe, Kia Sorento, Mazda CX-9 / CX-90), sedans (Toyota Camry, Mazda 3 / 6, Hyundai i30, Kia Cerato), vans (Toyota HiAce, Ford Transit, Hyundai Staria-Load), 8-seat people-movers (Kia Carnival, Hyundai Staria), EVs (Tesla, IONIQ 5 / 6, EV6 / EV9, BYD Atto / Seal, Polestar) and PHEV / hybrid (RAV4 Hybrid, Outlander PHEV, CX-60 PHEV). New, used, demonstrator, dealer, private sale or fleet-auction purchases all financeable.
Is this consumer car finance or business car finance?
Business car finance, strictly. Equifund arranges asset finance for ABN holders against their business: chattel mortgage, finance lease, novated lease and operating lease. This is not a consumer car loan. The lender assesses your business income, BAS, trading history and the vehicle as the security asset, not your personal pay slip. You claim depreciation and GST on the vehicle, and the structure suits sole traders, partnerships, company directors and small-business fleet operators.
Do I need to own property to qualify?
No. Equifund's specialist lender panel includes options that assess on the asset, your business income and trading history rather than requiring property as security. This matters for owner-operator tradies, sole-trader mobile professionals, real estate agents on commission and small-business fleet operators who don't want to lock the property folio for a sub-$100k vehicle.
Do I need a deposit?
$0 deposit is available for prime applications, especially established ABN holders with active trading history and verifiable business income. New ABNs typically need some contribution, but $0 deposit on the right deal is common for ongoing operators. We can also structure trade-in equity from your existing business car as deposit on the next one.
I'm a tradie buying a Ranger or HiLux for my work ute. How does that work?
Standard business-car finance via chattel mortgage. Your ABN, BAS and trading history are the application basis, not your PAYG pay slip. The ute is the asset and the security. You claim depreciation and GST upfront on the vehicle, and the instant asset write-off (where applicable based on the financial year and your aggregated turnover) can apply to the eligible portion. The Ford Ranger XLT / Sport / Wildtrak, Toyota HiLux SR5 / Rogue, Mazda BT-50 GT and Mitsubishi Triton GLS are the four most-financed work utes through Equifund.
What's the difference between chattel mortgage, novated lease and finance lease for a business car?
Three structures, each with different tax treatment. Chattel mortgage: you own the vehicle, claim depreciation and GST upfront, lender holds security over the asset. Best for sole traders and small companies that want the vehicle on the balance sheet. Novated lease: a three-way agreement between employee, employer and lender where the vehicle is salary-packaged. Best for employees of established businesses who want to package a vehicle pre-tax. Finance lease: lender owns the vehicle, you make rental payments and claim GST on each payment. Best for companies that prefer the vehicle off the balance sheet. We arrange all three across the specialist panel.
Can I finance an EV company car and access the FBT exemption?
Yes. EVs and plug-in hybrids under the luxury car tax (LCT) threshold for fuel-efficient vehicles are eligible for the Electric Car Discount FBT exemption (federal Australian Government, effective from 1 July 2022). We finance Tesla, Hyundai IONIQ 5 / 6, Kia EV6 / EV9, BYD Atto / Seal, Polestar, Mitsubishi Outlander PHEV and Mazda CX-60 PHEV across the specialist panel. The FBT exemption can make a salary-packaged EV materially cheaper than the equivalent ICE vehicle for many drivers; speak to your accountant for the specific calculation on your situation.
What is low-doc business car finance?
Low-doc business car finance is asset finance pre-approved on a reduced document set, typically BAS, bank statements and the dealer invoice or quote, rather than full financials and tax returns. Best suited to established ABN holders with an active business, trading history and verifiable income who don't have current-year financials prepared. Common for sole-trader tradies, sales reps on commission and self-employed mobile professionals.
I am a sole-trader mobile professional. Can I fund a Tesla, BYD or other EV through my ABN and claim the FBT exemption?
Yes. Sole-trader mortgage brokers, accountants, real estate agents on commission, sales reps and mobile services contractors can fund a Tesla Model Y / 3, BYD Atto 3 / Seal / Sealion 6 PHEV, Hyundai IONIQ 5, Kia EV6, Mitsubishi Outlander PHEV or BYD Shark 6 PHEV ute through the business ABN and access the Electric Car Discount FBT exemption (federal Australian Government, effective from 1 July 2022) when the vehicle sits under the LCT threshold for fuel-efficient vehicles. Speak to your accountant for the specific calculation on your situation.
How long does Australia business car finance take to settle?
Pre-approval typically comes back inside a business day when your application is complete. Settlement happens once you have signed contracts, the dealer has confirmed delivery and any final lender conditions are met. Specialist asset lenders move faster than major banks on business-car deals because they assess the vehicle and business income directly rather than waiting on consumer-loan underwriting cycles.
Can I finance a used business car, ex-fleet, private sale or auction purchase?
Yes. Used (including ex-lease / ex-fleet, end-of-cycle dealer demonstrators and high-spec second-hand), private sale and dealer-auction purchases are all financeable through the specialist asset lenders we work with. Major banks typically have age cut-offs that knock out older vehicles; specialist lenders look at the asset condition, kilometres and service history rather than calendar age alone.
Can I refinance an existing business car loan?
Yes. Refinance is common when an existing deal was settled at high rates, has an unfavourable structure (large balloon, restrictive covenants), or is consolidating multiple vehicles into one master facility. We compare your current setup against the specialist panel and present options.
Which lenders does Equifund work with?
A wide panel of Australian lenders spanning major banks, specialist asset financiers and non-bank lenders that specifically understand small-business income, BAS, fleet trading patterns and the residual value of business cars across utes, 4WDs, SUVs, sedans, vans and EVs.
Can I finance multiple business cars in one application?
Yes. Fleet deals (two to twenty vehicles for a business, staged purchases across a 12-month replacement pipeline, or annual rotation cycles for hire / rideshare fleets) are common. The lender panel includes options that split fleet deals across facilities or fund them under one master agreement. For larger fleets we can also bundle insurance and fuel-card programs.
I run a small tradie crew (2 to 5 utes). Can you fund the whole crew on one application?
Yes. Multi-ute tradie crew fleets (typically 2 to 5 Rangers, HiLuxes, BT-50s or Tritons) are the most common business-vehicle deal we arrange. Specialist lenders fund the whole crew on one master facility against the BAS and head-contractor framework rather than per-vehicle bank applications that slow the crew rotation. Mix-and-match between brands and trims is fine, and you can stage the deliveries across a 12-month pipeline.
What is an Australian Credit Licence (ACL)?
An Australian Credit Licence (ACL) is the ASIC authorisation required to engage in regulated credit activities in Australia. Equifund operates under ACL 389328. This means we are bound by responsible lending obligations and the National Consumer Credit Protection Act when arranging finance.