Trailer finance for freight and haulage operators
Specialist trailer finance and commercial trailer loans for Australian owner‑drivers, fleets and haulage businesses, covering the trailer alone or with the prime mover. We package your BAS, bank statements and freight contracts for the lenders on our panel that suit your work. New or used, on a chattel mortgage or finance lease.
- Pre-approval typically inside 24 hours*
- $0 deposit for prime applications*
- Wide specialist lender panel
- New, used, dealer or private sale
30-second eligibility check. No impact on your credit score.
Choose your industry
Choose the category that best describes your finance requirement.
No obligation. Soft credit check only.
Built for operators, backed by specialists
Whether you are an owner-driver adding your first trailer, a fleet operator replacing worn sets, or a haulage business that has just won a new freight contract, Equifund can match you to lenders that suit the deal.
Who we help
For operators across Australian freight and haulage.
 Adding Trailer Capacity
 Pairing a Trailer With a Prime Mover
 Won a New Freight Contract
 Refinancing Trailer Loans
Why choose us
Quick pre-approvals and finance matched to how your freight is invoiced, subject to lender criteria.
Wide panel of Australian lenders, not one credit template
We move quickly so you are not left waiting
Freight contracts, invoices and BAS packaged for lenders
Support for owner‑drivers and growing fleets
Which trailers can I finance?
You can finance curtainsiders, reefers, flat tops, drop decks, tippers, low loaders, tankers and livestock crates from the major Australian makers, new or used, through specialist lenders for ABN holders, subject to their criteria.
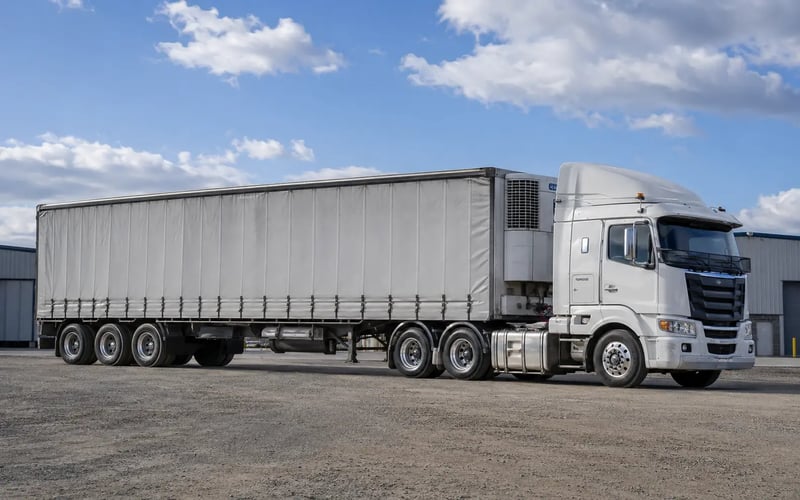
Curtainsiders
Curtainsider finance for linehaul and distribution operators moving palletised general freight.
Flat‑floor, mezzanine and drop‑deck curtainsiders, single trailers or B‑double sets, new, used or ex‑fleet.
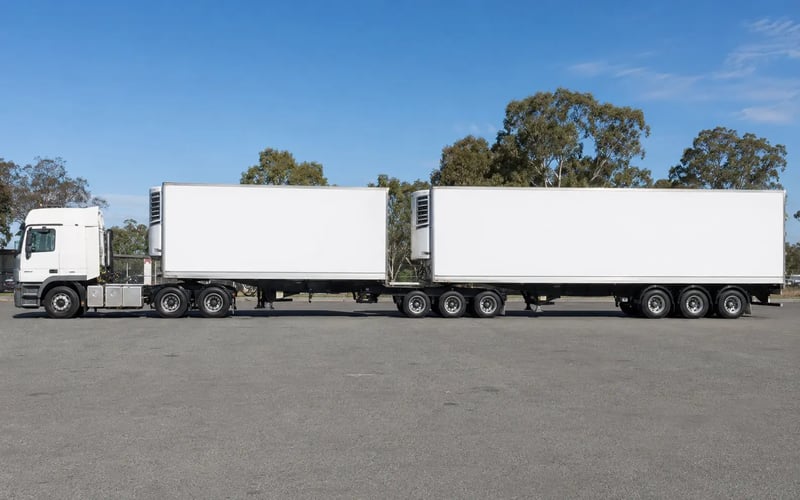
Refrigerated trailers
Refrigerated trailer finance for cold chain operators running chilled and frozen freight.
Single and multi‑temperature reefers, new or used, and the refrigeration unit can be funded with the trailer.
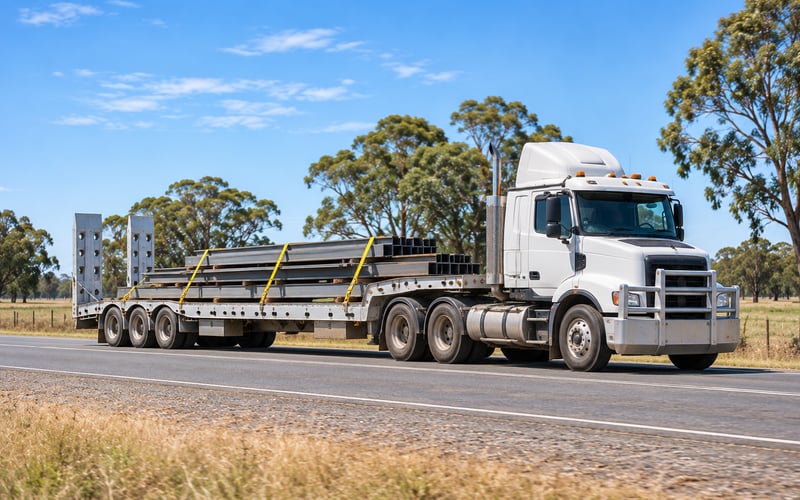
Drop decks and low loaders
Drop deck and low loader finance for operators carrying steel, building materials, plant and oversize loads.
Flat tops, drop decks, low loaders and floats, new or used, with your haulage contracts and the trailer's condition presented to lenders.
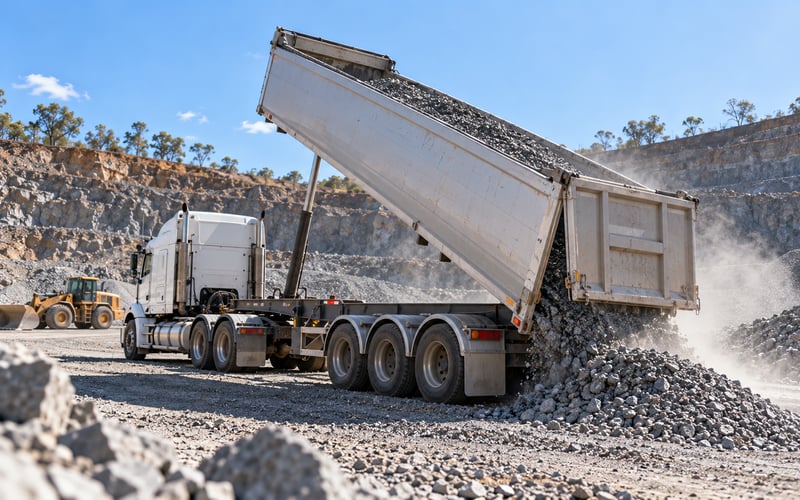
Tipper trailers
Tipper trailer finance for quarry, civil and grain haulage operators.
End tippers, side tippers and truck and dog combinations, new or used, funded alone or with the truck or prime mover that tows them.
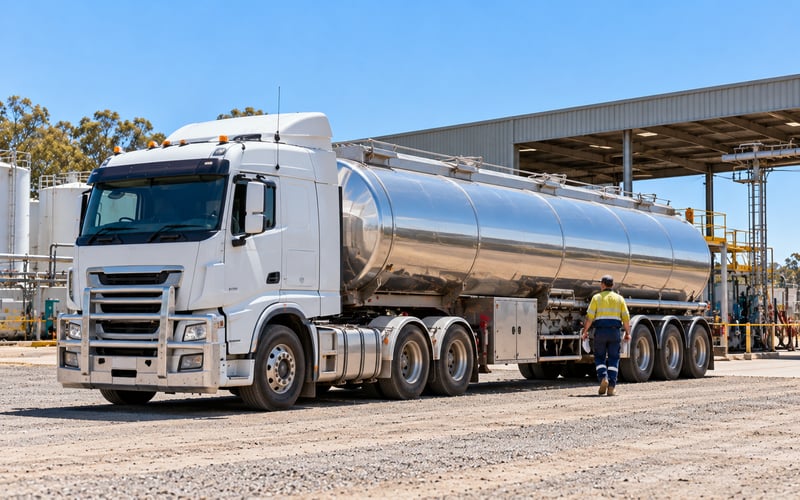
Tanker trailers
Tanker trailer finance for fuel, water, chemical and food‑grade haulage.
Stainless, aluminium and dangerous goods tankers, new or used, with the trailer's build and compliance set out for each lender.
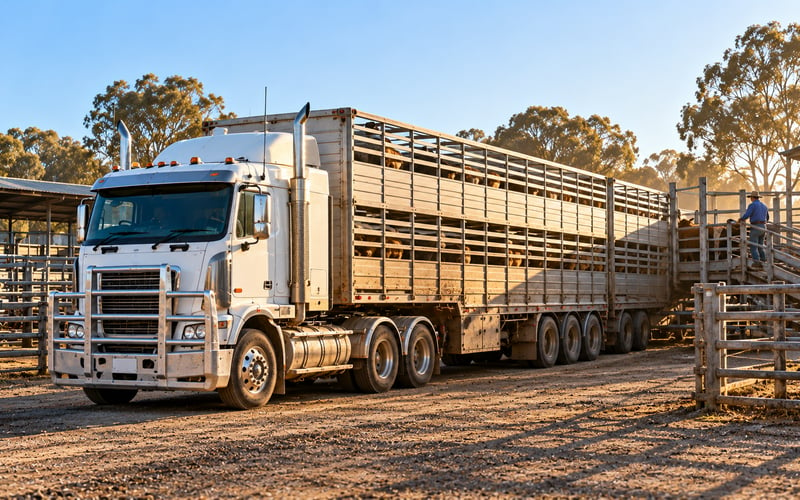
Livestock crates
Livestock trailer finance for carriers moving cattle and sheep between farms, saleyards and processors.
Single and double‑deck crates, new or used, with seasonal freight income presented to lenders.
Configurations vary by maker, including Krueger, Maxitrans, Vawdrey, Tefco, Lusty EMS and Drake. If you have a particular trailer in mind, ask us. Most makes can be funded, subject to the lender's asset criteria.
Why operators choose Equifund for trailer finance
Banks often apply a standard credit template. A specialist trailer finance broker packages your freight contracts, BAS and the trailer's value and compares lenders across a panel, not one bank's policy.
Equifund (trailer finance specialist)
Built around your deal
- Pre-approval typically inside 24 hours*
- Lenders that weigh trailer condition, not just calendar age
- $0 deposit for prime applications*
- Arranges deals that sit outside standard bank policy
- New, used, ex-fleet, private‑sale or auction
Major bank
Traditional lending
- Usually assessed against set policy criteria
- May need fuller financials or property ownership
- Specialist industry deals can fall outside policy
- Structure options can be more limited
Dealer / in‑house finance
Point of sale
- Convenient when buying from the yard
- Usually tied to that dealer's stock and brands
- Can offer less flexibility to structure the deal
- May not cover private‑sale or auction buys
Clear terms. No unnecessary complexity. Fast outcomes.
A straightforward path designed to move you from application to pre‑approval quickly.
Complete the form in 30 seconds
Tell us about your business and the trailer you are financing through our secure online form.
Speak with a trailer finance specialist
An Australian trailer finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get pre-approved over the phone
You could have an indicative pre-approval, typically inside 24 hours*, with a proposed rate, term and repayment structure. Any freight contracts you have can be included in the application.
Settle the loan and take delivery
Your specialist works through formal approval with the lender and coordinates settlement with the dealer, private seller or auction house.
Common trailer finance challenges and how we could help
Illustrative examples, not real clients. Outcomes depend on your circumstances and the lender's assessment.
What other equipment can I finance?
Equifund arranges finance across the major commercial asset classes for ABN holders, backed by a wide lender panel.


Apply for your trailer finance
Three quick steps. An Australian trailer finance specialist aims to reply the same business day.
 Business Details
 Contact Information
 Asset Information
What our clients have to say
Rated 5.0 on Google. Read what Australian clients say about working with our team. 5.0 ★ · Real Google reviews
Your trailer finance questions answered
Straight answers to the questions Australian transport operators ask most.
Who finances trailers in Australia?
Trailers in Australia are financed by major banks, dealers' in-house finance, and specialist commercial lenders accessed through a finance broker. Equifund Financial Group is an authorised credit representative (CRN 530270) under Australian Credit Licence 389328 and arranges trailer finance across a panel of specialist lenders rather than lending directly. Specialist lenders assess the trailer's condition and value alongside your ABN and BAS, and Equifund presents your freight contracts with the application. Assessing the trailer itself is how some trailers outside a bank's age policy can still get funded.
What types of trailers can I finance in Australia?
Equifund arranges finance for most commercial trailers, including curtainsiders, flat tops and drop decks, refrigerated trailers, end and side tippers, dog and tag trailers, low loaders and floats, tankers, livestock crates, skeletal and container trailers, and B‑double and road train sets. That includes the major Australian makers such as Krueger, Maxitrans, Vawdrey, Tefco, Lusty EMS and Drake. New, used, demonstrator, dealer or private sale, subject to the lender's asset criteria.
How long does trailer finance take in Australia?
Pre-approval typically comes back inside 24 hours* when your application is complete. Settlement happens once you have signed contracts and any final lender conditions are met. Specialist asset lenders can move quickly on trailer deals because they assess the trailer and your trading income directly, with the trailer itself as security rather than property.
Can I finance a used trailer, private sale or auction purchase?
Yes, used (including ex‑fleet), private sale and auction trailers can be financed through the specialist asset lenders we work with, subject to each lender's asset criteria. Some bank products have tight age limits that can rule out older trailers; many specialist lenders look at the trailer's condition, roadworthiness and value as well as calendar age.
Should I do a PPSR search before buying a used trailer privately?
Yes. The Personal Property Securities Register (PPSR) shows whether a security interest is registered against a trailer, and the PPSR treats a trailer as a motor vehicle for searching. The PPSR says that if you buy from a private seller and do not search, you are not protected, so a security interest registered against the trailer could still be enforced. You will generally be protected if you search the trailer's correct serial number (its VIN, or its chassis number if it has no VIN) on the day of the sale or the day before and the result shows no security interest, so keep the search certificate.
Can I refinance an existing trailer loan?
Yes, an existing trailer loan can often be refinanced. Refinance is common when an existing deal was settled at high rates, has an unfavourable structure (balloons, restrictive covenants) or when you want to consolidate several trailers into one facility. We compare your current setup against the specialist panel and present options. Whether refinancing suits depends on the existing loan's terms, any exit costs and lender criteria.
Which lenders does Equifund work with?
Equifund works with a wide panel of Australian lenders, including specialist asset financiers and non-bank lenders that finance trailers and transport equipment.
What is an Australian Credit Licence (ACL)?
An Australian Credit Licence (ACL) is the ASIC authorisation required to engage in regulated credit activities in Australia. Equifund Financial Group is an authorised credit representative (CRN 530270) under Australian Credit Licence 389328 and arranges finance as a broker, not a lender.
Can I finance a prime mover and trailer together?
Yes, in many cases. Truck and trailer finance can cover a prime mover and trailer in one application, whether that is a single semi-trailer, a B‑double set or a road train combination. Lenders look at whether the combined repayments fit your freight income, so a trailer added to a prime mover you already finance is usually assessed with both loans in mind. Some lenders fund the whole combination under one facility, subject to their criteria.
Can I finance multiple trailers in one application?
Yes, multiple trailers can often be financed in one application. Fleet deals, a B‑double set for a single contract, or a staged purchase across a 12-month pipeline are common. The lender panel includes options that split fleet deals across facilities or fund them under one master agreement, depending on your structure and lender criteria.
What is the difference between a chattel mortgage and a finance lease on a trailer?
The main difference is ownership: under a chattel mortgage you own the trailer and the lender holds security over it, while under a finance lease the lender owns the trailer and you make rental payments. With a chattel mortgage you claim depreciation and GST; with a finance lease GST is claimed on each payment. Many owner-drivers choose a chattel mortgage so the business owns and depreciates the trailer; some fleet operators use leases to manage repayment timing. Our trailer finance comparison guide sets the structures out side by side. Which suits you depends on your GST registration, accounting basis and current ATO rules, so confirm with your accountant.
What is freight income recognition?
Freight income recognition means showing lenders income from freight contracts, head-contractor agreements, purchase orders and ongoing route work, rather than relying only on PAYG salary. Equifund presents that income with your application. Each lender decides how much weight to give it. It matters for established operators whose income comes from contracted haulage, not a fortnightly pay slip.
What is low-doc trailer finance?
Low-doc trailer finance is asset finance assessed on a reduced document set, typically BAS, bank statements and the dealer's quote or invoice, rather than full financials and tax returns. Best suited to established operators with an active ABN, trading history and verifiable income who do not have current-year financials prepared.
What is pre-approval in trailer finance?
Pre-approval is an indicative offer before you commit to a specific trailer. It gives you a working budget, a repayment estimate and a window to find the right trailer. It is not a guarantee of finance. Final approval is subject to a full credit and verification check by the funding lender and the chosen trailer meeting its asset criteria.
Can I claim the instant asset write‑off on a trailer purchase?
Possibly, but many heavy trailers sit above the limit. The small business instant asset write-off has a per-asset limit and a turnover test set by legislation. Trailers above the limit are depreciated over time instead (for example through the small business pool). Tax treatment also depends on the structure you choose and current ATO rules, so check the ATO website and confirm your position with your accountant.
Do I need to own property to qualify?
Not necessarily. Equifund's lender panel includes options that assess the asset and your trading history rather than requiring property as security. That matters most for owner-drivers, haulage subcontractors and family transport businesses who would rather keep property out of the deal. Owning property can still help with the deposit or loan size at some lenders.
Do I need a deposit?
$0 deposit is available from some lenders for prime applications*, typically established operators with an ABN of 2 years or more, GST registration, a clean credit file and a new or late-model trailer. Other applications may need a contribution, depending on the lender.
Is a trailer over 4.5 tonnes a heavy vehicle?
Yes, in the states and territories that apply the Heavy Vehicle National Law. The National Heavy Vehicle Regulator (NHVR) says that law classes a vehicle as heavy if its gross vehicle mass or aggregate trailer mass is more than 4.5 tonnes, so most semi-trailers, dog trailers and low loaders are heavy vehicles. According to the NHVR, the law applies in the ACT, New South Wales, Queensland, South Australia, Tasmania and Victoria, but not in Western Australia or the Northern Territory. Have the trailer's VIN, build details and registration status ready with the dealer quote or private sale details, as lenders generally ask for them.
Can I finance a PBS trailer or combination?
Yes, trailers and combinations built under the Performance Based Standards (PBS) scheme can be financed, subject to lender criteria. PBS combinations need a Design Approval and a Vehicle Approval from the NHVR, which notes that a Vehicle Approval is not an authorisation to access the road network: the combination must also comply with a relevant notice or hold an access permit. Include the approval details and the access arrangements with your application, because some lenders ask to see them.
How is income from linehaul, cold chain or bulk haulage presented to lenders?
Linehaul, cold chain, container and bulk haulage income can be presented to lenders through head-contractor purchase orders, shipper contracts, freight invoices, BAS and ongoing route agreements rather than monthly PAYG. Each lender decides how much weight it gives that income, and some may offer repayment schedules that suit seasonal work such as grain or livestock haulage, subject to their criteria.
Can I finance a trailer I found for sale online?
A trailer you have found for sale online can be financed whether the listing sits with a dealer, a marketplace or a classifieds page, subject to the lender's criteria. The lender assesses the trailer itself, so the make, configuration, year, condition and the type of seller matter far more than where the advertisement appeared. Send us the listing and we will confirm what that lender needs to see.
Is there an age limit on a used trailer?
There is no single age cut-off that applies across the whole panel. Each lender sets its own limits, and many measure the trailer's age at the end of the loan term. Lenders weigh make, configuration, condition and value against your trading history, so a well-maintained trailer from a mainstream maker can be funded where a rarer trailer of the same age is not. Older trailers may mean a shorter term or a deposit.
What documents do I need to apply for trailer finance?
To apply for trailer finance you need an active ABN, recent BAS or bank statements, the trailer details including VIN, year and configuration, and the dealer invoice, quote or private sale details. If the trailer is for contracted work, we can include the freight contract or purchase order with your application. We confirm exactly what your lender match needs after a quick call.
Does checking my eligibility affect my credit score?
No. The 30-second eligibility check uses a soft enquiry. Soft enquiries are recorded on your credit file, but they are not shown to lenders and do not affect your credit score. The funding lender completes its own full credit and verification check as part of any application lodged with it.
What do lenders look for in a trailer finance application?
Lenders typically look for an ABN with at least two years of trading, transport industry experience, a clean credit history and evidence you can service the repayment. We can include a freight contract or quote for the work with your application. A shorter trading history may need a deposit, depending on the lender.
How do I finance a trailer in Australia?
Transport operators in Australia finance a trailer on a chattel mortgage or finance lease, usually through a bank, a dealer finance arm or a finance broker such as Equifund, an authorised credit representative that matches you to lenders and presents your freight contracts with the application. Lenders weigh the trailer type, age and condition alongside your ABN and BAS. An indicative pre-approval arranged through Equifund can give you a working budget before you negotiate. For a longer walk-through, read our guide on how trailer finance works.
*$0 deposit is available for prime credit applications only. Typical prime criteria include an active ABN of 2 years or more, GST registration, a clean credit file with no recent defaults or insolvency events, demonstrated trading income supported by BAS or bank statements, and a new or late-model trailer purchased through a recognised dealer. Loan-to-value, term, balloon, rate and fees vary by lender, asset type, age and applicant profile. Pre-approval is an indicative offer only and is subject to a full credit and verification check by the funding lender. The information on this page is general information only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you before acting on it.
Tax and GST treatment depends on your circumstances and current ATO rules, so confirm your position with your accountant. Instant asset write-off and depreciation rules are administered by the ATO; credit licensing is regulated by ASIC. Eligibility criteria are set by the individual lender.
*Pre-approval timeframes are indicative only and subject to lender assessment and eligibility criteria.
EF Financial Group Pty Ltd ACN 647 510 790 CRN 530270 Authorised under Australian Credit Licence Number: 389328.