Tractor Finance for Australian Farmers and Ag Contractors
Specialist tractor finance, also known as a tractor loan, for Australian farmers, graziers and ag contractors. BAS, grower contracts and seasonal income assessed directly. Utility, mid-horsepower and high-horsepower tractors, new, used, ex-fleet, dealer, private-sale or auction, funded through a chattel mortgage, finance lease or operating lease.
- Pre-approval typically inside 24 hours
- $0 deposit for prime applications
- Wide specialist lender panel
- New, used, dealer or private-sale machines
30-second check. No impact on your credit score.
Choose Your Industry
Choose the category that best describes your finance requirement.
No obligation. Soft credit check only.
Built for Operators, Backed by Specialists
Whether you are a farmer buying your first tractor, a cropper replacing ageing machines, or an ag contractor taking on new seasonal work, Equifund matches you to lenders that read seasonal income and asset value correctly.
Who We Help
Specialist finance for every corner of the Australian farming and agriculture industry.
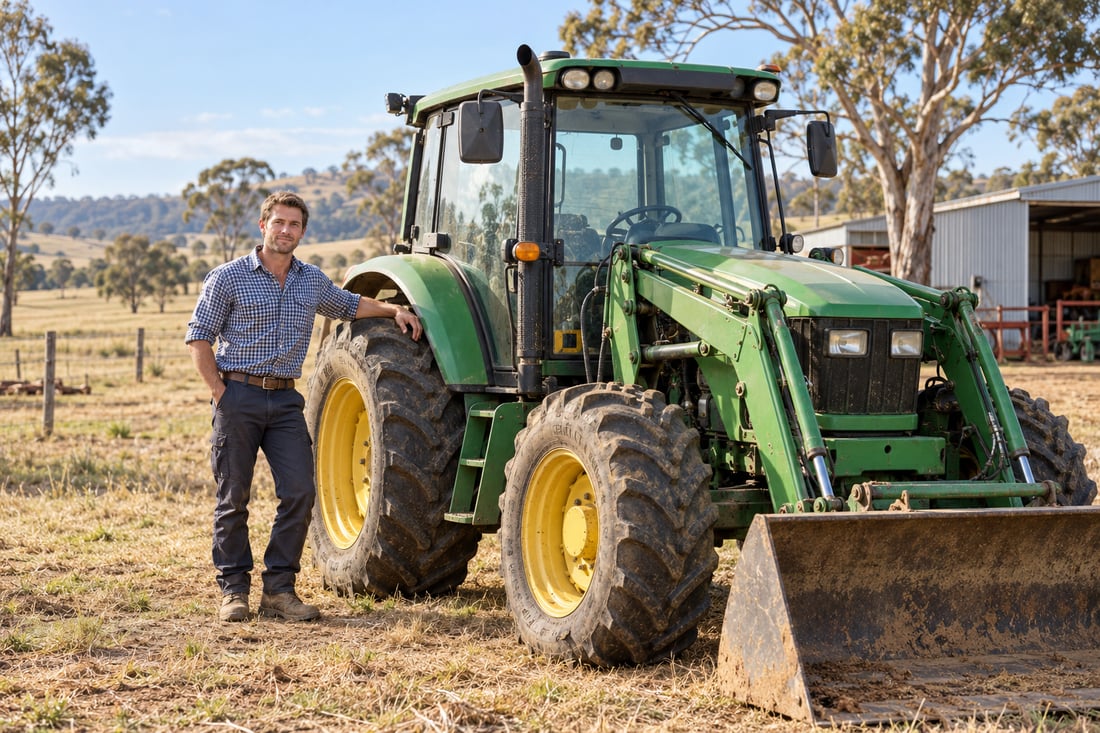 Farmers Buying Their First Tractor
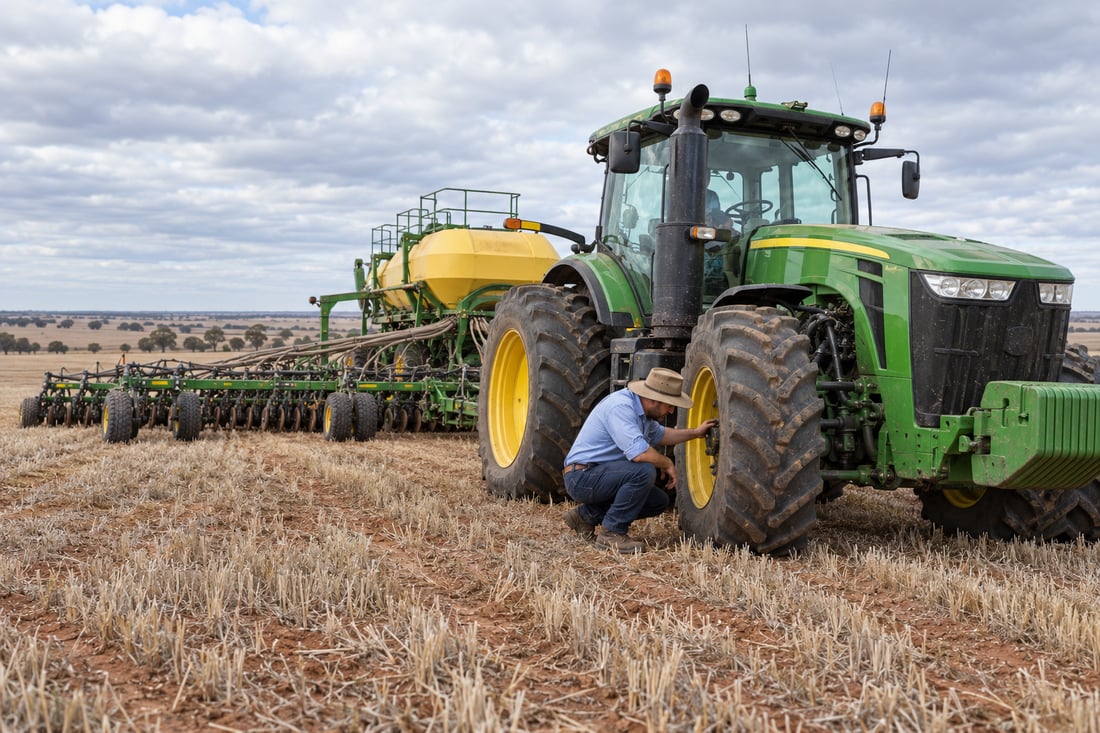 Croppers Replacing Ageing Tractors
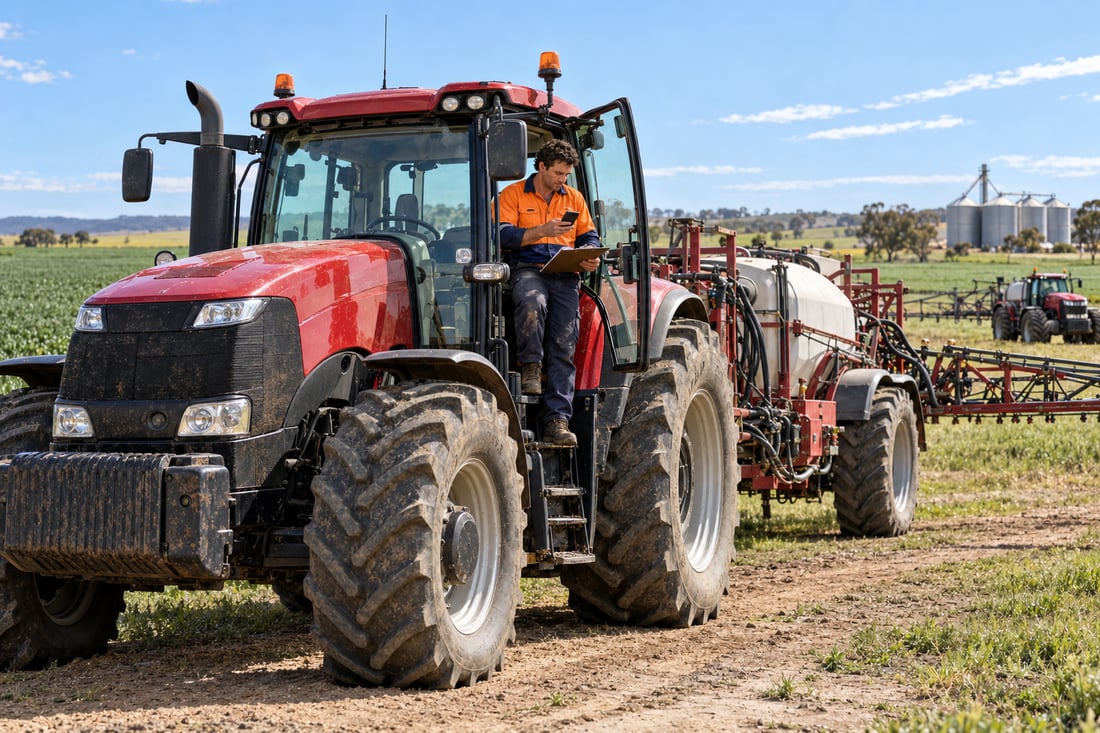 Ag Contractors Taking On New Seasonal Work
 Operators Refinancing Existing Tractor Loans
Why Choose Us
Faster pre-approvals and terms built around your season, not a city pay cycle.
Wide Panel of Australian Lenders, Not One Credit Template
We Move Quickly So You Are Not Left Waiting
Grower Contract, Seasonal and BAS Income Assessed Directly
Support for Family Farms and Ag Contractors
Why Operators Choose Equifund for Tractor Finance
A bank applies a generic credit template. Here is how a specialist tractor finance broker reads your seasonal income and asset value the way a major bank or dealer will not.
Equifund (Tractor Finance Specialist)
Built around your deal
- Pre-approval often inside 24 hours
- Reads seasonal and grower-contract income correctly
- $0 deposit on prime applications
- Funds deals outside standard bank policy
- New, used, ex-fleet, private-sale or auction
Major Bank
Traditional lending
- Generic template for property-backed borrowers
- Full financials and property security required
- Specialist industry deals can fall outside policy
- One product, limited structure flexibility
Dealer / In-house Finance
Point of sale
- Convenient when buying from the yard
- Limited to that dealer's stock and brands
- Less flexibility to structure the deal
- Not built for private-sale or auction buys
Clear Terms. No Unnecessary Complexity. Fast Outcomes.
A straightforward path designed to move you from application to pre-approval quickly.
Complete the Form in 60 Seconds
Tell us about your business and the tractor you are financing through our secure online form.
Speak With a Tractor Finance Specialist
An Australia-based tractor finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get Pre-Approved Over the Phone
You'll have a clear pre-approval, typically inside 24 hours, with rate, term and repayment structure tailored to how your contract income actually flows.
Settle the Loan and Take Delivery
Your specialist sources the strongest matched offer and coordinates settlement with the dealer, private seller or auction house.
Real Results for Real Operators
See how Australian farmers and ag contractors are getting the tractors they need, even with complex profiles.
What Other Equipment Can I Finance?
Equifund finances every major commercial asset class for prime ABN profiles, backed by a wide lender panel.
 Trucks
 Semi-Trailers & Trailers
 Refrigerated Trucks
 Excavators & Loaders
 Cranes & Site Machinery
 Trailer Trucks
 Tractors & Harvesters
 Yellow Goods
 Skid Steers & Access EquipmentTrucksSemi-Trailers & TrailersRefrigerated TrucksExcavators & LoadersCranes & Site MachineryTrailer TrucksTractors & HarvestersYellow GoodsSkid Steers & Access Equipment

Apply for Your Tractor Finance
Three quick steps. An Australia-based tractor finance specialist usually gets back to you the same business day.
 Business Details
 Contact Information
 Asset Information
What Our Clients Have to Say
Rated 5.0 on Google by Australian operators for fast pre-approvals, flexible terms and specialist service. 5.0 ★ · Real Google reviews
Have Questions?
Straight answers to the questions Australian tractor operators ask most.
Who finances tractors in Australia?
Tractors in Australia are financed by major banks, machinery dealers' in-house finance, and specialist commercial lenders accessed through a finance broker. Equifund is a licensed finance specialist, Australian Credit Licence 389328, and arranges tractor finance across a panel of specialist lenders rather than lending directly. Specialist lenders assess grower contracts, harvest income and seasonal repayment capacity, which is how repayments can be structured around the crop cycle rather than month to month.
What types of tractor can I finance in Australia?
We finance every tractor class: broadacre and row-crop tractors (John Deere, Case IH, New Holland, Massey Ferguson, Fendt), utility and compact tractors (Kubota), headers and combines, hay + forage equipment, sprayers, seeders, planters, tillage gear and grain-handling infrastructure. New, used, ex-fleet, dealer, private sale or auction.
How long does tractor finance take to settle in Australia?
Pre-approval typically comes back inside a business day. Settlement happens once you have signed contracts and any final lender conditions are met. Ag-specialist lenders read your grower contracts and harvest income directly, so they move faster than major banks on farm equipment deals.
Do I need to own farmland to qualify?
No, you do not need to own farmland to qualify. The specialist lender panel includes options that assess on the tractor asset, your grower contracts, harvest cycle income and trading history rather than requiring property as security. Matters most for share-farmers, contract harvesters and family farms that don't want to lock the farm folio.
Do I need a deposit?
$0 deposit is available for prime applications, especially established growers with active grower contracts or contract harvest agreements. New ABNs typically need contribution, but $0 deposit on the right deal is common for ongoing growers with verifiable harvest income.
Can I finance a used or ex-fleet tractor?
Yes, used and ex-fleet tractors can be financed, including dealer demo and private-sale machines. Major banks have age cut-offs; specialist lenders look at machine condition, hours and service history.
Can repayments be structured around the harvest cycle?
Yes, repayments can be structured around the harvest cycle. Seasonal repayment structures (skip-month, harvest-end lump, quarterly-to-match-receival) are standard for broadacre and hay+lucerne growers. Specialist lenders understand grower cashflow runs against GrainCorp / VicGrain receival cycles and hay-cut timing.
Can I finance multiple machines together?
Yes, multiple machines can be financed together. Multi-machine deals (tractor + header + sprayer for a full broadacre setup, or tractor + multiple hay implements for a hay contractor) are common. The lender panel includes options that fund packages under a master facility against the grower contract portfolio.
Can I refinance an existing tractor loan?
Yes, an existing tractor loan can be refinanced. Refinance is common when an existing deal was settled at high rates, has an unfavourable structure, or is consolidating multiple machines into one master facility.
Which lenders does Equifund work with?
A wide panel of Australian lenders spanning major banks, ag-specialist lenders, asset financiers and non-bank lenders that specifically understand grower-contract income, harvest cycles, seasonal cashflow and the residual value of farm equipment.
What is the difference between a chattel mortgage and a finance lease on a tractor?
Chattel mortgage: you own the tractor, claim depreciation and GST, lender holds security. Finance lease: lender owns it, you pay rental; GST claimed on each payment. Most owner-operators run chattel for depreciation. Both available.
What is grower-contract income recognition?
Grower-contract income recognition is how a specialist lender reads income from grower contracts, GrainCorp / VicGrain receival statements, hay supply agreements and contract harvest agreements rather than treating only PAYG salary as income. It matters for broadacre growers and contract harvesters whose income comes from seasonal harvest.
What is low-doc farm equipment finance?
Low-doc tractor finance is asset finance assessed on a reduced document set, typically BAS, bank statements and the grower contract, rather than full financials and tax returns. Best suited to established growers with an active ABN.
Can I claim instant asset write-off on a tractor purchase?
Tax treatment depends on the structure you choose and current ATO rules. For FY26, the small business instant asset write-off threshold is $20,000 per asset for businesses under $10M turnover. Larger tractor purchases generally fall under standard depreciation. Consult your accountant.
What is an Australian Credit Licence (ACL)?
An Australian Credit Licence (ACL) is the ASIC authorisation required to engage in regulated credit activities in Australia. Equifund operates under ACL 389328. This means we are bound by responsible lending obligations and the National Consumer Credit Protection Act when arranging finance.
Can I finance a tractor I found for sale online?
A tractor you have found for sale online can be financed whether the listing sits with a dealer, a machinery marketplace or a classifieds page. The lender assesses the machine itself, so the make, model, year, hours and the type of seller matter far more than where the advertisement appeared. Send us the listing and we will confirm what that lender needs to see.
Is there an age or hours limit on a used tractor?
There is no fixed age or hours cut-off across the panel. Lenders weigh the make, model, hours and condition against your trading history, so a well-maintained high-hour tractor from a mainstream brand is often funded where a rarer machine of the same age is not. Older machines may attract a shorter term or a deposit.
What documents do I need to apply for tractor finance?
To apply for tractor finance you need an active ABN, recent BAS or bank statements, the machine details including serial number, hours and year, and the supplier invoice or quote. Grower contracts or delivery agreements help where income is seasonal. We confirm exactly what your lender match needs after a quick call.
Depreciation and asset cost thresholds set by the ATO. Credit licensing regulated by ASIC. General information only, not personal or financial advice. Fees, terms and eligibility are set by the individual lender and vary by circumstance. Equifund Financial Group Pty Ltd, Australian Credit Licence 389328.