Business Car Financefor Australian ABN Holders
Specialist business car finance for established Australian ABN holders, from tradie utes to small-business SUVs, mobile-professional sedans and EV company cars. BAS and trading history assessed directly. Chattel mortgage, hire purchase and finance lease options, matched to how your business actually earns.
- Pre-approval inside 24 hours
- $0 deposit for prime applications
- Wide specialist lender panel
- New, used, dealer or private-sale vehicles
30-second eligibility check. No credit check unless you proceed.
Choose Your Industry
Choose the category that best describes your finance requirement.
No obligation. A credit check only happens if you choose to proceed.
Built for Business, Backed by Specialists
Whether you run a tradie ute, a client-facing SUV, or a small fleet, Equifund matches you to lenders that read business income and vehicle value correctly.
Who We Help
Specialist finance for every corner of Australian business motoring.
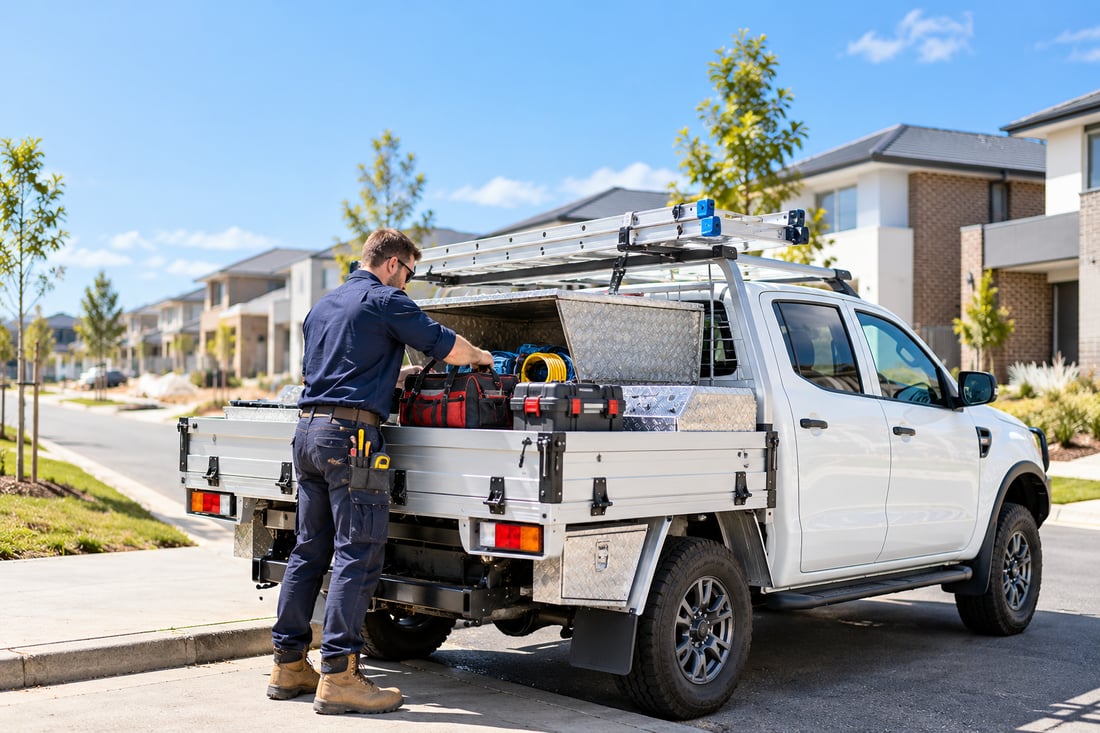 Tradies & Contractors
 Small-Business Owners
 Mobile Professionals
 Small Fleet Operators
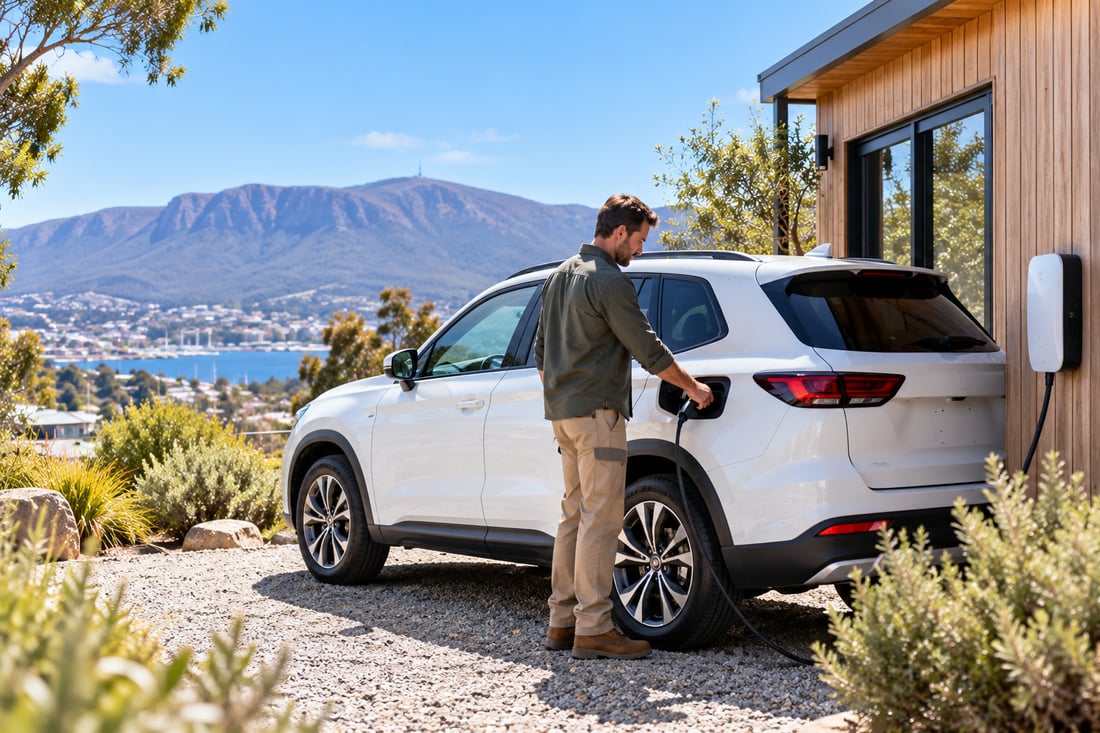 EV & Hybrid Buyers
Why Choose Us
Faster pre-approvals and terms built around your business.
Lenders Who Understand Business Vehicles
We Move Quickly So Your Vehicle Is Not the Bottleneck
Repayments Structured Around Your Cash Flow
Support for Sole Traders and Non-Standard Profiles
Which Business Car Type Can I Finance?
The main business vehicle types Australian ABN holders put to work, financed through specialist lenders for established businesses.
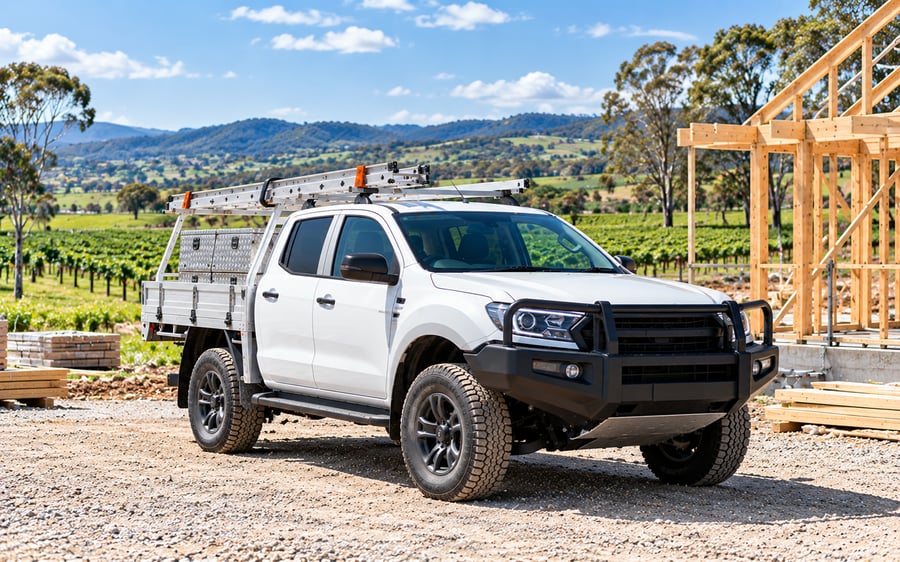
Work Utes
Finance for single-cab, extra-cab and dual-cab utes used for trades, site and rural work, new or used, from a dealer, auction or private sale.
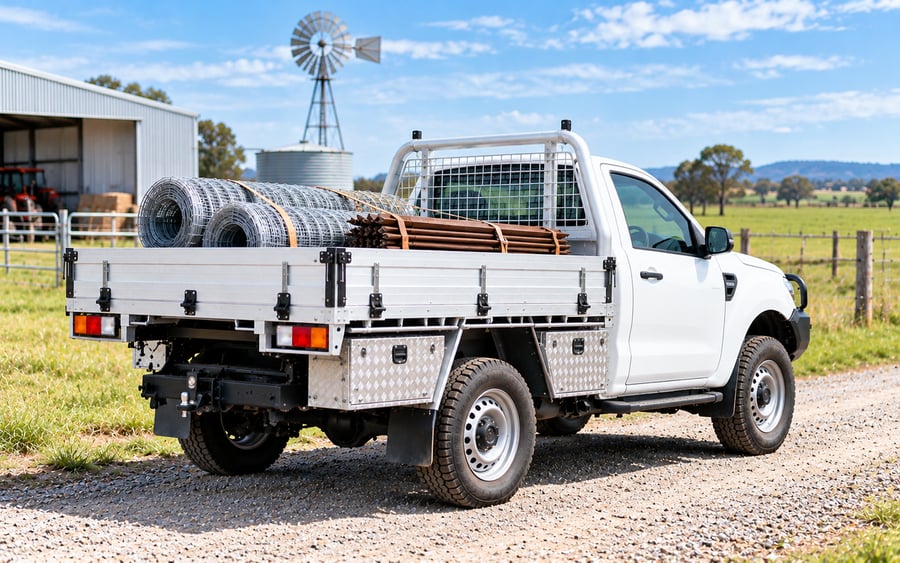
Cab-Chassis & Tray-Back Utes
Finance for cab-chassis utes with alloy or steel trays, toolboxes, canopies and racks fitted for the trade, including the cost of the fit-out on the same facility.
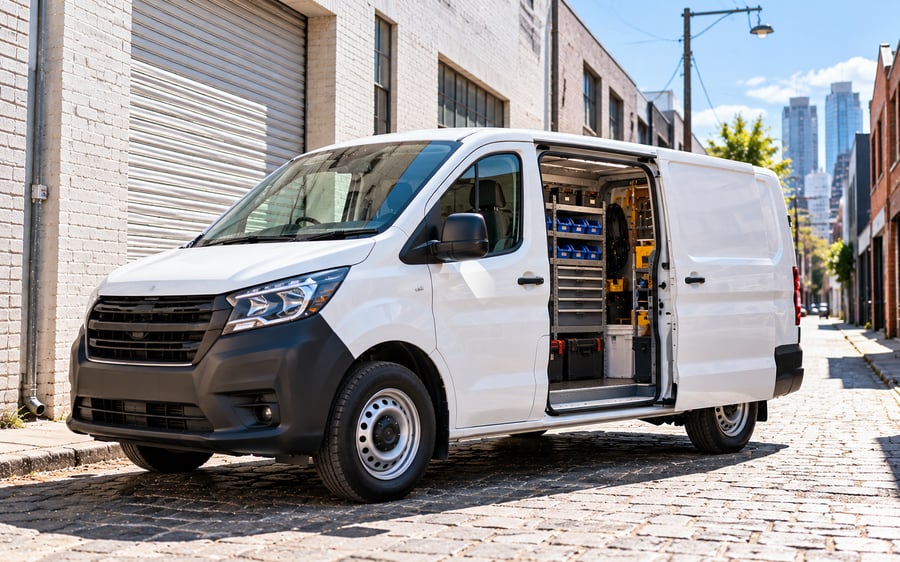
Vans
Finance for compact, mid-size and large vans with shelving and racking, used for deliveries, service calls and mobile trades across city and regional routes.
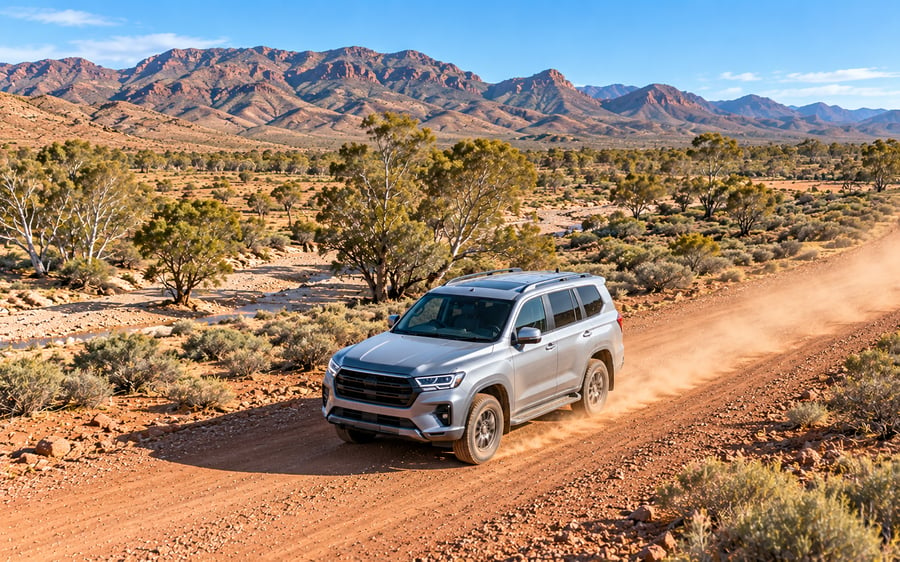
Business SUVs & 4WDs
Finance for SUVs and 4WDs used for sales territories, regional travel and site visits on rough roads, with towing capacity for trailers and equipment.
Sedans & Hatchbacks
Finance for sedans and hatchbacks used by consultants, agents, accountants and other client-facing roles, financed through the business ABN.
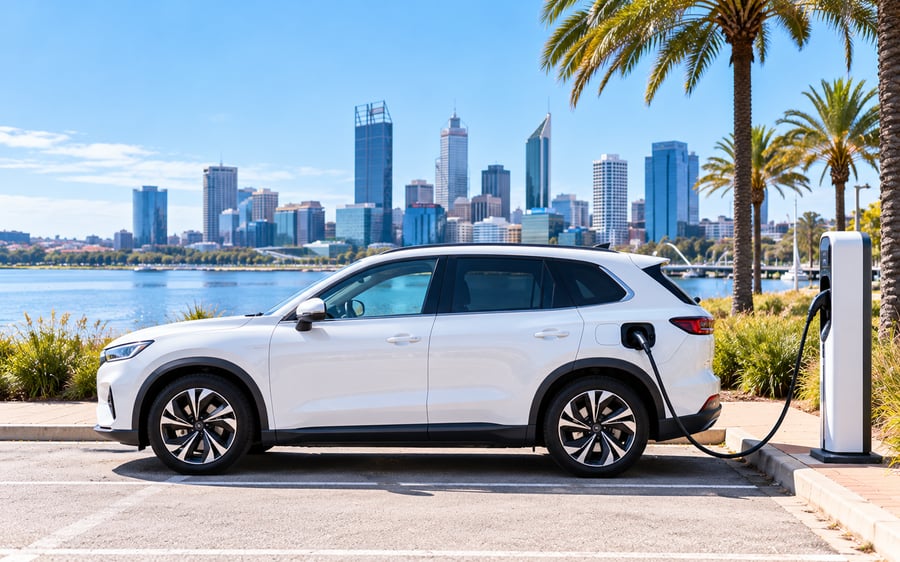
Electric & Plug-In Hybrid
Finance for battery electric and plug-in hybrid cars, SUVs and utes through your ABN, assessed on your business income and the vehicle.
Plus utes, vans, SUVs and cars from Toyota, Ford, Mazda, Mitsubishi, Isuzu, Hyundai, Kia, BYD, Tesla, Volkswagen, Nissan, Subaru and GWM. If your vehicle is not listed, ask us and we will check it against the lender panel.
Which Business Car Finance Structure Is Right for You?
Three ways to structure your finance, each suited to a different goal and cashflow position. Choosing a structure? Compare chattel mortgage, hire purchase and leases in our business vehicle finance guide.
Chattel Mortgage
You own the vehicle from the day finance settles, while your lender holds a mortgage over it as security until the loan is repaid. It is the most requested structure for GST-registered ABN holders, since you can typically claim the GST back on the purchase price straight away and depreciation runs through your own business. A balloon payment can be added to lower your regular repayments if that suits your cash flow better.
Hire Purchase
The lender owns the vehicle for the life of the agreement and you make fixed repayments to use it, with ownership transferring to you once the final payment clears. It suits business owners who want the certainty of a fixed repayment structure, and the GST is spread across your payments rather than claimed as one lump sum upfront.
Finance Lease
Your lender retains legal title to the vehicle for the term of the lease while you use it in your business, making regular lease payments that are typically fully tax deductible. At the end of the term you can make an offer to buy the asset, refinance the residual, or hand it back, giving you flexibility as your fleet needs change.
Depreciation and car cost thresholds set by the ATO. Credit licensing regulated by ASIC.
Clear Terms. No Unnecessary Complexity. Fast Outcomes.
A straightforward path designed to move you from application to pre-approval quickly.
Complete the Form in 60 Seconds
Tell us about your business and the vehicle you are financing through our secure online form.
Speak With a Business Car Finance Specialist
An Australia-based business car finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get Pre-Approved Over the Phone
You'll have a clear pre-approval often within 1 business day, with rate, term and repayment structure tailored to how your business actually earns.
Settle the Loan and Take Delivery
Your specialist sources the strongest matched offer and coordinates settlement with the dealer, private seller or auction house.
Real Results for Real Businesses
See how Australian tradies, business owners and fleet operators are getting the business cars they need, even with complex profiles.
What Other Vehicles & Equipment Can I Finance?
Equifund finances every major commercial asset class for prime ABN profiles, backed by a wide lender panel.

Apply for Your Business Car Finance
Three quick steps. An Australia-based business car finance specialist gets back to you the same business day.
 Business Details
 Contact Information
 Asset Information
What Our Clients Have to Say
Rated 5.0 on Google by Australian business owners and ABN holders for fast pre-approvals, flexible terms and specialist service. 5.0 ★ · Real Google reviews
Have Questions?
Straight answers to the questions Australian business owners and ABN holders ask most.
What types of business cars can I finance in Australia?
We finance every category of business car: dual-cab and single-cab utes (Toyota HiLux, Ford Ranger, Mazda BT-50, Mitsubishi Triton, Isuzu D-Max, VW Amarok), 4WDs (Toyota Prado, LandCruiser 79 / 200 / 300, Ford Everest, Pajero Sport, Patrol), mid-size SUVs (Toyota RAV4, Mazda CX-5, Hyundai Tucson, Kia Sportage, Mitsubishi Outlander), large SUVs (Toyota Kluger, Hyundai Santa Fe, Kia Sorento, Mazda CX-9 / CX-90), sedans (Toyota Camry, Mazda 3 / 6, Hyundai i30, Kia Cerato), vans (Toyota HiAce, Ford Transit, Hyundai Staria-Load), 8-seat people-movers (Kia Carnival, Hyundai Staria), EVs (Tesla, IONIQ 5 / 6, EV6 / EV9, BYD Atto / Seal, Polestar) and PHEV / hybrid (RAV4 Hybrid, Outlander PHEV, CX-60 PHEV). New, used, demonstrator, dealer, private sale or fleet-auction purchases all financeable.
Is this consumer car finance or business car finance?
Business car finance, strictly. Equifund arranges asset finance for ABN holders against their business: chattel mortgage, hire purchase, finance lease and operating lease. This is not a consumer car loan. The lender assesses your business income, BAS, trading history and the vehicle as the security asset, not your personal pay slip. You claim depreciation and GST on the vehicle, and the structure suits sole traders, partnerships, company directors and small-business fleet operators.
Do I need to own property to qualify?
No. Equifund's specialist lender panel includes options that assess on the asset, your business income and trading history rather than requiring property as security. This matters for owner-operator tradies, sole-trader mobile professionals, real estate agents on commission and small-business fleet operators who don't want to lock the property folio for a sub-$100k vehicle.
Do I need a deposit?
$0 deposit is available for prime applications, especially established ABN holders with active trading history and verifiable business income. New ABNs typically need some contribution, while established operators with a prime application can often access $0 deposit. We can also structure trade-in equity from your existing business car as deposit on the next one.
I'm a tradie buying a Ranger or HiLux for my work ute. How does that work?
Standard business-car finance via chattel mortgage. Your ABN, BAS and trading history are the application basis, not your PAYG pay slip. The ute is the asset and the security. You claim depreciation and GST upfront on the vehicle, and the instant asset write-off (where applicable based on the financial year and your aggregated turnover) can apply to the eligible portion. The Ford Ranger XLT / Sport / Wildtrak, Toyota HiLux SR5 / Rogue, Mazda BT-50 GT and Mitsubishi Triton GLS are the four most-financed work utes through Equifund.
What's the difference between chattel mortgage, hire purchase and finance lease for a business car?
Three structures, each with different tax treatment. Chattel mortgage: you own the vehicle, claim depreciation and GST upfront, lender holds security over the asset. Best for sole traders and small companies that want the vehicle on the balance sheet. Hire purchase: the lender owns the vehicle until the final payment, then ownership transfers to you, with GST spread across the repayments. Best for businesses that want fixed repayments and eventual ownership. Finance lease: lender owns the vehicle, you make rental payments and claim GST on each payment. Best for companies that prefer the vehicle off the balance sheet. We arrange all three across the specialist panel.
Can I finance an electric or plug-in hybrid car through my ABN?
Yes. Electric and plug-in hybrid cars, SUVs and utes can be financed through your ABN with a chattel mortgage, hire purchase or finance lease, assessed on your business income and the vehicle. We finance Tesla, Hyundai IONIQ 5 / 6, Kia EV6 / EV9, BYD, Polestar, Mitsubishi Outlander PHEV and Mazda CX-60 PHEV across the specialist panel. Tax treatment varies by business, so confirm it with your accountant.
What is low-doc business car finance?
Low-doc business car finance is asset finance pre-approved on a reduced document set, typically BAS, bank statements and the dealer invoice or quote, rather than full financials and tax returns. Best suited to established ABN holders with an active business, trading history and verifiable income who don't have current-year financials prepared. Common for sole-trader tradies, sales reps on commission and self-employed mobile professionals.
How long does Australia business car finance take to settle?
Pre-approval typically comes back inside a business day when your application is complete. Settlement happens once you have signed contracts, the dealer has confirmed delivery and any final lender conditions are met. Specialist asset lenders move faster than major banks on business-car deals because they assess the vehicle and business income directly rather than waiting on consumer-loan underwriting cycles.
Can I finance a used business car, ex-fleet, private sale or auction purchase?
Yes. Used (including ex-lease / ex-fleet, end-of-cycle dealer demonstrators and high-spec second-hand), private sale and dealer-auction purchases are all financeable through the specialist asset lenders we work with. Major banks typically have age cut-offs that knock out older vehicles; specialist lenders look at the asset condition, kilometres and service history rather than calendar age alone.
Can I refinance an existing business car loan?
Yes. Refinance is common when an existing deal was settled at high rates, has an unfavourable structure (large balloon, restrictive covenants), or is consolidating multiple vehicles into one master facility. We compare your current setup against the specialist panel and present options.
Which lenders does Equifund work with?
A wide panel of Australian lenders spanning major banks, specialist asset financiers and non-bank lenders that specifically understand small-business income, BAS, fleet trading patterns and the residual value of business cars across utes, 4WDs, SUVs, sedans, vans and EVs.
Can I finance multiple business cars in one application?
Yes. Fleet deals (two to twenty vehicles for a business, staged purchases across a 12-month replacement pipeline, or annual rotation cycles for hire / rideshare fleets) are common. The lender panel includes options that split fleet deals across facilities or fund them under one master agreement. For larger fleets we can also bundle insurance and fuel-card programs.
I run a small tradie crew (2 to 5 utes). Can you fund the whole crew on one application?
Yes. Multi-ute tradie crew fleets (typically 2 to 5 Rangers, HiLuxes, BT-50s or Tritons) are the most common business-vehicle deal we arrange. Specialist lenders fund the whole crew on one master facility against the BAS and head-contractor framework rather than per-vehicle bank applications that slow the crew rotation. Mix-and-match between brands and trims is fine, and you can stage the deliveries across a 12-month pipeline.
What is an Australian Credit Licence (ACL)?
An Australian Credit Licence (ACL) is the ASIC authorisation required to engage in regulated credit activities in Australia. Equifund (EF Financial Group Pty Ltd) is an authorised credit representative (CRN 530270) under Australian Credit Licence 389328. This means we are bound by responsible lending obligations and the National Consumer Credit Protection Act when arranging finance.
$0 deposit is available for prime credit applications only. Typical prime criteria include an active ABN of 2 years or more, GST registration, a clean credit file with no recent defaults or insolvency events, demonstrated trading income supported by BAS or bank statements, and a new or late-model vehicle purchased through a recognised dealer. Loan-to-value, term, balloon, rate and fees vary by lender, vehicle type, age and applicant profile. Pre-approval is an indicative offer only and is subject to a full credit and verification check by the funding lender. The information on this page is general information only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you before acting on it. EF Financial Group Pty Ltd ACN 647 510 790 CRN 530270 Authorised under Australian Credit Licence Number: 389328.