Apply for Trailer Finance Pre-Approval
Adding a trailer for a new freight contract? Tell us the trailer and the run, and we will match you to the structure and lenders that suit your freight income.
A trailer only earns when it is hooked up and loaded, so its repayments need to match the freight it wins. Compare chattel mortgage, hire purchase and leases on GST, tax and repayments, then apply once.
Side by side for curtainsiders, tippers, reefers and low loaders, so you can weigh owning against leasing. Buying a specific trailer? Start with our trailer finance page.
Swipe to compare all four
| Feature | Chattel mortgageWidely used | Hire purchase | Finance lease | Operating lease |
|---|---|---|---|---|
| Best for | GST-registered transport operators | Owner-drivers wanting ownership | Lower repayments with a residual at term end | Fleets wanting a fixed refresh cycle |
| Deposit | $0 for prime applications | $0 for prime applications | $0 for prime applications | Set by the lessor |
| Term | 1-7 years | 1-7 years | 2-5 years | 2-5 years |
| GST | Claim upfront if GST‑registered | Claim upfront if GST‑registered | On each payment | On each payment |
| Own at end | Yes | On the final payment | Buy for the residual if the lender agrees | Return the trailer |
| Balloon | Optional, set by lender | Optional, set by lender | Residual agreed at the start | None |
| Documents | Financials or BAS | Financials or BAS | Financials or BAS | Financials or BAS |
Illustrative example: a $110,000 tri-axle curtainsider over 5 years, structured three ways.
Indicative only. Repayments calculated at 8.5% p.a. over 60 months, payments in arrears, 29 October 2026. Not a quote or offer. Excludes fees and tax effects; tax outcomes are general information only, confirm with your accountant.
Each run puts different demands on a trailer, so lenders look at the work behind it. Select your freight task to see the trailers operators on that run usually finance.
How each trailer type is usually financed, from refrigerated sets to low loaders.
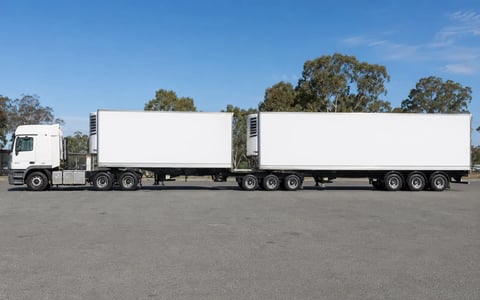
Reefer trailers and B‑double sets for chilled and frozen freight, new or used.
Flat tops, drop decks and extendables for general freight, steel and machinery loads.
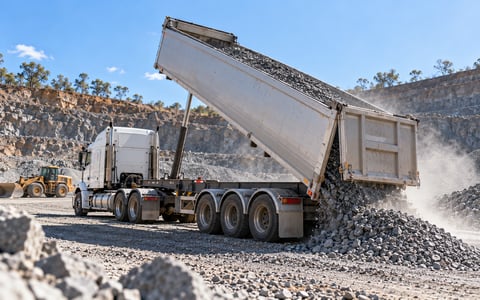
End tippers, side tippers and truck‑and‑dog sets for quarry, civil and grain haulage.
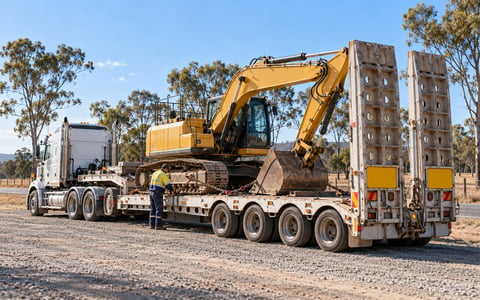
Low loaders and floats for moving plant and machinery, usually through specialist lenders.
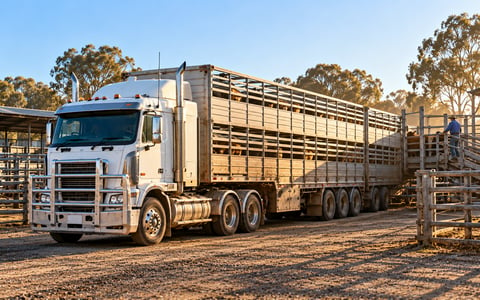
Single and double-deck crates for cattle, sheep and mixed livestock cartage.
Banks, dealer and manufacturer finance, specialist transport lenders and finance brokers all offer them.
EF Financial Group Pty Ltd ACN 647 510 790 CRN 530270 Authorised under Australian Credit Licence Number: 389328.

Adding a trailer for a new freight contract? Tell us the trailer and the run, and we will match you to the structure and lenders that suit your freight income.


Straight answers on chattel mortgage, hire purchase and leasing for trailers.
For most GST-registered Australian transport operators, a chattel mortgage is the most suitable trailer finance option. You own the trailer from day one, can claim the GST in the purchase price as a credit upfront, and can use a balloon to lower monthly repayments over terms of 1 to 7 years. Fleets that replace trailers on a fixed cycle often use an operating lease instead. General information only; confirm the right structure with your accountant.
Asset finance lenders fund most commercial trailers, including curtainsiders, flat tops and drop decks, refrigerated trailers, tipper and side tipper trailers, low loaders and floats, tankers, livestock crates, skeletal and container trailers, dog and tag trailers, and B‑double and road train sets. New and used trailers can be financed, including private sales, subject to valuation and lender assessment.
The difference between a chattel mortgage and a finance lease for a trailer is ownership. Under a chattel mortgage you own the trailer from day one, the lender registers its security interest on the PPSR until the loan is repaid, and a GST-registered business can claim the GST upfront. Under a finance lease the lender owns the trailer, you make lease payments with GST on each payment, and at the end the residual is payable: you can pay it and buy the trailer if the lender agrees, refinance it, or return the trailer and settle any shortfall. Confirm the tax treatment with your accountant.
Used trailers can be financed in Australia, including private sales (see trailer finance). Many banks limit how old a trailer can be at the end of the loan term, while specialist asset finance lenders consider older trailers case by case, based on your profile and the trailer's condition, roadworthiness and valuation. Older trailers may need a deposit. Subject to lender assessment.
Lenders can finance a trailer on its own or together with a prime mover, often in a single application. Lenders look at whether the combined repayments fit your freight income, so a trailer added to a prime mover you already finance is assessed against both loans. Some operators use a balloon on the trailer to keep the total monthly cost workable. Subject to lender assessment.
Trailer finance lenders usually ask for four things: your ABN, how long it has been active and whether the business is registered for GST; the trailer details from a dealer quote, invoice or private sale, with the make, year and VIN; recent BAS or business bank statements, with full-doc applications also asking for financials and tax returns; and any current loans or leases, including on your prime mover, so new repayments can be planned around them. Subject to lender assessment.
Equifund takes one application and matches it to the lenders on its panel that suit your profile, including banks, second-tier lenders and specialist transport and asset finance lenders. Matching looks at your credit, trading history, the freight contract or subcontract the trailer will work on, the trailer's type, age and condition, your deposit and GST status, so you only apply once. Pre‑approval is obligation-free, and fees, rates and terms are set by the lender and confirmed in writing before you sign.
GST-registered businesses can generally claim the full GST in a trailer's purchase price as a credit upfront: for a chattel mortgage in the BAS for the period of purchase, and for a hire purchase agreement entered into from 1 July 2012 in the period of the first payment or tax invoice, according to the ATO. On a $110,000 GST-inclusive trailer, that is $10,000 of GST. Under a lease, GST is included in each payment and claimed as you pay. General information only; confirm with your accountant.
The car cost limit does not apply to commercial trailers, because a trailer is not a car for tax purposes (a car is a motor vehicle designed to carry a load under 1 tonne and fewer than 9 passengers). The limit, $69,883 for 2026-27 according to the ATO, applies to passenger vehicles, so the full cost of the trailer (GST-exclusive if you claim the GST credit) can be depreciated. General information only; confirm with your accountant.
Trailers are deducted as they decline in value over their effective life, which the Commissioner sets in the Income Tax Assessment (Effective Life of Depreciating Assets) Determination 2025, or which you can self-assess. Eligible small businesses with aggregated turnover under $10 million can instead use the simplified depreciation pool, deducting 15% in the first year and 30% of the pool balance each year after, according to the ATO. Under a lease, the lender claims depreciation instead. Confirm with your accountant.
Eligible small businesses with aggregated turnover under $10 million can immediately deduct assets costing less than the instant asset write-off threshold, which is $20,000 and permanent from 1 July 2026, according to the ATO. Smaller box, plant and tradesman trailers may fall under it, while most heavy trailers cost more and go into the simplified depreciation pool instead. General information only; confirm with your accountant.
For a GST-registered owner-driver with an established trading history, a chattel mortgage is usually the most suitable option: you own the trailer, can claim the GST upfront, and the interest and depreciation are generally deductible for business use. As a sole trader you sign the finance personally, so lenders assess your personal credit file and your individual tax returns alongside the business BAS. Owner-drivers who are not registered for GST can still use a chattel mortgage or hire purchase. General information only; confirm with your accountant.
Trailer finance repayments depend on the amount, term, rate and balloon. As an illustration, on a $110,000 tri-axle curtainsider at 8.5% p.a. over 5 years, a chattel mortgage with no balloon is about $2,260 a month, and a 30% ($33,000) balloon brings it to about $1,815 a month, with the balloon owing at the end. Compare the total cost, including fees, not just the monthly figure. Indicative only, not a quote or offer.
Lenders set trailer finance rates from their own cost of funds, which moves with the RBA cash rate, plus a margin, then adjust for your credit file, time trading, deposit, loan amount, the trailer's age and type, and the structure. A late-model curtainsider from a dealer usually prices sharper than an older tipper bought privately. Published chattel mortgage rates in Australia start from around 7.5% p.a. and can reach 20% p.a. or higher for some borrowers, depending on the credit profile and the asset (money.com.au, October 2026). Business finance often has no comparison rate, so compare the total cost in dollars, including fees. Indicative only, not a quote, offer or rate guarantee.
A balloon on trailer finance is a lump sum due at the end of the loan term, a percentage of the price set by the lender based on the term and the trailer's age, that lowers your monthly repayments, as in the repayment example above. Trailers often stay in service well beyond a 5 year term, so many operators refinance the balloon or pay it out and keep running the trailer. Indicative only, subject to lender assessment.
No-deposit trailer finance may be available for prime applications, subject to lender assessment. Lenders may ask for a deposit if your credit file is impaired, your ABN is newer or the trailer is older or bought privately. A deposit can also widen the lender pool and improve the rate offered.
Trailer finance pre‑approval is typically issued within 24 hours* once your BAS or bank statements and the trailer details, such as the dealer quote or the make, year and VIN, are provided, subject to lender assessment. Settlement timing then depends on the lender, the seller and your documents.
Whether to finance or hire a trailer depends mainly on how steady the work behind it is. Hire suits short contracts, seasonal peaks or specialist trailers you need only now and then, because you pay only while you use it and the hire company usually handles major servicing. Finance suits trailers that are loaded most weeks of the year: repayments are usually fixed, a chattel mortgage or hire purchase builds equity in a trailer you can later sell or trade in, and a GST-registered business can generally claim the GST upfront under a chattel mortgage. To decide, compare a year of hire costs with a year of repayments plus running costs. General information only; confirm with your accountant.
Trailer refinance lets established operators borrow against trailers they already own outright. The lender advances an agreed amount based on the trailer's valuation and you repay it over an agreed term. It is often used to fund a deposit on a new prime mover or to take on a new freight contract. Subject to valuation and lender assessment.
$0 deposit is available for prime credit applications only.
Typical prime criteria include an active ABN of 2 years or more, GST registration, a clean credit file with no recent defaults or insolvency events, demonstrated trading income supported by BAS or bank statements, and a new or late-model trailer purchased through a recognised dealer. Loan-to-value, term, balloon, rate and fees vary by lender, asset type, age and applicant profile. Pre‑approval is an indicative offer only and is subject to a full credit and verification check by the funding lender. The information on this page is general information only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you before acting on it.
*Pre‑approval timeframes are indicative only and subject to lender assessment and eligibility criteria.
Sources: ATO, GST hire purchase and leasing; ATO, small business pool; Effective Life Determination 2025; ATO, car cost limits; ATO, $20,000 instant asset write-off; money.com.au, chattel mortgage rates, October 2026. ATO figures last checked 2 November 2026.