Apply for Equipment Finance Pre-Approval
Just won a contract and need the machine on site? Tell us the machine and the job, and we will match you to the structure and lenders that suit how the work pays.
Progress claims can take weeks to land, but machine repayments start on a fixed schedule. The right structure can bring your GST claim forward and set repayments, or a balloon, around how your contracts pay. Compare all four, then apply once.
Side by side for excavators, loaders, dozers and cranes, so you can weigh owning against leasing. Buying a specific machine? Start with our construction equipment finance page.
Swipe to compare all four
| Feature | Chattel mortgageWidely used | Hire purchase | Finance lease | Operating lease |
|---|---|---|---|---|
| Best for | GST-registered construction businesses | Owner-operators wanting ownership | Lower repayments with a residual at term end | Fleets wanting a fixed refresh cycle |
| Deposit | $0 for prime applications | $0 for prime applications | $0 for prime applications | Set by the lessor |
| Term | 1-7 years | 1-7 years | 2-5 years | 2-5 years |
| GST | Claim upfront if GST‑registered | Claim upfront if GST‑registered | On each payment | On each payment |
| Own at end | Yes | On the final payment | Buy for the residual if the lender agrees | Return the machine |
| Balloon | Optional, set by lender | Optional, set by lender | Residual agreed at the start | None |
| Servicing | Your responsibility | Your responsibility | Your responsibility | May be bundled, set by lessor |
An illustrative example on a $150,000 excavator over 5 years, with three ways to structure it.
Indicative only. Repayments calculated at 8.5% p.a. over 60 months, payments in arrears, 29 October 2026. Not a quote or offer. Excludes fees and tax effects; tax outcomes are general information only, confirm with your accountant.
Each trade runs different machines and gets paid differently, so lenders assess them differently. Select your industry to highlight the machines it usually finances.
How each machine type is usually financed, from excavators to cranes.
Mini, midi and full-size excavators, new or used, for site prep, civil and demolition work.
Skid steers, compact track loaders and wheel loaders for site work and material handling.
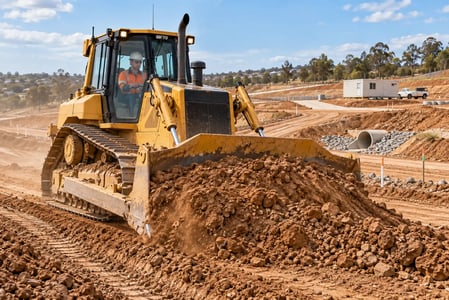
Bulldozers for bulk earthworks, clearing and mining support, often with higher loan amounts.
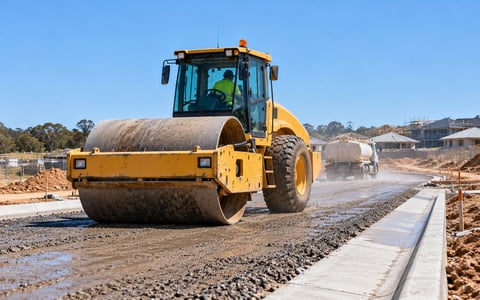
Rollers and compaction equipment for road, pavement and civil contracts.
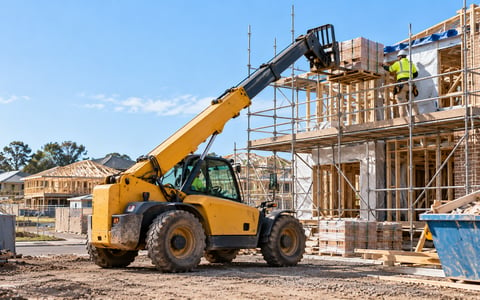
Telehandlers for lifting and placing materials on building, civil and mining sites.
Banks, dealer and manufacturer finance, specialist equipment lenders and finance brokers all offer them.
EF Financial Group Pty Ltd ACN 647 510 790 CRN 530270 Authorised under Australian Credit Licence Number: 389328.

Just won a contract and need the machine on site? Tell us the machine and the job, and we will match you to the structure and lenders that suit how the work pays.


Straight answers on chattel mortgage, hire purchase and leasing for construction equipment.
For most GST-registered Australian construction businesses, a chattel mortgage is the most suitable construction equipment finance option. You own the machine from day one, can claim the GST in the purchase price as a credit upfront, and can use a balloon to lower monthly repayments over terms of 1 to 7 years. Civil contractors refreshing a fleet every few years often use an operating lease instead. General information only; confirm the right structure with your accountant.
Asset finance lenders fund most construction and earthmoving equipment, including excavators, skid steers, wheel loaders, bulldozers, graders, backhoes, telehandlers, dump trucks, cranes, rollers, pavers, concrete equipment, crushers and screeners. New and used machines can be financed; older or specialist machines are assessed case by case by specialist lenders, subject to valuation and lender assessment.
The difference between a chattel mortgage and a finance lease for an excavator is ownership. Under a chattel mortgage you own the excavator from day one, the lender registers its security interest on the PPSR until the loan is repaid, and a GST-registered business can claim the GST upfront. Under a finance lease the lender owns the excavator, you make lease payments with GST on each payment, and at the end the residual is payable: you can pay it and buy the machine if the lender agrees, refinance it, or return the machine and settle any shortfall. Confirm the tax treatment with your accountant.
Used construction equipment can be financed in Australia, including private sales (see used equipment finance). Many banks limit how old a machine can be at the end of the loan term, while specialist asset finance lenders consider older machines case by case, based on your profile and the machine's condition, hours and valuation. A pre-purchase inspection or a deposit may be required. Subject to lender assessment.
Whether to finance or hire construction equipment depends mainly on how often the machine works. Hire, including dry hire, suits short jobs, irregular use or specialist machines you need only now and then, because you pay only while you use it and the hire company usually handles major servicing. Finance suits machines that work on your sites most of the year: repayments are usually fixed, a chattel mortgage or hire purchase builds equity in a machine you can later sell or trade in, and a GST-registered business can generally claim the GST upfront under a chattel mortgage. To decide, compare a year of hire costs with a year of repayments plus running costs. General information only; confirm with your accountant.
Some banks finance mainstream construction machines but are more cautious with specialist equipment such as tower cranes, crushers and screeners, which have narrower resale markets. Specialist asset finance lenders do finance these machines, usually with pricing that reflects the narrower resale market. Subject to lender assessment.
Construction equipment finance lenders usually ask for four things: your ABN, how long it has been active and whether the business is registered for GST; the machine details from a dealer quote, invoice or private sale, with the make, model, year and hours; recent BAS or business bank statements, with full-doc applications also asking for financials and tax returns; and any current loans or leases, so new repayments can be planned around them. Subject to lender assessment.
Equifund takes one application and matches it to the lenders on its panel that suit your profile, including banks, second-tier lenders and specialist equipment finance lenders. Matching looks at your credit, trading history, the machine's type, age and condition, your deposit and GST status, so you only apply once. Pre‑approval is obligation-free, and fees, rates and terms are set by the lender and confirmed in writing before you sign.
GST-registered businesses can generally claim the full GST in the machine's purchase price as a credit upfront: for a chattel mortgage in the BAS for the period of purchase, and for a hire purchase agreement entered into from 1 July 2012 in the period of the first payment or tax invoice, according to the ATO. On a $150,000 GST-inclusive excavator, that is $13,636 of GST. Under a lease, GST is included in each payment and claimed as you pay. General information only; confirm with your accountant.
No, the car cost limit does not apply to construction equipment such as excavators, loaders, dozers and cranes, because they are not cars for tax purposes (a car is designed to carry a load under 1 tonne and fewer than 9 passengers). The limit, $69,883 for 2026-27 according to the ATO, applies to passenger vehicles, so the full cost of the machine (GST-exclusive if you claim the GST credit) can be depreciated. General information only; confirm with your accountant.
Construction equipment is deducted as it declines in value over its effective life, which the Commissioner sets in the Income Tax Assessment (Effective Life of Depreciating Assets) Determination 2025, or which you can self-assess. Eligible small businesses with aggregated turnover under $10 million can instead use the simplified depreciation pool, deducting 15% in the first year and 30% of the pool balance each year after, according to the ATO. Under a lease, the lender claims depreciation instead. Confirm with your accountant.
Eligible small businesses with aggregated turnover under $10 million can immediately deduct assets costing less than the instant asset write-off threshold, which is $20,000 and permanent from 1 July 2026, according to the ATO. Most construction machines cost more, so they go into the simplified depreciation pool instead. General information only; confirm with your accountant.
For a GST-registered sole trader with an established trading history, a chattel mortgage is usually the most suitable option: you own the machine, can claim the GST upfront, and the interest and depreciation are generally deductible for business use. As a sole trader you sign the finance personally, so lenders assess your personal credit file and your individual tax returns alongside the business BAS. Sole traders who are not registered for GST can still use a chattel mortgage or hire purchase. General information only; confirm with your accountant.
Construction equipment finance repayments depend on the amount, term, rate and balloon. As an illustration, on a $150,000 excavator at 8.5% p.a. over 5 years, a chattel mortgage with no balloon is about $3,080 a month, and a 30% ($45,000) balloon brings it to about $2,470 a month, with the balloon owing at the end. Compare the total cost, including fees, not just the monthly figure. Indicative only, not a quote or offer.
Lenders set equipment finance rates from their own cost of funds, which moves with the RBA cash rate, plus a margin, then adjust for your credit file, time trading, deposit, loan amount, the machine's age and type, and the structure. Published chattel mortgage rates in Australia start from around 7.5% p.a. and can reach 20% p.a. or higher for some borrowers, depending on the credit profile and the asset (money.com.au, October 2026). Business finance often has no comparison rate, so compare the total cost in dollars, including fees. Indicative only, not a quote, offer or rate guarantee.
A balloon is a lump sum due at the end of the loan term, a percentage of the price set by the lender based on the term and the machine's age, that lowers your monthly repayments, as in the repayment example above. At the end you pay it out, refinance it or trade the machine in. Indicative only, subject to lender assessment.
No-deposit construction equipment finance may be available for prime applications, subject to lender assessment. Lenders may ask for a deposit if your credit file is impaired, your ABN is newer or the machine is older or bought privately. A deposit can also widen the lender pool and improve the rate offered.
Construction equipment finance pre‑approval is typically issued within 24 hours* once your BAS or bank statements and the machine details are provided, subject to lender assessment. Settlement timing then depends on the lender, the seller and your documents.
Equipment refinance lets established operators borrow against machines they already own outright. The lender advances an agreed amount based on the machine's valuation and you repay it over an agreed term. It is often used to fund new contracts or site mobilisation. Subject to valuation and lender assessment.
$0 deposit is available for prime credit applications only.
Typical prime criteria include an active ABN of 2 years or more, GST registration, a clean credit file with no recent defaults or insolvency events, demonstrated trading income supported by BAS or bank statements, and new or late-model equipment purchased through a recognised dealer. Loan-to-value, term, balloon, rate and fees vary by lender, asset type, age and applicant profile. Pre‑approval is an indicative offer only and is subject to a full credit and verification check by the funding lender. The information on this page is general information only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you before acting on it.
*Pre‑approval timeframes are indicative only and subject to lender assessment and eligibility criteria.
Sources: ATO, GST hire purchase and leasing; ATO, small business pool; ATO, effective life; Effective Life Determination 2025; ATO, car cost limits; ATO, $20,000 instant asset write-off; money.com.au, chattel mortgage rates, October 2026. ATO figures last checked 2 November 2026.