Farm Equipment Finance for Australian Farms
Specialist farm equipment finance, also known as agricultural finance or farming finance, for established Australian growers, croppers and contractors, from broadacre cropping to horticulture and viticulture. BAS and trading history assessed directly. Tractors, headers, air seeders, balers, sprayers and tillage bundled into one chattel mortgage, finance lease or operating lease.
- Pre-approval typically inside 24 hours
- $0 deposit for prime applications
- Wide specialist lender panel
- New, used, dealer or private-sale machinery
30-second check. No impact on your credit score.
Choose Your Industry
Choose the category that best describes your finance requirement.
No obligation. Soft credit check only.
Built for Growers, Backed by Specialists
Whether you run a broadacre cropping enterprise, a horticulture operation, or a family farm, Equifund matches you to lenders that read farm income and machinery value correctly.
Who We Help
We arrange specialist finance across Australian agriculture.
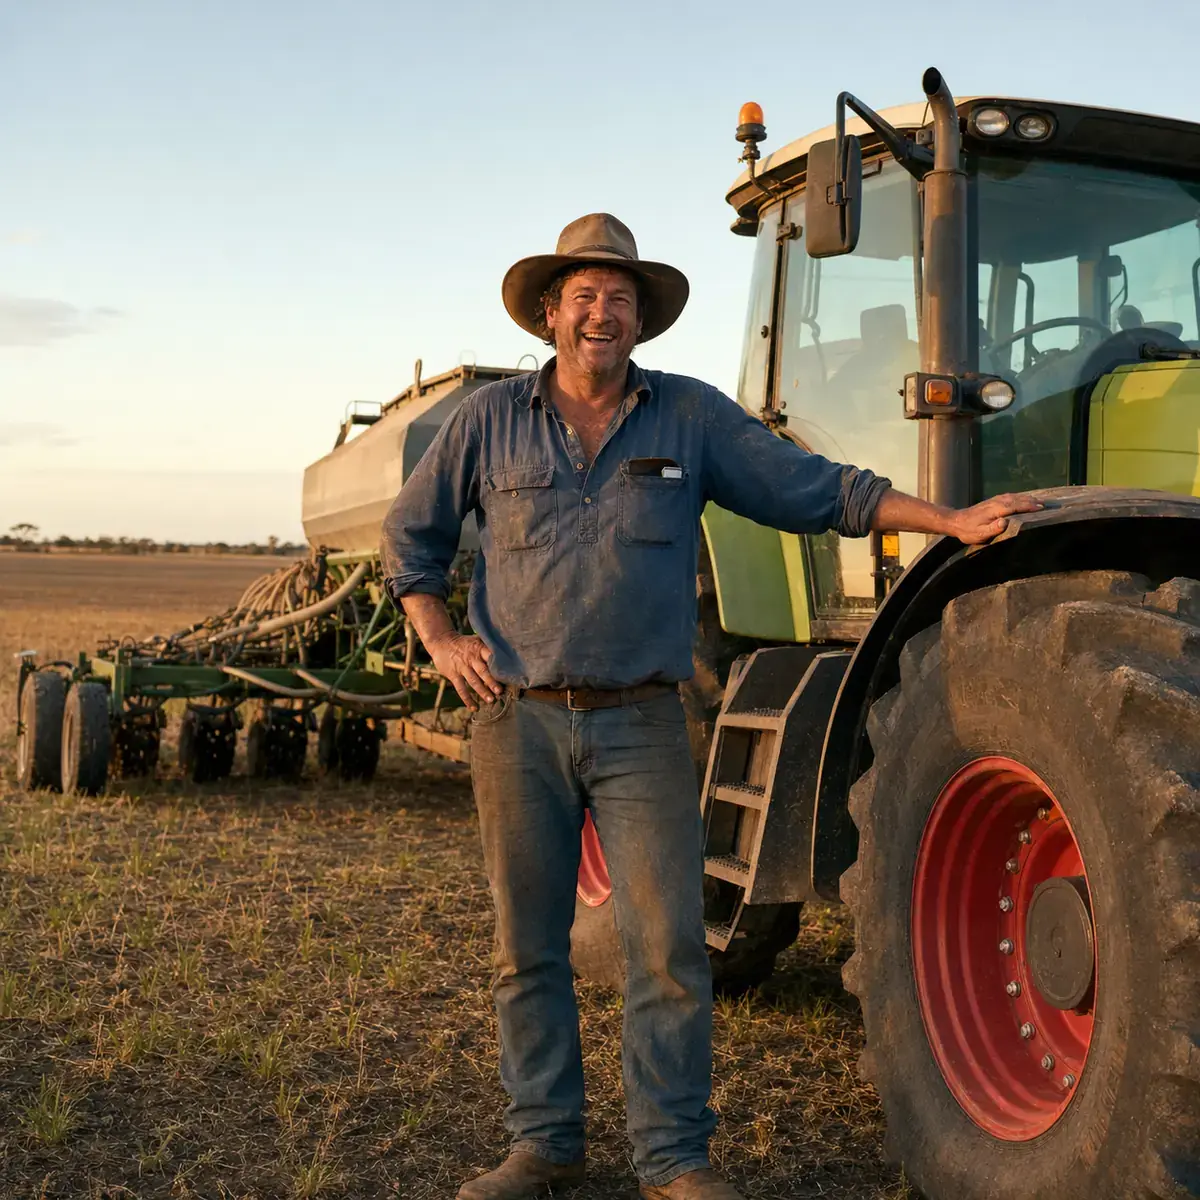 Broadacre Cropping Growers
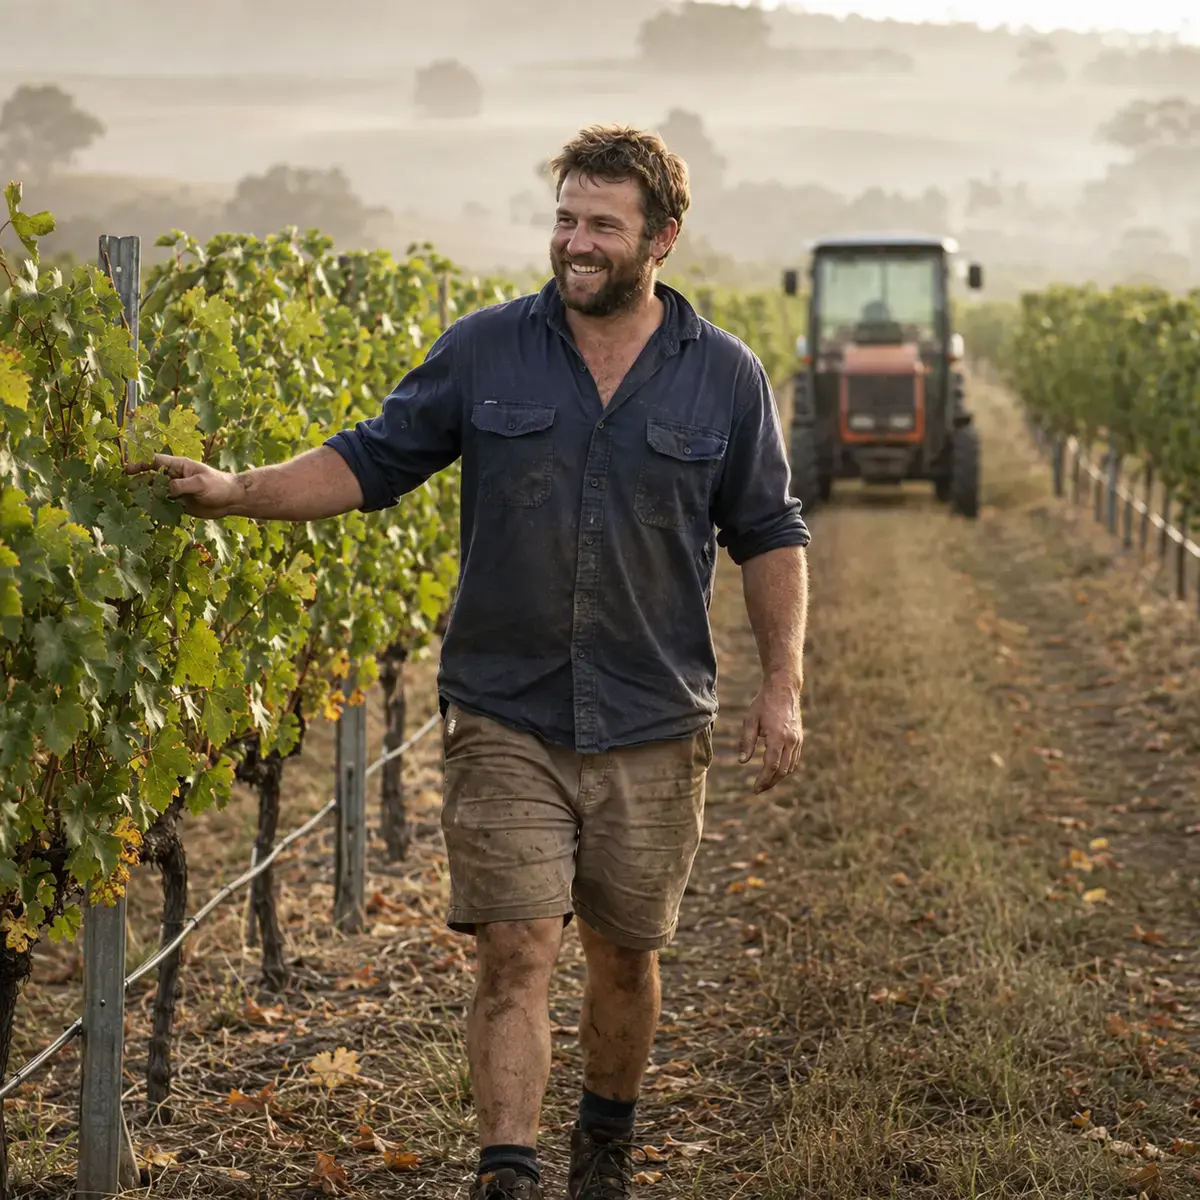 Horticulture & Viticulture Growers
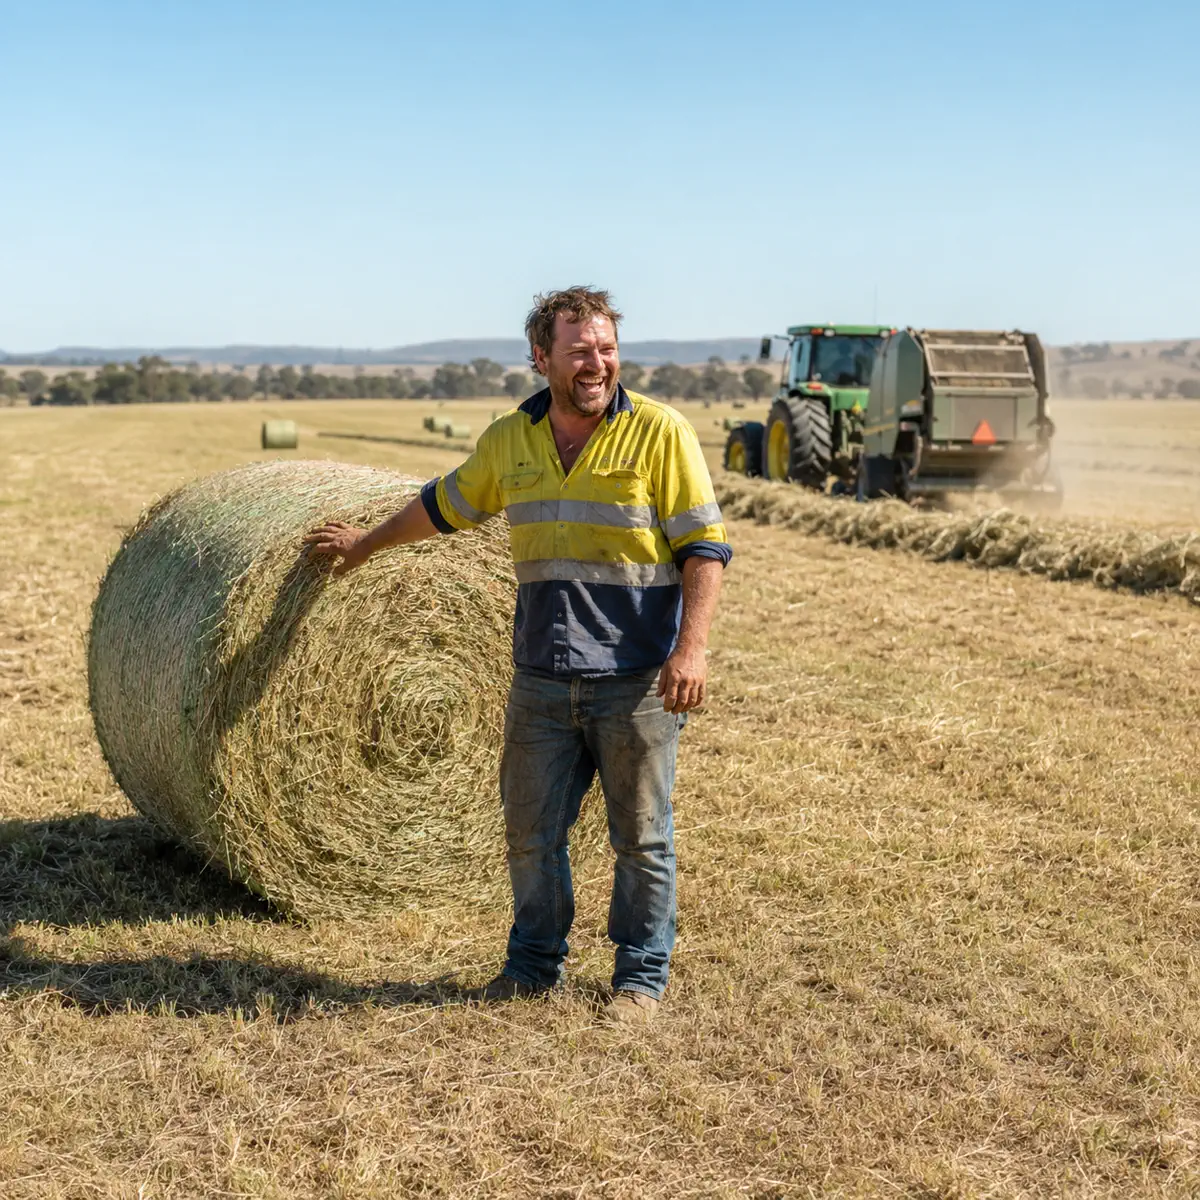 Hay & Silage Contractors
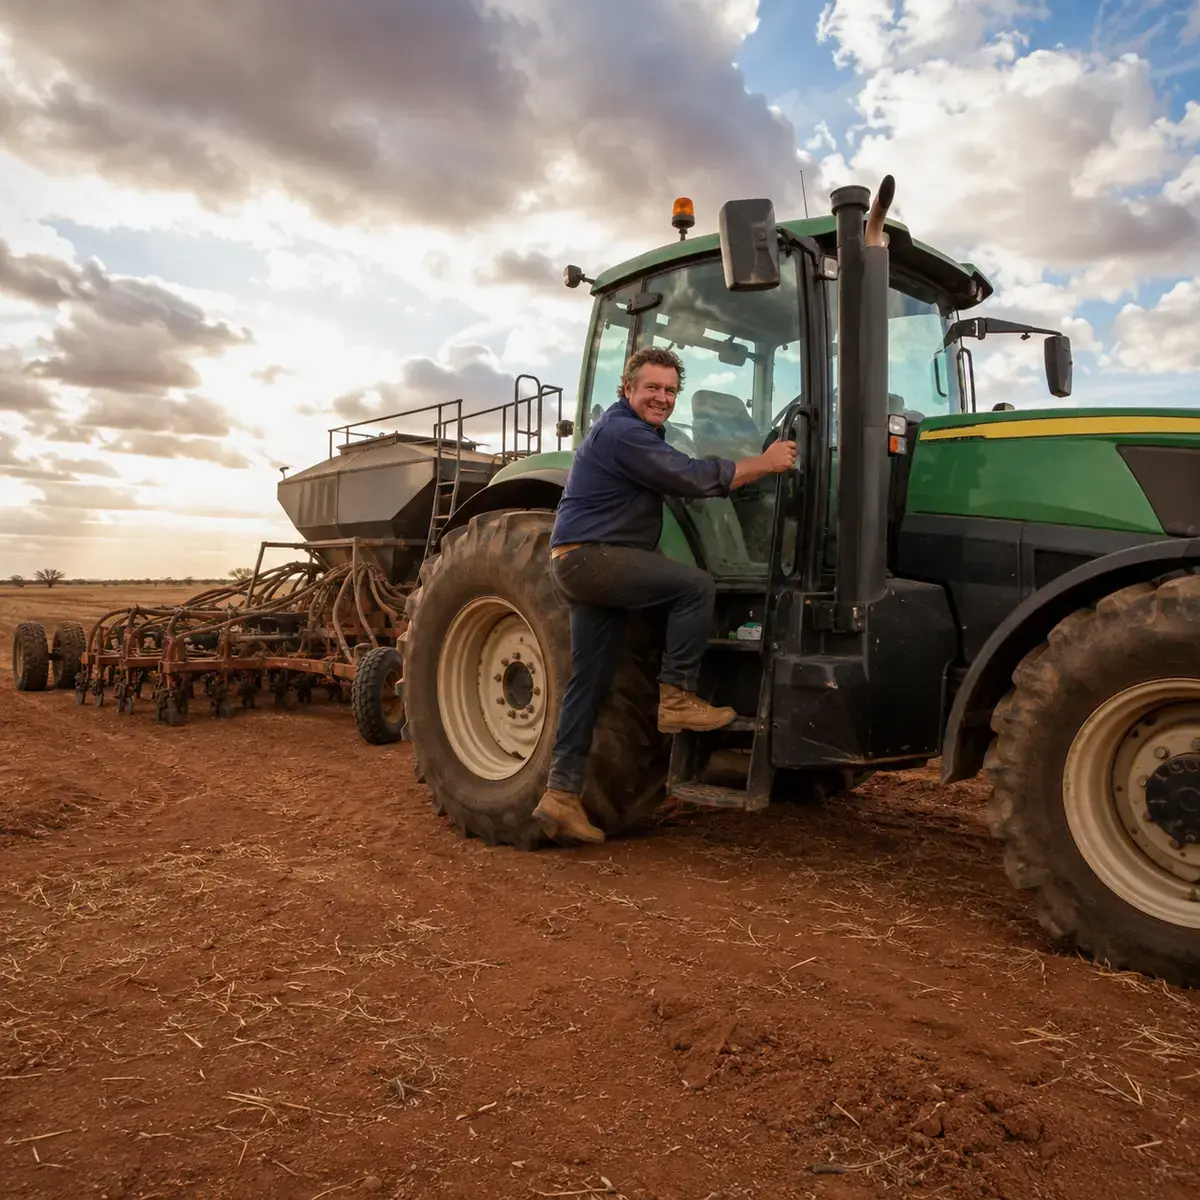 Dryland Cropping Operators
 Agricultural Contractors
Why Choose Us
Equifund arranges pre-approval typically inside 24 hours, with terms built around your farming operation.
Specialist Lenders for Farm Machinery
We Move Quickly So You Do Not Miss the Window
Repayments Structured Around Your Season
Support for Family Farms and Non-Standard Profiles
Which Farm Machinery Can I Finance?
Equifund arranges finance for the farm machinery Australian growers and contractors run, new or used, through specialist lenders for prime ABN profiles.
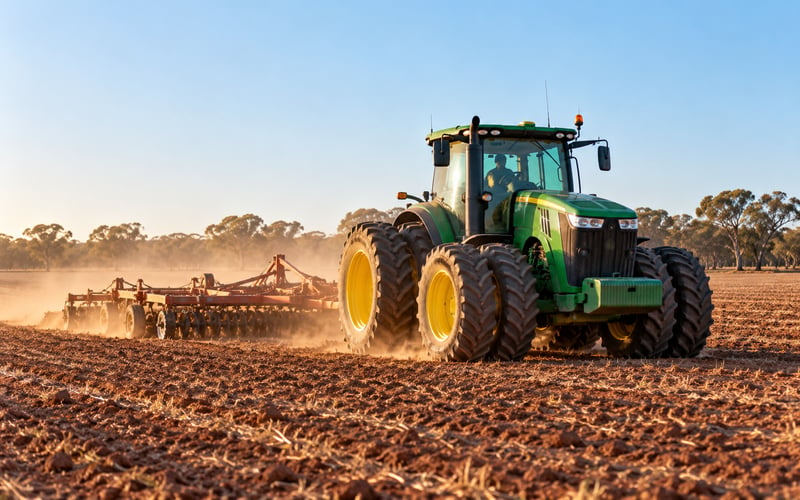
Tractors
Tractor finance for broadacre, livestock and mixed farms, from utility tractors to articulated 4WDs, new or used.
John Deere, Case IH, New Holland, Kubota, Fendt and Massey Ferguson from dealers, private sellers or clearing sales.
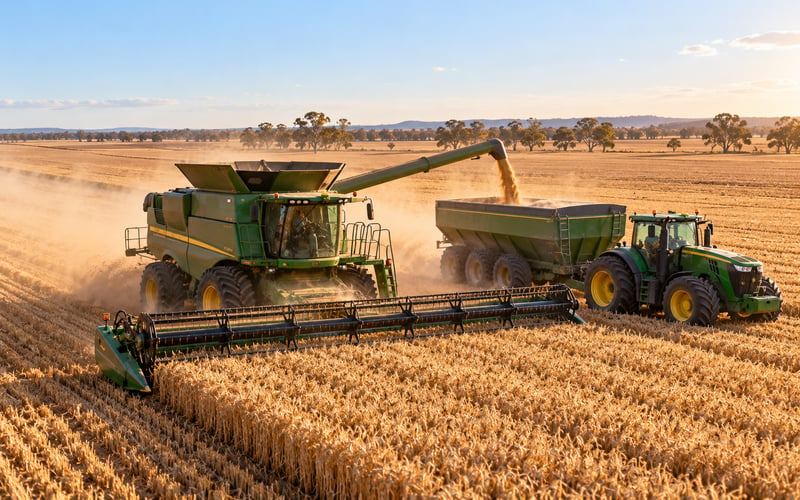
Combine Harvesters & Headers
Header and combine finance timed to harvest, with repayments that can follow your grain income.
Draper and stripper fronts, chaser bins and field bins financed with the header or on their own.
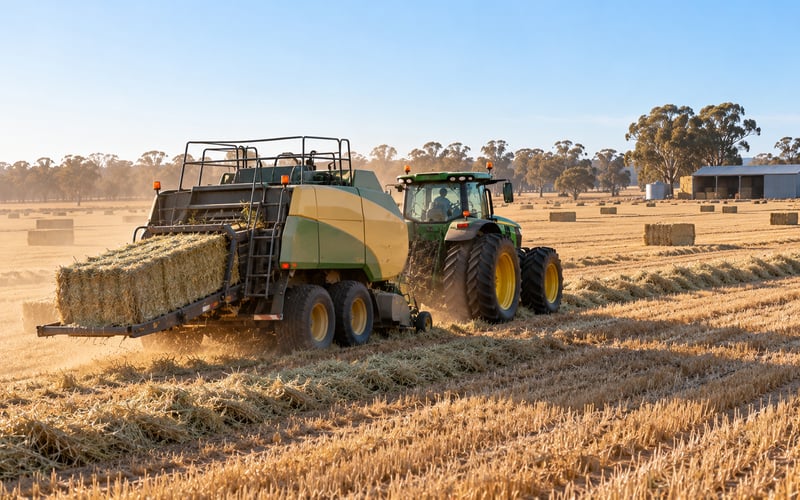
Balers & Hay Equipment
Finance for large square and round balers, mowers, rakes and tedders for hay, silage and contract baling work.
Krone, Kuhn, New Holland and Claas hay gear, new, used or bundled with a tractor.
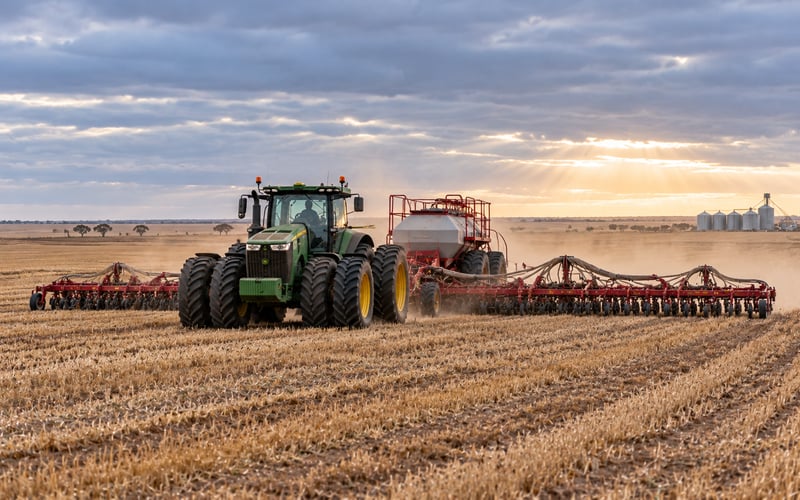
Air Seeders & Planters
Air seeder, seeding bar and precision planter finance so the new rig is on the farm before the sowing window.
Bourgault, Morris, Horwood Bagshaw and John Deere bars and carts, from a dealer or clearing sale.
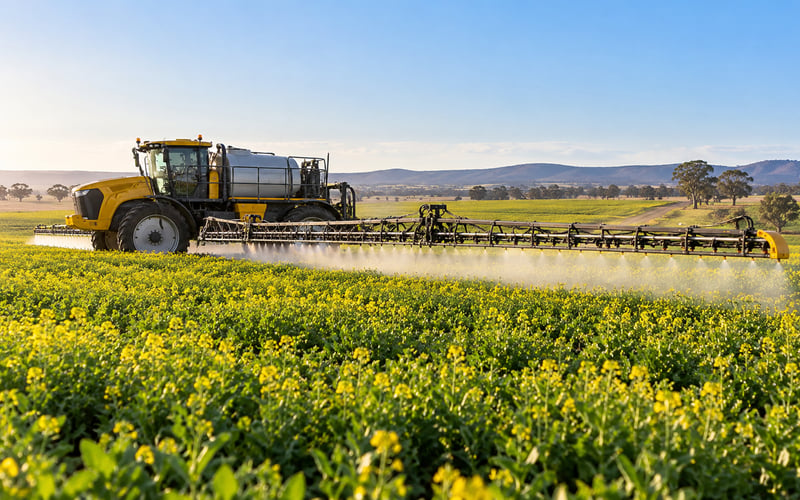
Boom Sprayers
Self-propelled and trailing boom sprayer finance for growers and spray contractors who can't afford to miss a spray window.
Goldacres, John Deere, Case IH and Croplands sprayers, new or used.
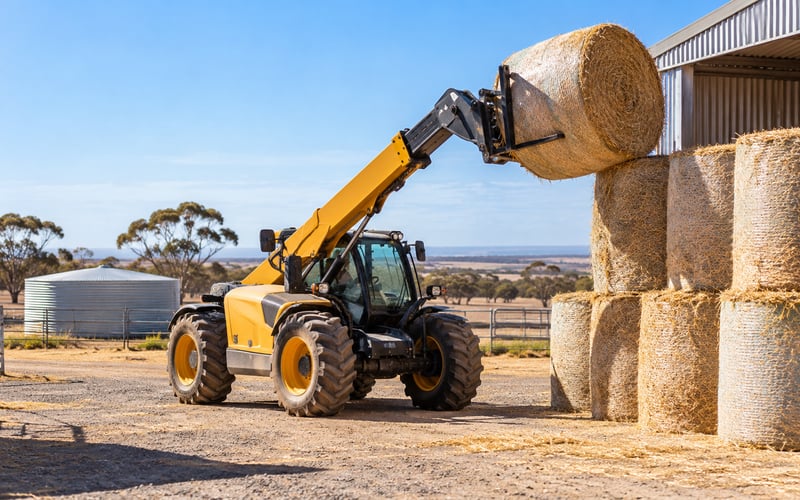
Telehandlers & Farm Loaders
Telehandler and loader finance for stacking bales, loading grain and moving feed around the yard and sheds.
Manitou, JCB, Merlo and Kubota telehandlers and wheel loaders, new or used.
Our lender panel covers all major makes, including John Deere, Case IH, New Holland, Kubota, Massey Ferguson, Fendt, Claas, Krone and Manitou. If your brand is not listed, ask us and we will check it against the lender panel.
Why Growers Choose Equifund for Farm Equipment Finance
A bank applies a generic credit template. Here is how a specialist farm equipment finance broker reads your grower income and asset value the way a bank or dealer often does not.
Equifund (Farm Equipment Finance Specialist)
Built around your deal
- Pre-approval typically inside 24 hours
- Reads grower and contract income correctly
- $0 deposit on prime applications
- Lenders on our panel can fund deals outside standard bank policy
- New, used, ex-fleet, private-sale or auction
Major Bank
Traditional lending
- Generic template for property-backed borrowers
- Often asks for full financials and property security
- Seasonal farm income can fall outside policy
- One product, limited structure flexibility
Dealer / In-house Finance
Point of sale
- Convenient when buying from the yard
- Limited to that dealer's stock and brands
- Less flexibility to structure the deal
- Not built for private-sale or auction buys
Clear Terms. No Unnecessary Complexity. Fast Outcomes.
We keep the path from application to pre-approval straightforward, so you move quickly.
Complete the Form in 60 Seconds
Tell us about your farm or ag-contracting business and the machinery you are financing through our secure online form.
Speak With a Farm Equipment Finance Specialist
An Australian farm equipment finance specialist reviews your situation and walks you through the documents needed for the lender match.
Get Pre-Approved Over the Phone
You'll have a clear pre-approval typically inside 24 hours, with rate, term and repayment structure tailored to how your season actually flows.
Settle the Loan and Take Delivery
Your specialist sources a well-matched offer and coordinates settlement with the dealer, private seller or auction house.
Real Results for Real Growers
See how Australian growers and contractors are getting the machinery they need, even with complex profiles.
What Other Equipment Can I Finance?
Equifund arranges finance for major commercial asset classes through a wide lender panel.
 Trucks
 Semi-Trailers & Trailers
 Refrigerated Trucks
 Excavators & Loaders
 Cranes & Site Machinery
 Trailer Trucks
 Tractors & Harvesters
 Yellow Goods
 Skid Steers & Access EquipmentTrucksSemi-Trailers & TrailersRefrigerated TrucksExcavators & LoadersCranes & Site MachineryTrailer TrucksTractors & HarvestersYellow GoodsSkid Steers & Access Equipment
Apply for Your Farm Equipment Finance
It takes three quick steps. An Australian farm equipment finance specialist usually gets back to you the same business day. Prefer to talk? Call 1300 464 805.
 Business Details
 Contact Information
 Asset Information
What Our Clients Have to Say
Equifund is rated 5.0 on Google by Australian business owners for fast pre-approvals, flexible terms and specialist service. 5.0 ★ · Real Google reviews
Have Questions?
Here are straight answers to the questions Australian growers and contractors ask most.
What types of farm equipment can I finance in Australia?
Equifund arranges finance for broadacre and row-crop tractors (John Deere, Case IH, New Holland, Massey Ferguson, Fendt), utility and compact tractors (Kubota), combine harvesters and headers, balers and hay equipment, air seeders and planters, boom sprayers, telehandlers and farm loaders, plus tillage gear and grain-handling infrastructure. New, used, ex-fleet, dealer, private sale or auction.
How much can I finance for farm equipment?
Recent farm facilities have ranged from $68,000 to $420,000. These include a vineyard tractor and grape harvester at $68,000, a Goldacres sprayer and tractor at $150,000, a John Deere 8R and air seeder at $310,000 and a Fendt 900 with a Bourgault air seeder at $420,000. The amount depends on the machine, your trading history and your credit profile. Smaller purchases from around $30,000 are still welcome.
Do I need to own farmland to qualify?
You don't need to own farmland to qualify. The specialist lender panel includes options that assess on the farm equipment asset, your grower contracts, harvest cycle income and trading history rather than requiring property as security. This matters most for share-farmers, contract harvesters and family farms that don't want to tie up the farm title.
Do I need a deposit?
A deposit is not always required. $0 deposit is available for prime applications, especially established growers with active grower contracts or contract harvest agreements. Other applications may need a contribution, depending on the lender.
Which finance option suits seasonal agriculture businesses?
Most seasonal growers use a chattel mortgage, since you own the equipment from settlement and repayments can be structured around harvest income rather than a flat monthly schedule. Contractors with steadier year-round income sometimes prefer a finance lease for the lower upfront cost. A specialist reviews your actual income pattern before recommending a structure. For a side-by-side view, see chattel mortgage vs lease for farm machinery.
What is the best farm equipment finance for a grain grower?
Most grain growers use a chattel mortgage, since you own the equipment from settlement, can typically claim the GST back on the purchase price and depreciation runs through your own business, while repayments are structured around harvest income rather than a fixed monthly schedule. The right structure still depends on your trading history and cash flow, so a specialist reviews your situation before recommending one. Confirm your own tax position with your accountant.
Can repayments be structured around the harvest cycle?
Seasonal repayment structures (skip months, a lump sum after harvest, or quarterly payments timed to receivals) are standard for broadacre growers and hay and lucerne producers. Specialist lenders understand seasonal farm income and can structure repayments around harvest and receival timing.
What is a chattel mortgage for farm equipment finance?
You own the equipment from the day finance settles, while your lender holds a mortgage over it as security until the loan is repaid. It's a common structure for GST-registered farming businesses, since you can typically claim the GST back on the purchase price straight away and depreciation runs through your own business. Best for GST-registered growers wanting full ownership from day one, with terms from 1 to 7 years. Confirm your own tax position with your accountant.
What is hire purchase for farm equipment finance?
With hire purchase, the lender owns the equipment for the life of the agreement and you make fixed repayments to use it, with ownership transferring to you once the final payment clears. It suits growers who want the certainty of a fixed repayment structure. Terms are flexible. Confirm your own tax position with your accountant.
What is a finance lease for farm equipment finance?
Under a finance lease, your lender retains legal title to the equipment for the term of the lease while you use it on the farm, making regular lease payments that are typically fully tax deductible. At the end of the term you can make an offer to buy the equipment, refinance the residual, or hand it back. Best for growers preferring a lease structure, with flexible terms. Confirm your own tax position with your accountant.
What is an operating lease for farm equipment finance?
An operating lease means you pay to use the equipment for an agreed term, and your lender carries the risk of its residual value, not you. It suits operations that like to keep their equipment current, since bundled servicing is often included and you simply hand it back and roll into newer equipment when the term ends. Terms typically run 3 to 5 years.
What is an unsecured business loan for farm equipment finance?
With an unsecured business loan, funds are assessed against your business's trading position rather than security over the equipment itself, so you can move quickly on a private sale or older machine a traditional lender might decline. Best for machines over 15 years old or urgent pre-season replacements, with a shorter, flexible term.
What is low-doc farm equipment finance?
Low-doc farm equipment finance is asset finance assessed on a reduced document set, typically BAS, bank statements and the grower contract, rather than full financials and tax returns. Best suited to established growers with an active ABN.
Can I claim instant asset write-off on a farm equipment purchase?
Tax treatment depends on the structure you choose and current ATO rules. The small business instant asset write-off threshold and eligibility rules are set by the ATO and change over time, so check the current rules for your business. Larger farm equipment purchases generally fall under standard depreciation. Confirm your own tax position with your accountant.
How long does Australian farm equipment finance take to settle?
Pre-approval typically comes back inside 24 hours. Settlement happens once you have signed contracts and any final lender conditions are met. Ag-specialist lenders read your grower contracts and harvest income directly, so they can structure repayments around your season on farm equipment deals.
Can I finance a used tractor, header or ex-fleet machine?
Used farm equipment, including ex-fleet, dealer demo and private sale, is all financeable. Many major banks apply age cut-offs; specialist lenders look at machine condition, hours and service history. If you are still looking for the machine itself, you can browse used farm machinery for sale and enquire on a machine and its finance in one step.
Can I finance multiple machines together?
Multi-machine deals, such as a tractor, header and sprayer for a full broadacre setup, or a tractor and multiple hay implements for a hay contractor, are common. The lender panel includes options that fund packages under a master facility against the grower contract portfolio.
Can I refinance an existing farm equipment loan?
Yes, an existing farm equipment loan can be refinanced. Refinance is common when the current loan was settled at high rates, has an unfavourable structure, or you want to consolidate several machines into one master facility.
What is the best way to finance a tractor in Australia?
The best structure depends on whether you want to own the tractor from day one, which points to a chattel mortgage, or keep repayments lower with flexible end-of-term options, which points to a finance lease or operating lease. Equifund matches you to a specialist lender from a wide panel based on your ABN history and the machine you are financing.
$0 deposit is available for prime credit applications only. Typical prime criteria include an active ABN of 2 years or more, GST registration, a clean credit file with no recent defaults or insolvency events, demonstrated trading income supported by BAS, bank statements or farm financials, and new or late-model farm equipment purchased through a recognised dealer. Loan-to-value, term, balloon, rate, fees and seasonal repayment options vary by lender, asset type, age and applicant profile. Pre-approval is an indicative offer only and is subject to a full credit and verification check by the funding lender. The information on this page is general information only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you before acting on it.