Equipment finance rates for established Australian businesses
Published rates start from around 7.5% p.a. and are usually fixed for the term. Estimate weekly, fortnightly and monthly repayments on business equipment loans, then see what moves your rate.Indicative only, not a quote or offer.
Estimate your repayments
Tell us the asset and a few details about your business, and we'll estimate your rate and repayment as you go.
We estimate an indicative rate from these answers, so you do not need to know it.
or $0/week · $0/fortnight
As a GST-registered business, you may be able to claim the GST on the purchase, depending on the finance structure. Speak with your accountant.
Get My Personalised QuoteNo obligation. Asking will not affect your credit score.
Estimates only. Not a quote or offer. The indicative rate is a guide based on your answers; your actual rate, fees and repayment are set by the lender and subject to lender assessment and eligibility criteria.
What moves your equipment finance rate
Equipment finance rates are usually fixed for the term. Where yours lands depends on the lender's cost of funds and how it reads your business.
Your credit file
A clean file usually prices sharpest. Paid defaults or past arrears narrow the lender pool.
Time trading
Two or more years on the same ABN, with GST registration, usually opens the widest choice of lenders.
The asset's age and type
New and late-model assets from a dealer usually price better than older or private-sale assets.
Deposit or trade-in
Money down lowers the amount financed and can improve the rate a lender offers.
Amount, term and balloon
Lenders price the whole structure, so compare the total cost in dollars, not just the rate.
Your documents
Up-to-date BAS and bank statements help. Low-doc options can be priced differently.
Sources: money.com.au, chattel mortgage rates; money.com.au, equipment finance; RBA, cash rate. Checked 5 November 2026. Published rates are a guide only, not a quote or offer. Your rate is set by the lender after it assesses your application.
Make sense of your numbers
No jargon and no pressure. Pick a topic below and we will explain it in plain English, the way we would over a coffee, so you can make a confident call.
Indicative rate
A friendly guide, not a locked-in number. Your real rate depends on little things like how long you have been trading and the asset itself. Finding you a sharp one is our job, not yours, and you never have to work it out alone.
Talk this through with a specialistBalloon or residual
A slice of the loan you set aside for the very end, which keeps your weekly payments lighter today. When you get there you can pay it out, refinance, or trade the asset in, and we walk you through whichever suits you best.
Talk this through with a specialistChattel mortgage
The most common, straightforward way to finance business gear. The asset is yours from day one, and it often comes with handy GST and tax perks your accountant will love. We handle the paperwork.
Talk this through with a specialistBigger deposit or trade-in
A deposit, or trading in something you already own, means a smaller amount to finance and less interest along the way. Even a modest amount makes a difference, and there is no minimum you have to hit.
Talk this through with a specialistA longer loan term
Spreading the loan over more years makes each payment smaller and easier to fit around your income. You pay a little more for the breathing room, and that is a perfectly normal, sensible trade to make.
Talk this through with a specialistAdding a balloon
Leaving a lump sum for the end keeps your weekly payments lower now. Plenty of businesses do it to keep repayments manageable, and we help you plan for that final payment well in advance.
Talk this through with a specialistGST on the purchase
If you are registered for GST, you may be able to claim the GST on the asset, depending on how the finance is structured. Your accountant can confirm exactly what applies to you.
Talk this through with a specialistDepreciation and tax
Business assets can often be depreciated, and the interest may be deductible. It is worth a quick chat with your accountant to make the most of it at tax time.
Talk this through with a specialistNo impact to ask
Getting an estimate or asking us a question does not touch your credit score. You are only formally assessed once you choose to go ahead with an application.
Talk this through with a specialistNot sure what is right for you? That is what we are here for.
Tell us a little about your business and we will shape the deposit, term and balloon around how your business earns, then do the lender shopping for you across our panel. There is no obligation, and simply asking will not affect your credit score.
These figures are a friendly estimate to help you plan, not a formal quote or offer. We confirm your real numbers with the lender and walk you through every one before you decide anything.
From estimate to settlement
You do the estimate. We do the shopping around, the paperwork and the lender match. There is no impact on your credit score to enquire.
- 01Estimate your repayment
- 02Send a few business details
- 03We match you across a wide lender panel
- 04Get your indicative pre-approval
- 05Sign and settle
Why operators skip the bank queue
The same deal, four different doors. Here is how a specialist broker stacks up against the alternatives.
Equifund
Specialist broker
- Wide lender panel on one form
- Pre-approval often in 24 hours*
- Property often not needed
- Used and older assets welcome
- Low-doc and new ABN options
- Your broker does the legwork
- A dedicated specialist, start to finish
Your bank
Direct to one lender
- One lender, one view
- Days to weeks
- Property often required
- Restrictive on used assets
- Low-doc rarely
- You do the legwork
- Branch queue or call centre
Single lender
Direct to one financier
- One lender, one product
- Several days
- Sometimes required
- Limited appetite
- Case by case
- You do the legwork
- Call centre
Compare sites
A lead form
- A handful of lenders
- Varies by who calls
- Varies
- Limited
- Rarely
- You do the legwork
- Self-serve, then sales calls
Finance we have recently arranged
A snapshot of finance we have recently arranged across the industries we specialise in, from transport to agriculture.
Representative of recent Equifund settlements. Amounts are indicative and client details are changed for privacy. Not a quote or offer.
What our clients have to say
Australian business owners trust us for fast turnaround, flexible terms and genuine service.
Equipment finance across every core industry
From transport to earthmoving, the estimate above works across the industries we specialise in. Pick yours to see finance built around your gear.
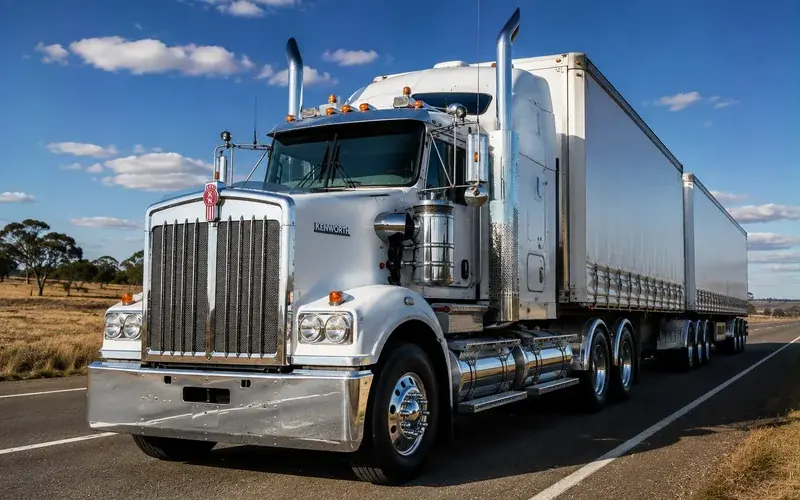
Transport & Logistics
Trucks, prime movers and trailers for owner-operators and fleets.
Explore ›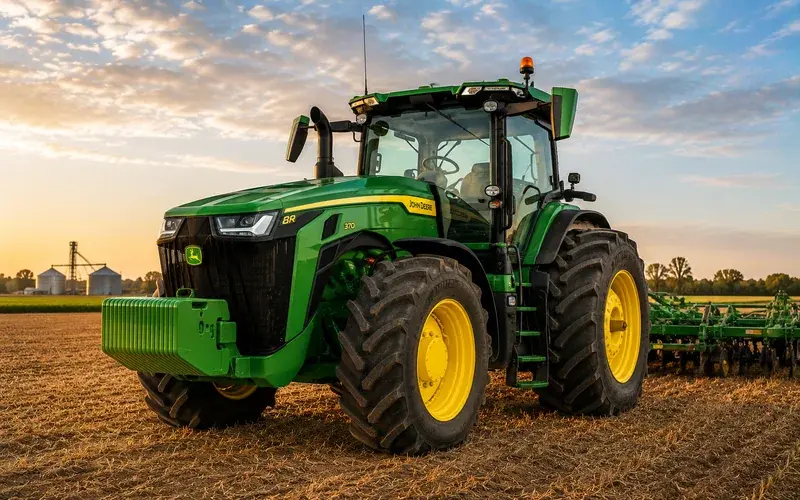
Farming & Agriculture
Tractors, headers, implements and machinery that work the land.
Explore ›
Construction & Civil
Cranes, forklifts, compaction and site plant for builders and contractors.
Explore ›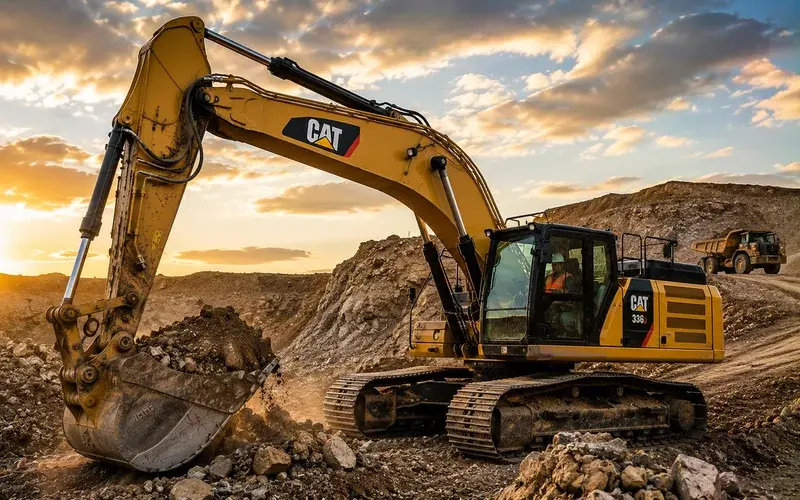
Earthmoving & Mining
Excavators, loaders, skid steers and dozers for civil and resources.
Explore ›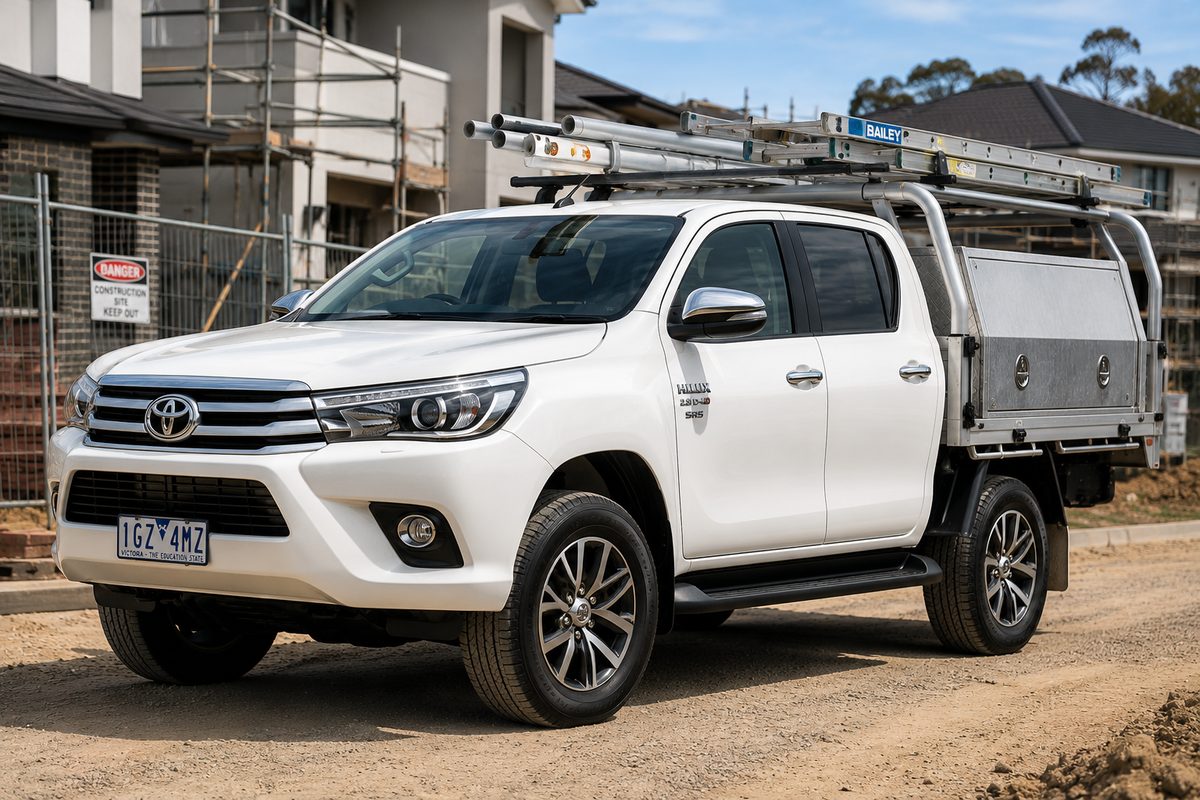
Light Commercial Vehicles
Utes, vans and light trucks that keep the business on the road.
Explore ›Ways to sharpen your finance rate
A few simple moves can widen your lender options and sharpen your rate. Here is what lenders actually look for.

The stronger your file, the sharper your options
Check Where I StandThese are general pointers to help you prepare, not a promise of finance. Tell us your situation and a specialist will show you exactly where you stand across our lender panel.
Common equipment finance rate questions
Straight answers to the questions businesses ask most.
What are equipment finance rates in Australia right now?
Published chattel mortgage rates in Australia start from around 7.5% p.a. and can reach 20% p.a. or higher for some borrowers, depending on the credit profile and the asset (money.com.au, November 2026). Equipment finance rates are usually fixed for the term. Your own rate is set by the lender after it assesses your application. Indicative only, not a quote or offer.
How are equipment finance rates set?
Lenders set equipment finance rates from their own cost of funds, which moves with the RBA cash rate, plus a margin. They then adjust for your credit file, time trading, deposit, loan amount, the asset's age and type, and the finance structure. A new machine bought from a dealer usually prices better than an older one bought privately.
Did the November 2026 RBA rate rise change equipment finance rates?
The RBA lifted the cash rate by 0.25 percentage points to 4.85% from 4 November 2026. Equipment finance rates are usually fixed, so existing contracts keep their rate, while lenders may reprice new loans as their cost of funds changes. If you hold a quote or pre-approval, check whether the rate is locked and for how long.
Are equipment finance rates fixed or variable?
Equipment finance rates in Australia are usually fixed for the life of the loan, so the repayment stays the same for the whole term. That makes repayments easy to plan around, but paying out early can involve break costs, so check the payout terms before you sign.
Why does equipment finance often have no comparison rate?
Comparison rates are required under the National Credit Code for consumer credit, so business finance often comes without one. Compare offers on the total cost in dollars instead: the rate, fees, term, balloon and any early payout costs, not just the headline rate.
Does the age of the equipment change the rate?
The age of the equipment usually changes the rate. New and late-model assets generally attract sharper pricing, while older assets can carry a higher rate, a shorter maximum term or a deposit requirement, because the lender's security is worth less. Subject to lender assessment.
How can I get a lower equipment finance rate?
A lower equipment finance rate usually comes from a stronger file: a clean credit history, up-to-date BAS and bank statements, two or more years of trading, a deposit or trade-in, and a newer asset from a dealer. Comparing lenders matters too, which is what a broker such as Equifund does across its panel. Subject to lender assessment.
Do newer businesses pay higher equipment finance rates?
Newer businesses can pay higher equipment finance rates. Some specialist lenders consider ABNs registered for less than 2 years, often with a deposit, GST registration, a clean credit file or experience in the same industry, and pricing reflects the extra risk. Subject to lender assessment.
How are equipment finance repayments calculated?
Repayments are worked out by spreading the amount financed over the term at the interest rate, then adjusting for any balloon left owing at the end. The amount financed is the price less any deposit or trade-in. The calculator above shows indicative weekly, fortnightly and monthly figures. Actual repayments are set by the lender.
Does a balloon change the interest rate?
A balloon usually changes the repayment and the total interest rather than the rate itself. It lowers the regular repayment by leaving a lump sum owing at the end, which means paying interest on a larger balance for longer. Lenders set the maximum balloon by term and the asset's age.
What is a chattel mortgage?
A chattel mortgage is a business loan where you own the asset from day one and the lender holds security over it until the loan is repaid. A GST-registered business can generally claim the GST in the purchase price upfront, and the interest and depreciation are generally deductible for business use. Confirm the tax treatment with your accountant.
Can repayments be weekly, fortnightly or monthly?
Many commercial lenders offer weekly, fortnightly or monthly repayments, so you can match them to how your business is paid. The calculator above shows all three. The total interest over the term is broadly similar across frequencies.
How much deposit do I need for equipment finance?
No-deposit equipment finance may be available for prime applications, subject to lender assessment. Lenders may ask for a deposit if your credit file is impaired, your ABN is newer or the asset is older or bought privately. A deposit can also widen the lender pool and improve the rate offered.
Can I finance used or private-sale equipment?
Used equipment can be financed, including dealer, auction and private sales. Lenders look at the asset's age, condition and value, and older or privately bought assets may need extra checks, a deposit or a shorter term. Subject to lender assessment.
How fast can equipment finance be pre-approved?
Equipment finance pre-approval is typically issued within 24 hours* once your BAS or bank statements and the asset details are provided, subject to lender assessment. Settlement timing then depends on the lender, the seller and your documents.
Will checking my rate affect my credit score?
Checking your rate with Equifund does not affect your credit score, because an initial eligibility check is not a credit application. A formal application with a lender does involve a credit assessment. Your specialist will explain each step before anything is submitted, so there are no surprises.

Apply for equipment finance
Tell us a few details and an Australian finance specialist gets back to you, usually the same business day.
Business Details
Contact Information
Asset Information
Application received
Thanks, an Australian finance specialist will be in touch, usually the same business day.